@Antti_Viljakainen, do you know if the metal price forecasts have been raised?
Silver, in particular, seems to be rallying quite a bit.
Of course, it must be noted that this will only benefit Sotkamo Silver later.
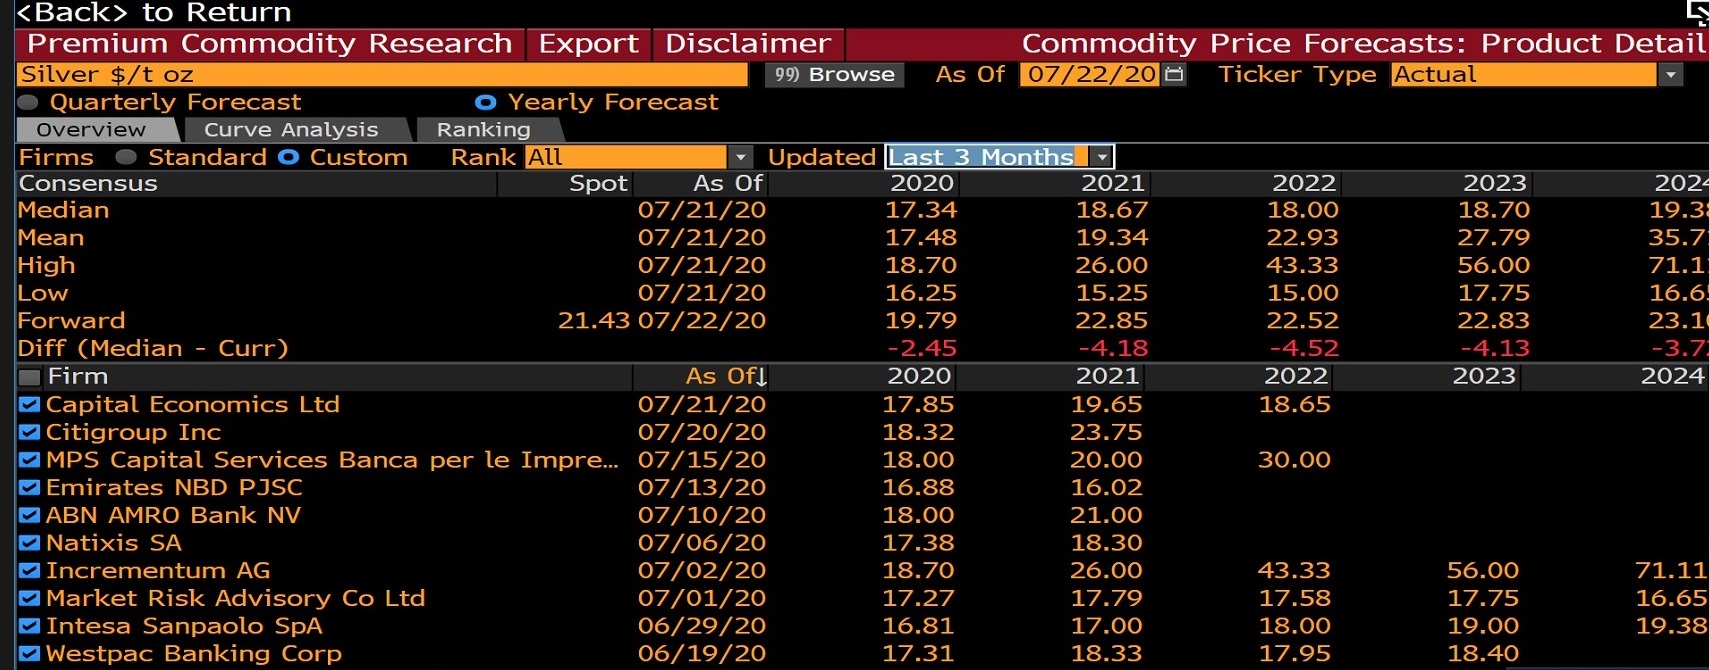
Below is a picture of Bloomberg’s 3-month price forecasts, updated within the last 3 months, which I also use as a basis for my Sotkamo Silver forecasts. They are almost at the same level as at the end of May when the previous update was made, so this rally has pretty much caught commodity analysts with their pants down. The appreciation of silver is, of course, excellent news for Sotkamo Silver!
3 Likes
In Inderes’ grapevine, this normalization of the gold/silver ratio has been expected for a while now. The coronavirus has also hit the largest silver-producing countries hard in recent months, while industrial demand has started to recover.
It’s a pity that SoSi hasn’t yet been able to show that production costs would remain under control. Even with these high silver prices, I don’t think the company offers enough return for the risk as a long-term investment, even if the cash crisis is avoided. Of course, if the price of silver continues to rise and we get a proper price spike… 
1 Like
Yep. Even though the market is now providing strong tailwinds, the role of their own game is still central. In Q1’20 and Q4’19, costs accumulated to roughly 80 MSEK/Q. If they can’t bring these levels down, then the silver price clearly needs to be well over twenty to ensure that cash flow is sufficient for interest expenses, necessary maintenance and development investments, and setting aside cash for debt repayment. So, there is still risk remaining in the company. An interesting Q2 is therefore expected in August. The volume side of things has probably played out more or less according to plan so far, as the full-year production guidance remains unchanged, but that cost level is the most interesting factor among the things within the company’s control.
In principle, with these factors, a significant price spike in silver could be possible (and the current price justified in the longer perspective), especially if gold continues its rally driven by money printing at the same time. However, I don’t have any proper supply/demand model for silver, so I don’t dare/know how to predict without a proper fundamental analysis, as movements or their absence, especially in silver, can be quite surprising. Of course, I need to actively monitor potential forecast changes from raw material analysts and their arguments for both gold and silver.
4 Likes
SoSi despite the incredible price spike in silver:
3 Likes
My view on the price of silver is more bullish than Viljakainen’s analysis. I consider it likely that the price of silver/metals will only continue to rise due to, for example, the market situation and central banks printing money. Technically, the situation looks similar to 2009-2010, when silver rose to almost 50 in 2011.
In Q2, the average price of silver was around 15. Now we are already double that! If the Q3 result doesn’t convince, then nothing will.
Before corona, Inderes’ target was 0.44c, and in my opinion, the situation at the moment is at least as good, assuming that costs can be kept under control. The stock seems to be acceptable at least abroad. At least through GSI, there has been a lot of buying recently, from what I have been following in Nordnet’s statistics. Does anyone know of a better place to track through which certain stock purchases have been made?
3 Likes
Silver’s spot price is already 28 USD/oz, but SOSI is still in the starting blocks. The price of the main product (silver) has risen by about 50% in a month, which should be a phenomenal driver for this company. Where does the pessimism come from? Is the ghost of Talvivaara hanging over the company? If the company cannot get its production reasonably in order, then some international mining company will surely pay well for it (which would also solve the challenge of a “single mine company”). My understanding is that silver is often a by-product of base metal mining companies, but in this company’s mix, silver accounts for 60%, and gold is not insignificant either, having risen to record highs recently.
1 Like
Wow, you’re really energetic today. Did you read yesterday’s earnings report?
I think the most important thing to read in the quarterly report is that production is running smoothly. The CEO confirmed the previously given production guidance for silver. Q2 was full of turmoil and plagued by an exceptionally low silver price, but now the silver price has “normalized” to a much healthier level. I completely agree with 'fzifi’s view that the Company should be valued at least at the same level as at the beginning of the year. Well, the market will decide what ultimately happens.
1 Like
Did you look at how much the investments were? And the mining costs in that column again?
Regarding precious metals, I mainly rely on Bloomberg’s consensus (though for H2’20, I exceptionally raised the forecasts this time, as the difference between forecasts and spot prices had become quite large), so I don’t just throw parameters into the model out of thin air (the reasons for this have been discussed above). It will be interesting to see if Bloomberg’s consensus forecasts will eventually catch up with spot prices, or if the analysts participating in the consensus already see a bubble in metals after an almost vertical rise.
This is a completely possible scenario, even though assessing the technical side is even more difficult than fundamental analysis of silver. From a fundamental perspective, investors are currently driving silver demand (rising gold prices, weakened USD, low real interest rates, etc.), and the challenges arising from the COVID-19 pandemic on the supply side create a double leverage. Supply is likely to normalize at some point as mines in, for example, South America, which were shut down due to the pandemic, get back into production, but new mines and thus a massive increase in supply that would normalize the situation are unlikely to emerge. The persistence of strong investor demand is then more difficult to assess, but in the prevailing economic and political conditions, it could certainly last for a long time.
Of course, from a longer-term perspective, I am a bit skeptical that a business like the mining industry would become incredibly profitable for virtually all producers for years (as gold and silver production would be permanently if gold prices were well over two thousand dollars and silver over 30 USD/oz). Usually, counterforces tend to emerge from somewhere that normalize situations. This is also important for Sotkamo Silver, as our valuation model considers the entire life cycle of the company, not just the results of a single year. Of course, even a 1-2 year price peak would be an extremely good thing for the company to allow the awkwardly high debt to melt away.
Yes, they have to be. The cash flow can’t really support anything else. This price rally came at the eleventh hour for Sotkamo Silver, and of course, it’s good!
That was the case. It’s good to remember, however, that relative to the expectations at the beginning of the year, Sotkamo Silver’s cost side has been a heavy disappointment, especially in Q4 and Q1, and Q2 was not good either in terms of costs. Weak results due to high costs and investments have inflated net debt (which impacts our sum-of-the-parts model behind our target price). At the beginning of the year, the expectation was that the company would perform excellently according to pre-feasibility estimates with silver spot prices of 16-18 USD/oz and a EUR/USD exchange rate of 1.1, but now the situation is that below 20 USD/oz and without a reduction in cost levels, Sotkamo Silver would be in quite serious trouble with its cash flow and debts. A higher cost position, in turn, makes Sotkamo Silver a riskier and more speculative investment target than anticipated at the beginning of the year (i.e., the company is more dependent on the market). In addition, the share issue in the spring also significantly increased the number of shares, which has also eroded the basis for the target price. These are probably also reasons why the leverage from the silver price has not translated into Sotkamo Silver in the same way as into many other silver companies.
Volume is indeed good for precious metals in Q2. However, costs are still unpleasantly high and significantly above the levels estimated in the pre-feasibility studies, so there is still work to be done. If current prices hold or continue to rise, Sotkamo Silver will certainly be forgiven a lot in terms of costs, but the increase in the cost position on the cost curve, as well as certain balance sheet weaknesses and limited liquidity, shift the company’s investment profile in a riskier direction. Some may, of course, like this (in principle, the leverage to the metal price should be higher in the upper part of the cost curve), but in my opinion, the expected return must be truly robust if, in addition to the chronically high risks of the mining business, significant company-specific risks are also added.
Congratulations to those whose view on the price of silver has been accurate and has generated returns with any instrument! Although our view is somewhat critical, I naturally wish Sotkamo Silver all the best and hope the company can take advantage of the strong market and develop the mine.
8 Likes
Good analysis from Viljakainen, which helps me calm down a little about the stock as well. Although, at a time when there seems to be a bubble wherever you turn your head, this feels like “a true gift from the trading Gods”, to quote Peter Schiff.
In addition to rambling, a couple of pertinent points:
-
Doesn’t a healthy price level for silver and gold benefit the company throughout its operations? Easier to attract skilled labor, easier to arrange financing, etc. A silver price near the $30/oz level should work wonders, especially for a company in the early stages of its life cycle like this one. I’m not quite so scared by all the operational softness in Q2, because it should be clear to everyone living on Earth what happened then.
-
In my opinion, the stock also has a significant option element, especially for things that happen after the forecast period. Let’s say silver jumps into the $50-100 USD/oz range, which means that the company’s current mine and other claims would have significantly more economically viable mining potential than previously assumed.
Is there any information on how long this mining company can continue mining without a new environmental permit? Will there be sanctions for this exceeding?
http://www.silver.fi/sivu/fi/press_releases/?show=one&lang=fi&id=18D45B0D5C2D5C38
During H1, 266,000 tons were mined (“Milled tonnes during first half were about 266,000”). They’ve really gotten to work there if the 500,000 mark is broken already in August. This is pure speculation, but does the company have better information that the decision on a new environmental permit will be coming soon? They can’t just run the mine that hard for the joy of getting sanctions, can they??
That’s how it is. The recent rise in silver or other metal prices has probably not yet affected the Nordic banks’ reluctance (risk) to finance mines in any way.
It depends on the authorities, of course, but I don’t expect any reactions beyond a wagging finger. The new permit has been under consideration for a (perhaps even unlawfully) long time. Last year, the total excavation permit condition was exceeded, and Sotkamo Silver didn’t receive any major penalties for it.
These are two different figures. The permit condition applies to total excavation (incl. ore and waste rock), while in interim reports, the company reports ore fed to the concentrator. It’s likely that the mine has continued at roughly the same production rate during the summer as in the beginning of the year.
I believe that the company and the authorities are having some kind of dialogue about the conditions, the fulfillment of conditions, and the schedules, and thus Sotkamo Silver probably has some idea of the state of the permit process. In addition, the permit has been under consideration since the end of 2018, so it must be completed soon. I suppose a new permit will be issued shortly, but there is certainly some uncertainty related to the conditions, although I don’t expect the permit conditions to cause major “forced investments.” On the other hand, the permit is a prerequisite for maintaining the current production level, and I also don’t believe that the production volume will increase rapidly due to the permit. However, it may be possible to improve production efficiency to some extent with the new permit, at least in the longer term (incl. the permit being a prerequisite for commissioning the pre-concentrator planned to be integrated into the process).
4 Likes
@Antti_Viljakainen, you’ve refrained from using the consensus price of raw materials in your forecasts, which is a perfectly valid approach. However, the market price has now risen significantly and is, even with moving averages, higher than the consensus previously used in forecasts. Even if the price of silver were to collapse tomorrow to early-year levels, it is at least probable that higher delivery prices will be achieved for Q3 deliveries. I don’t know about the timing of delivery batches, though – how many are there per quarter? The price of a mining batch was retroactively formed from a 1-2 month average of the spot price, or something like that?
Could you therefore start to evaluate scenarios for how SoSi would perform over periods of months or quarters at these price levels?
3 Likes
Silver Miners’ Q2’20 Fundamentals Problems in Mexico and Peru.
3 Likes
Thanks, Akseli_Gran, for the link! A very informative article 
Sotkamo Silver 10-bagger?
Those gold/silver YouTube channels usually don’t produce very useful or reliable information, as most of their content is largely wishful thinking without a basis. I’m not commenting on the video’s topic here, but rather as a general observation about those videos.
I would recommend that those considering investing in SoSi familiarize themselves with the silver markets, for example, through The Silver Institute. They regularly publish high-quality texts on silver. For an investor less familiar with silver, an excellent place to start is the 2020 World Silver Survey.
Although forecasting is incredibly challenging and forecasts often go completely wrong, I believe that by using high-quality data and combining it with other available information, it is sometimes possible to gain an informational advantage over the markets. For example, like this:
May 13:
August 28:
However, those considering investing in SoSi should remember that it is a very indebted and high-cost mine relying on a single card. Even a high silver price may not bring comfort if the company is weak:
3 Likes