Let’s open a dedicated thread for the IT consulting company Siili. As an analyst, I will participate in the discussions here to the best of my ability, and you can also forward questions you’d like to ask the management.
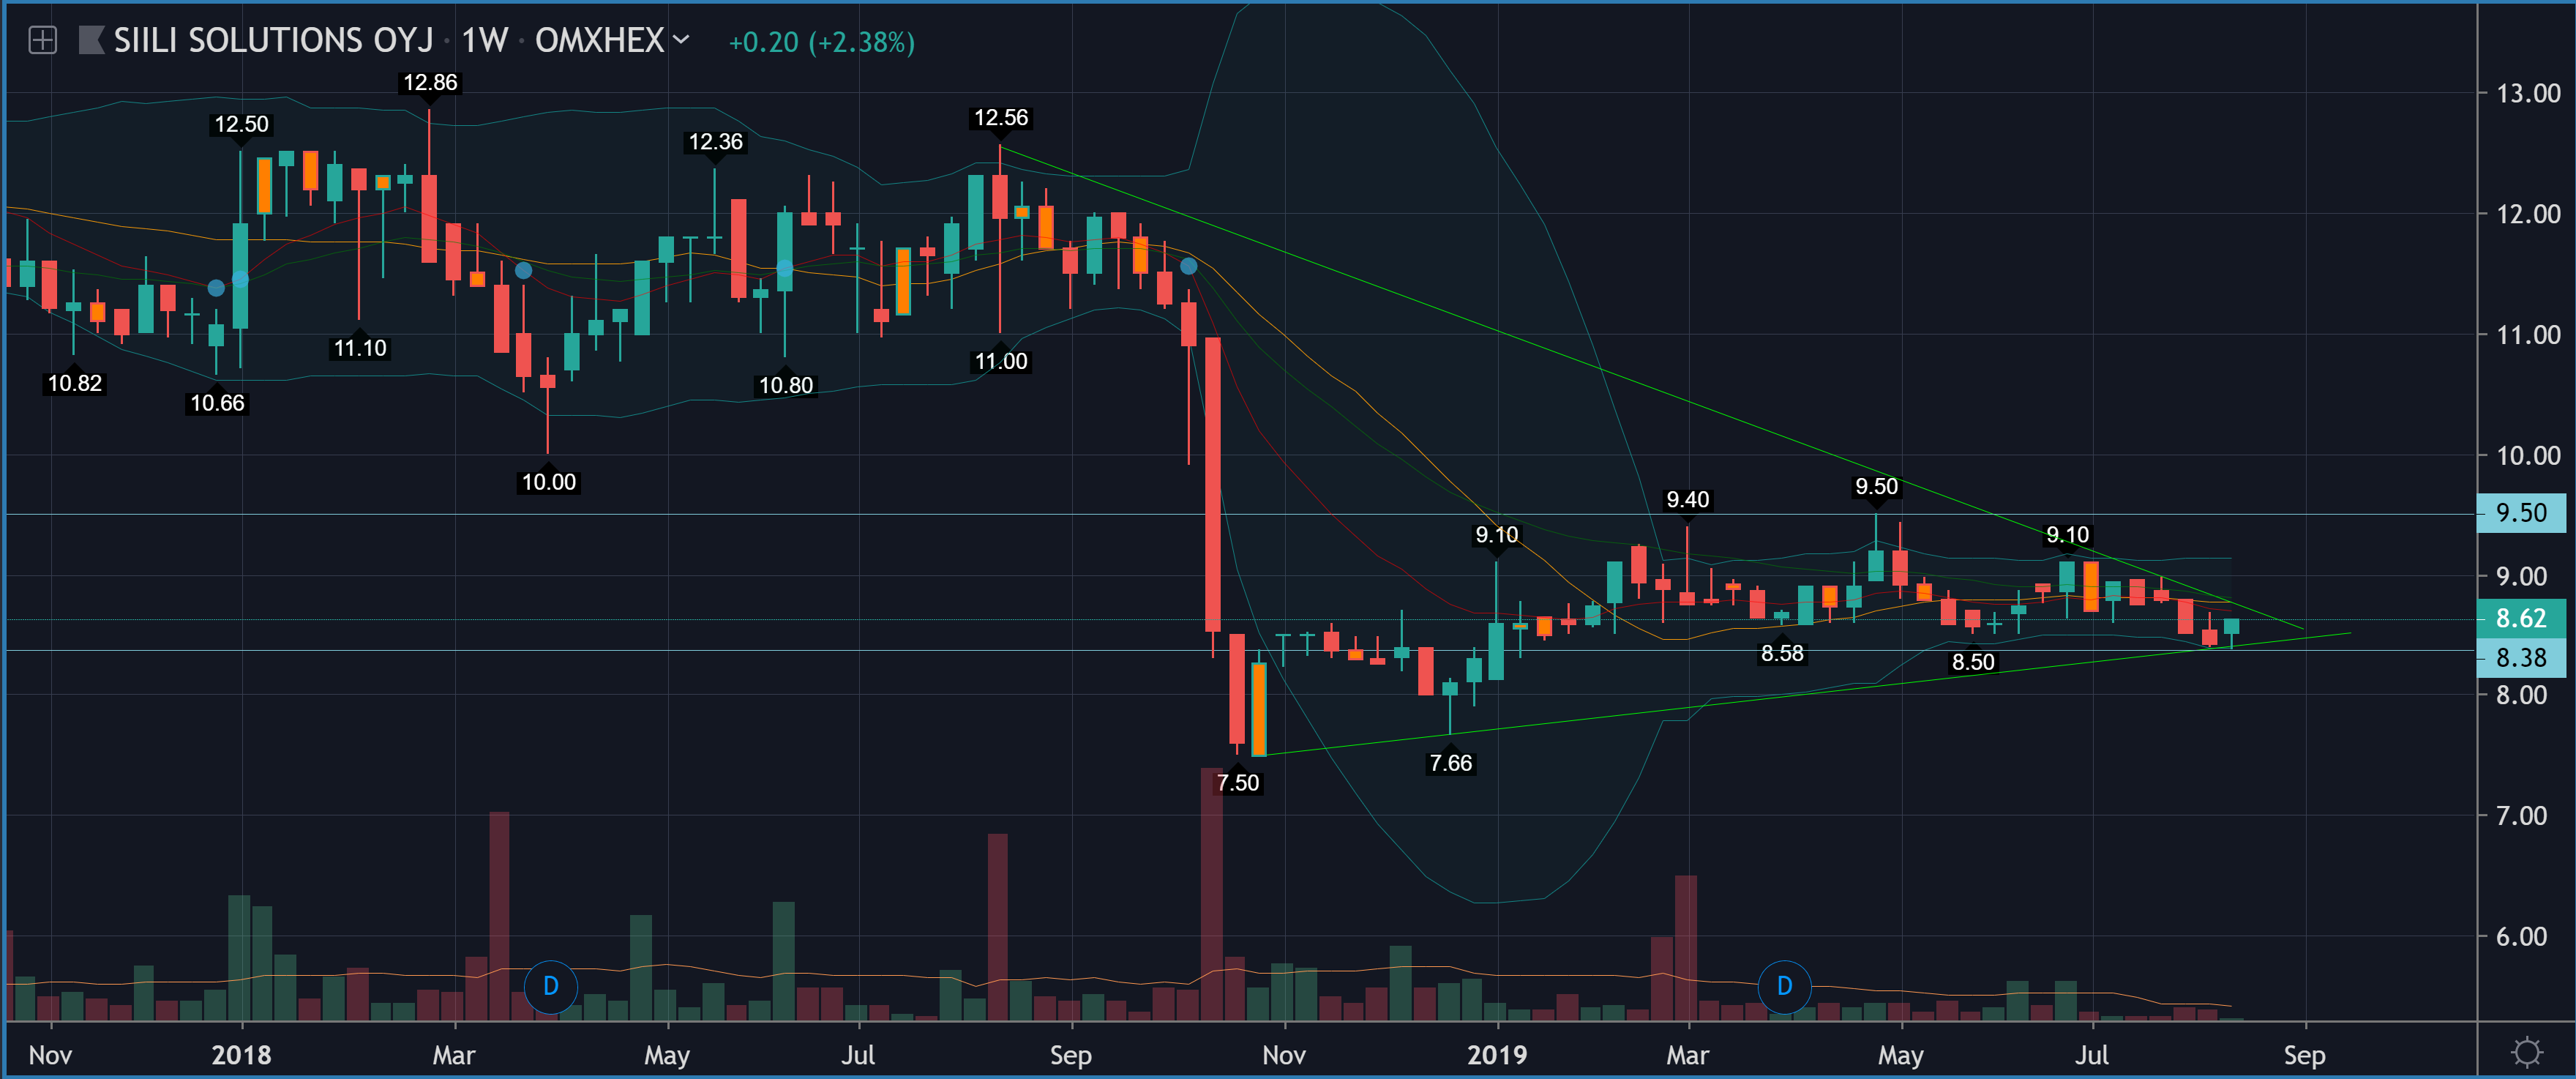
TA doesn’t paint a flattering picture of the company. The tightening wedge indicates that a break in one direction or another will happen soon, and the odds are on the downside.
Is the company’s earning power ready for a worsening economic outlook and tightening competition in the IT market in Finland?
I’m just guessing, but don’t IT consulting companies primarily sell human resources, and don’t they have many products? So, no scalability and questionable continuity? To put it bluntly, they could be called glorified staffing agencies, invested in by people who want to invest in “technology companies” but fear high valuation multiples, or am I completely off track? How can Siili create a competitive advantage for itself, let alone a moat?
Yes, these are expert businesses, but that doesn’t mean that owner value couldn’t be created in the industry with significant leverage. Just look at how Siili has performed since its listing. This has been an excellent sector to own for the past 5 years, though the market is now becoming more challenging.
Compared to product companies, consultants generally have a more stable business model, more stable profitability, good cash flow and dividends, and no product development risk. Established players also typically have their hands quite deep in clients’ pockets, providing good business continuity. Multiples are justifiably lower than in product companies. They ride the same technology trend as product companies, but with a different business model. Therefore, I believe the IT services sector is a perfectly valid way to invest in the technology sector in general, especially if you don’t want to take a stance as an investor on which individual technology will be a winner in the future.
It’s difficult to achieve a very sustainable competitive advantage in this sector because expertise decays so quickly with the rapid development of technology. In my opinion, one important source of competitive advantage, given that we are in a people business, is innovations related to organizational models and culture. Good examples from this sector over the last 10 years include Gofore, Futurice, and Reaktor.
The stock has once again fallen to attractive prices. @Mikael_Rautanen, have there been any negative news about the company lately? OP has at least been a big client, do you know how the new arrangements there affect Siili? What about Nokia, is it still a significant client for Siili?
{“content”:“I haven’t heard anything one way or another. The CMD (Capital Markets Day) is coming up in a few weeks (broadcast on InderesTV), where we’ll hear an update. OP has, to my understanding, been the largest client (if I recall correctly, it was >15% at its peak, but presumably less today), but Siili has, as I understand it, primarily provided services to areas where OP is investing rather than cutting. Of course, cuts will indirectly affect all subcontractors. Nokia is, to my understanding, not significant (I’m not sure if they are a client at all anymore); I recall that services were once provided to HERE in the automotive sector.”,“target_locale”:“en”}
I thought I saw in my news feed that OP would generally reduce the use of external services. Of course, one can’t know what all that includes, but it could partially affect everyone.
I received a good observation from one user about Siili’s original investment, which was not disclosed in the release but was revealed in the H1 report to be €150k. So even if it’s 10x in this round, it won’t shake the market value much yet, but it’s certainly positive! And the sum raised corresponds to a typical First North IPO, so the right things have been done there
After watching the CMD, I’m a bit concerned about how the management will keep a large and somewhat fragmented entity in check. When new business ideas and potential acquisitions are added alongside current operations, management processes must function well and the strategy must be clear at all levels of the organization. It’s quite a demanding balancing act on a knife’s edge, as creativity must be allowed space, yet a heterogeneous entity must simultaneously be kept efficient and manageable.
If Siili starts to branch out too much, the analyst will have to send the CEO pruning shears for Christmas next year.
Very good point and a relevant concern. Also for the analyst. Otherwise, this seems to be moving in a good direction. Of course, so far the portfolio companies (VALA, Auto, +Robocorp) have done well.
Siili’s valuation multiples look quite low if the forecasts materialize. 2020 P/E 11, 2021 9.6, 2022 8.3. ROE > 20%. Does anyone have thoughts on the company’s current situation? Hasn’t Siili been doing better for a couple of quarters now?
Really affordable valuation. Now buried in poor visibility. Will likely correct itself once last year’s numbers and outlook are released. Too cheap compared to the sector, of course!
The valuation is undeniably low. In terms of quality, I’m concerned about the company’s position towards the customer and thus the continuity of the business – my fear is that the company will become a resource provider from whom it’s easy to reduce purchases when times get tough. Another unproven thing is that the changed organization works, the new CEO is the right person to lead it, and (as mentioned earlier in the thread) the strategic focus doesn’t get lost. Not that I have any particular reason to doubt these, but such changes always cause a certain state of flux in an organization. If progress is made on these issues, I think there’s clear upside potential here.
I myself jumped back in from last autumn’s price dip and added recently. However, I still want more evidence of a successful turnaround before I’m willing to invest more heavily. The financial statement will be interesting reading.
PS. If you look purely at valuation multiples, it’s worth noting that VALA Group is fully consolidated into the results even though minority shareholders have a 40% stake in it, meaning the E-component of the P/E ratio also includes the minority. This doesn’t have a huge impact, but something nonetheless.

 The recording will be available after the live event.