Scanfil - Contract Manufacturer for the Portfolio

Here are Viljakainen’s comments on the Scanfil fire, although more detailed information is still not available.

The factory affected by the fire belongs to the Italian MB, which Scanfil has agreed to acquire. The acquisition is expected to be confirmed during Q4. The potential effects of the fire on the acquisition or MB’s production capacity are difficult to assess given the limited current information.

3 Likes

Here are also Antti’s pre-comments, as Scanfil publishes its Q3 report on Friday :slight_smile:

According to our assessment, Scanfil has progressed in Q3 with the ramp-up of projects won last year, in addition to which the SRX acquisition has supported the figures inorganically in Q3. Therefore, we expect Scanfil’s operating profit to have finally turned to growth in Q3. However, we have marginally lowered our forecasts, as Scanfil did not complete the ADCO acquisition according to the original schedule during Q3 (however, we expect the acquisition to be completed in Q4). We estimate Scanfil will reiterate its guidance, although there may be slight downward pressure on the upper end of the relatively wide ranges, as the macroeconomic picture has remained sluggish in Europe.

4 Likes

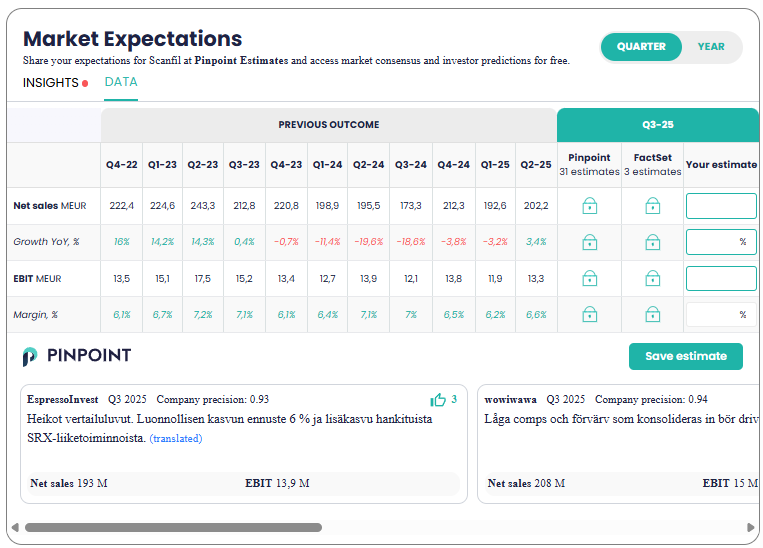
Q3 report coming up – share your expectations!

31 investors have already submitted their estimates ahead of the report, and like @Antti_Viljakainen, they expect growth and improved EBIT compared to last year.

Submit your own estimate for Net Sales and EBIT to compare your view with others here!

4 Likes

:rocket: Scanfil Q3 2025: Return to organic growth!

  • Revenue grew by 10.4% to EUR 191.3 million and EBITA grew to EUR 14.1 million :chart_increasing:

  • Organic revenue growth was 7.8%

  • Strong growth in Americas (+30.6%) and APAC (+26.0%)

  • Strategic acquisitions accelerate growth and geographical diversification in the aerospace and defense industries: US-based ADCO Circuits in June and Italian MB Elettronica in July. Both transactions are expected to be completed in the last quarter of the year.

  • Medtech & Life Science grew by 16.1% and Energy & Cleantech by 26.1%

  • Sustainability milestone: EcoVadis Gold :seedling:

  • Stable financial position :dollar_banknote:: net debt / EBITDA was 0.14 and equity ratio 55%

  • New customer projects: worth EUR 72.3 million in Q3

Scanfil estimates 2025 revenue to be EUR 780–920 million and EBITA to be EUR 55–68 million.

Full report and CEO Christophe Sut’s review: https://www.scanfil.com/fi/sijoittajat/raportointi-ja-esitykset

24 Likes

Growth in America

Revenue grew especially in America despite exchange rate effects.

“Adjusted for the impact of exchange rate changes, revenue grew by 40.2 percent in America and 33.0 percent in APAC. Growth of 11.7 percent in Northern Europe was due to an Energy & Cleantech customer,” commented CEO Christophe Sut.

According to Sut, Ebita growth was supported by increased volumes and the company’s efficiency measures.

Scanfil divides its customers into three groups: Industrial, Energy & Cleantech (energy, circular economy, and electrification), and Medtech & Life Science (medical technology).

Of these, Energy & Cleantech and Medtech & Life Science grew.

In Energy & Cleantech, revenue grew by 26.1 percent, which, according to Sut, was due to strongly progressing customer project wins.

“We remain very confident about the long-term development of this customer group. New customer projects were won during the quarter totaling 18.4 million euros.”

Medtech’s growth was 16 percent.

“We signed an agreement with a significant customer, which supports the long-term development of Medtech & Life Science,” Sut commented.

“New customer projects were won during the quarter totaling 15.3 million euros.”

The revenue of the Industrial customer group decreased by 2.3 percent compared to the previous year’s reference period. According to Sut, volumes are expected to stabilize in the future.

7 Likes

Antti has prepared a new company report following Q3. :slight_smile:

The overall picture of Scanfil’s Q3 report, published on Friday, was in our opinion quite neutral, and we did not make significant changes to our forecasts after the report. We thus reiterate our Reduce recommendation for Scanfil and our target price of 10.50 euros. The company’s outlook is positive in both the short and longer term, but in our opinion, the stock has already priced in a suitable amount of expected earnings growth (2026e: adj. EV/EBITA 11x. Thus, the 12-month return expectation does not rise to a sufficiently attractive level from the current valuation with a one-year horizon.

Quoted from the report:

We expect Scanfil’s revenue to grow by just over 6% to EUR 830 million this year and adjusted EBITA by 8% to EUR 59.4 million. Our forecasts are thus slightly below the mid-points of the guidance ranges. We forecast Scanfil’s adjusted EPS to grow at a pace of approximately 15% by 2028, driven by acquisitions, a gradually recovering economic situation, and organic growth enabled by project wins. The main risks for our forecasts relate to external demand factors such as the global economy. Internally, we believe the company is in quite good shape (including customer satisfaction rising to a record high level in a survey published in connection with the Q3 report), although the integration of two almost simultaneous acquisitions, in our opinion, slightly increases the risk level related to the company’s own operations in the coming quarters.

3 Likes
4 Likes

Isa and Antti discussed Scanfil. :slight_smile:

The overall picture of Scanfil’s Q3 report was fairly neutral. The outlook is positive in both the short and longer term, but the stock has adequately priced in the expected earnings growth. Head of Research Antti Viljakainen summarizes.

Topics:

00:00 Intro 00:12 Q3 revenue growth 01:15 Weaker cash flow 2:00 Balance sheet position 03:19 Project sales 04:50 Future growth drivers 06:00 Valuation & recommendation

This video can also be found on the Inderes Nordic channel:
https://www.youtube.com/@inderesnordic

1 Like

Let’s put this fresh Scanfil release here. :backhand_index_pointing_down:

19.11.2025 12:15:11 EET | Scanfil Oyj | Inside Information

Scanfil Oyj Stock Exchange Release 19.11.2025 at 12:15 p.m.

Inside Information: Scanfil’s acquisition of MB Elettronica expected to be completed in January

The completion of the acquisition of MB Elettronica (“MB”) has been postponed and the transaction is expected to be completed during January 2026. The acquisition has received regulatory approvals and the remaining closing conditions are believed to be met before the closing of the transaction.

Scanfil announced in a stock exchange release on October 18 that a fire occurred at MB’s factory building in Cortona on October 17. MB’s management has informed Scanfil that operations continue without significant disruptions.

The acquisition was announced in a stock exchange release on July 13, 2025.

4 Likes

The comment is here. The finalization of the MB deal is slightly delayed, for which resolving the complication caused by the fire is probably partly the reason. From the perspective of the share’s fair value, this naturally has no significance. The same naturally applies to the ADCO deal, where the finalization phase has also been delayed from Q3 to Q4, as I understand it, due to reasons related to regulatory approvals.

Among Scanfil’s peers, Kitron made an acquisition yesterday evening and also published guidance for next year. Kitron is acquiring DeltaNordics for EUR 114 million, which corresponds to an EV/EBITDA multiple of 9.7x calculated from next year’s earnings forecast. Behind the somewhat high-looking price is likely DeltaNordics’ focus on the defense sector (approximately half of its revenue). Kitron guided for clear growth and margin improvement for next year without DeltaNordics, but Bloomberg consensus estimates are around the upper end of Kitron’s guidance ranges. Although Kitron’s valuation is among the highest in the peer group (2025e: P/E 30x), the stock has not moved anywhere this morning. Thus, at least at first glance, the content of the release seems to have been sufficient for investors (or alternatively, I have interpreted something incorrectly). For Kitron, the defense sector is genuinely a

5 Likes

The somewhat anticipated ADCO acquisition from the US has been completed. The company is very profitable and it brings significantly more defense industry business to Scanfil. Scanfil on saanut päätökseen yhdysvaltalaisen ADCO Circuitsin yritysoston - Scanfil

14 Likes

Here are Antti’s comments regarding the announcement/news above. :slight_smile:

Scanfil announced on Tuesday evening that it had completed the acquisition of US electronics contract manufacturer ADCO Circuits. The completion of the deal was expected and has no material impact on our near-term forecasts, as we had anticipated the arrangement to be completed during Q4. In our opinion, ADCO fits well with Scanfil strategically, and the valuation of the arrangement is also moderate, so the value creation potential of this relatively small deal appears promising. Our original comment on the acquisition can be read here.

5 Likes

Antti has prepared a new company report on Scanfil. :slight_smile:
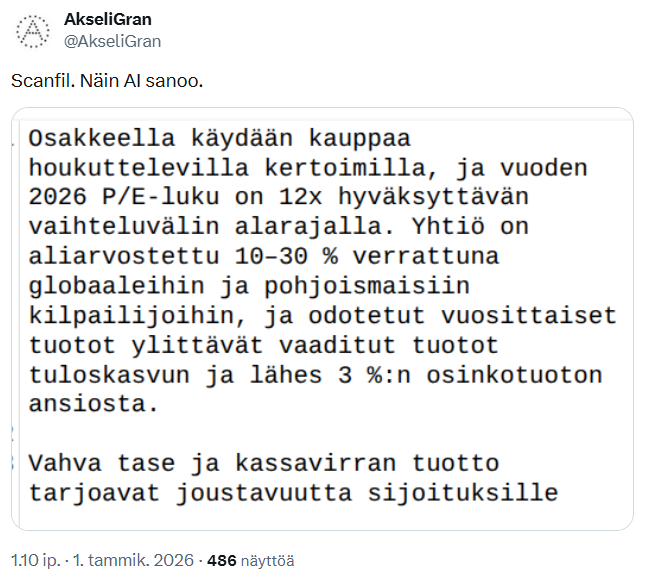
We reiterate our target price of EUR 10.50 for Scanfil and raise our recommendation for the company to Add (previously Reduce). We have not made material changes to our Scanfil forecasts, although the delay in acquisitions slightly lowered our Q4 forecasts. However, with the valuation (2026e: P/E 12x) having fallen due to the recent slight decline in the share price, we believe the expected return has improved and risen slightly above the required rate of return. Also, in the longer term, we believe Scanfil offers an attractive profitable growth investment story.

10 Likes

Scanfil and Valmet have agreed to expand their cooperation into new geographical areas and products. The new agreements support Valmet’s geographical presence and growth through several products and product families.

Full press release: Scanfil ja Valmet lujittavat yhteistyötään elektroniikan sopimusvalmistuksessa - Scanfil

17 Likes

https://x.com/AkseliGran/status/2006684488026210468?s=20

2 Likes
7 Likes

Here are Antti’s comments on how Scanfil has finalized the MB acquisition. :slight_smile:

Scanfil announced on Thursday evening that it has completed the acquisition of the Italian electronics contract manufacturer MB Elettronica. The completion of the deal in January was expected, and the timing has no impact on our forecasts. However, the acquisition target delivered a very strong result in 2025, exceeding our estimates, which naturally already partly triggers the earn-out payment. Overall, the risks concerning our forecasts for Scanfil for the coming years are at least decreasing thanks to MB’s strong 2025 figures. Scanfil is organizing a briefing regarding the acquisition today at 2:00 p.m. The briefing can be followed here.

7 Likes

Following the evaluation of the acquisitions of the Italian MB Elettronica and the US-based ADCO Circuits, Scanfil has defined its outlook for 2026.

Scanfil estimates its 2026 revenue to be EUR 940–1,060 million and its comparable EBITA to be EUR 64–78 million.

Scanfil will publish its financial statements for January–December on Friday, 20 February 2026, at approximately 8:00 a.m.

14 Likes

Scanfil invests in its factory in Suzhou, China: https://www.scanfil.com/fi/uutishuone/press_release/scanfil-investoi-kiinan-tehtaaseensa-suzhoussa

17 Likes

Here are Antti’s comments regarding Scanfil’s recent announcements :slight_smile:

Scanfil announced its guidance for 2026 on Thursday. The midpoints of the wide guidance ranges were well in line with our current forecasts. Initially, we do not believe the guidance will cause significant pressure for changes to our or the consensus forecasts for Scanfil’s current year. However, the guidance, which hit expectations, slightly reduces the risks related to the organic and inorganic growth and earnings growth we have forecasted for this year.

Scanfil announced on Thursday that it is investing EUR 9 million in the expansion of its factory located in Suzhou, China. With the investment, the factory’s floor area will more than double. In Scanfil’s strategy, the Suzhou factory focuses especially on the Chinese local market, where, according to our understanding, the company has performed well in recent years. It supports long-term organic growth, but it does not cause immediate changes to our forecasts regarding investments or growth and earnings forecasts.

4 Likes