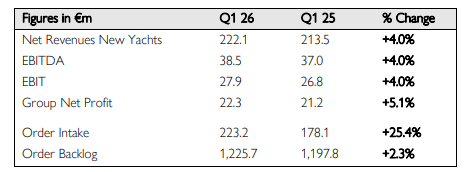
Investing where the market is booming! So new appointments in the US, yada yada..
At this stage, these investments are not yet reflected in the numbers, but hopefully, sales in the US will continue to accelerate at a rapid pace. 
Investing where the market is booming! So new appointments in the US, yada yada..
At this stage, these investments are not yet reflected in the numbers, but hopefully, sales in the US will continue to accelerate at a rapid pace.
Damn, free time is really at a premium lately; I barely have time to quickly check company results. Hopefully, I’ll have some time over the weekend to dive deeper!
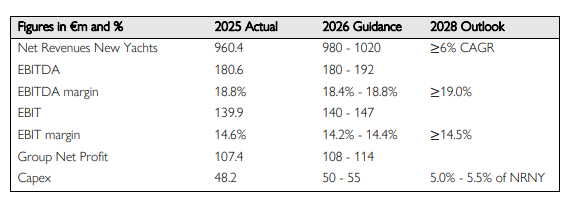
Sanlorenzo is guiding for moderate growth this year with margins largely in line with the previous year.
It certainly still gives the impression of a luxury brand! It requires a bit of mulling over for me: if growth is slow and margins aren’t improving, is it a value trap or will SL eventually get better multiples? Of course, a lot also depends on how the 2028 targets are met. If growth were to be brisker than that 6% CAGR and the EBITDA margin rose above 20%, the situation could be different. Food for thought.
A couple of picks from CEO Massimo Perotti:
We enter our Tomorrow’s Timeless Plan from a position of strength: in 2025 we delivered on all key guidance metrics, and Q1 2026 confirms continued momentum, with order intake up 25% year-on-year, marking the seventh consecutive quarter of growth. Our Order Backlog, 90% sold to end clients, and Net Backlog above €1 billion provide clear revenue visibility over the coming years.
This part puts a smile on my face. The numbers alone were nice to read, but this kind of hinting is music to my ears!
Looking ahead, we see additional upside potential not yet embedded in our guidance, including a gradually stabilising geopolitical backdrop, the reopening of key markets and the expansion of high-margin refit and services activities
Good companies are the kind where you can check the results even a month later.
My gut feeling is that this is a “low-hurry” company, although my level of familiarity (and thus the small size of my holding) is quite superficial.
Revenue was 960 MEUR in 2025 and the EBIT margin was already 14.6%. The >2028 targets are indeed a 6% CAGR and an EBIT margin >14.5%. So, from the company’s perspective, margins are pretty much capped out.
From an investor’s point of view, the “most interesting” phase of the company’s development is in a way over—meaning the past years when margins improved in addition to sales growth.
On the other hand, the targets tell me that my fear of margins “normalizing” downwards might also be exaggerated.
Let’s assume revenue grows by 6% by the end of 2028. It would then be 1,143 MEUR. Let’s be generous and say the EBIT margin is 15%. EBIT would thus be 171 MEUR. Net debt-free, let’s ignore interest expenses. Italian taxes were around 24%, I believe. So net profit 130 MEUR. Shares ~35.5 million. EPS 3.7 EUR.
If the P/E remained at 11x, the share price would be ~40 EUR at the start of 2029, with a euro or two in dividends paid a couple of times. Total return an epic 6% per year… 
But one could simply argue that a business with 20% ROIC, even with slow growth (~3%), deserves multiples of 12-14. For example, trading at 13x at the beginning of 2029, the annual return would be a whopping… 13%! Note: 3% growth would be quite low; you’d think a company like this could grow faster well into the future given current trends.
And as mentioned, the company itself seems to signal that the guidance is slightly conservative. But they don’t have a crystal ball, of course.
The CEO says the company is looking for an acquisition target in the United States  :