Paysafe (PSFE) - Worldwide Online Payments

Paysafe and Foley Trasimene

I thought that Paysafe’s listing in Q1 2021 via the $BFT SPAC might interest other forum members. At least, based on the O&M thread, there are already owners here. The founder of the SPAC is William P. Foley, who currently serves as Chairman of Fidelity’s Board of Directors and owner of the Vegas Golden Knights (NHL). So, there’s a lot of reputation from the financial world and big money behind this.

What is a SPAC?

SPAC, or Special Purpose Acquisition Company, explained in more detail: Special-purpose acquisition company - Wikipedia. In short, it is a company into which a group of institutions has invested a large sum of money, and this company is looking for an acquisition target in the market to merge with. In other words, an inverse IPO. This is one of the biggest deals seen on the market to date.

Services and the Growth of Online Betting and Gaming

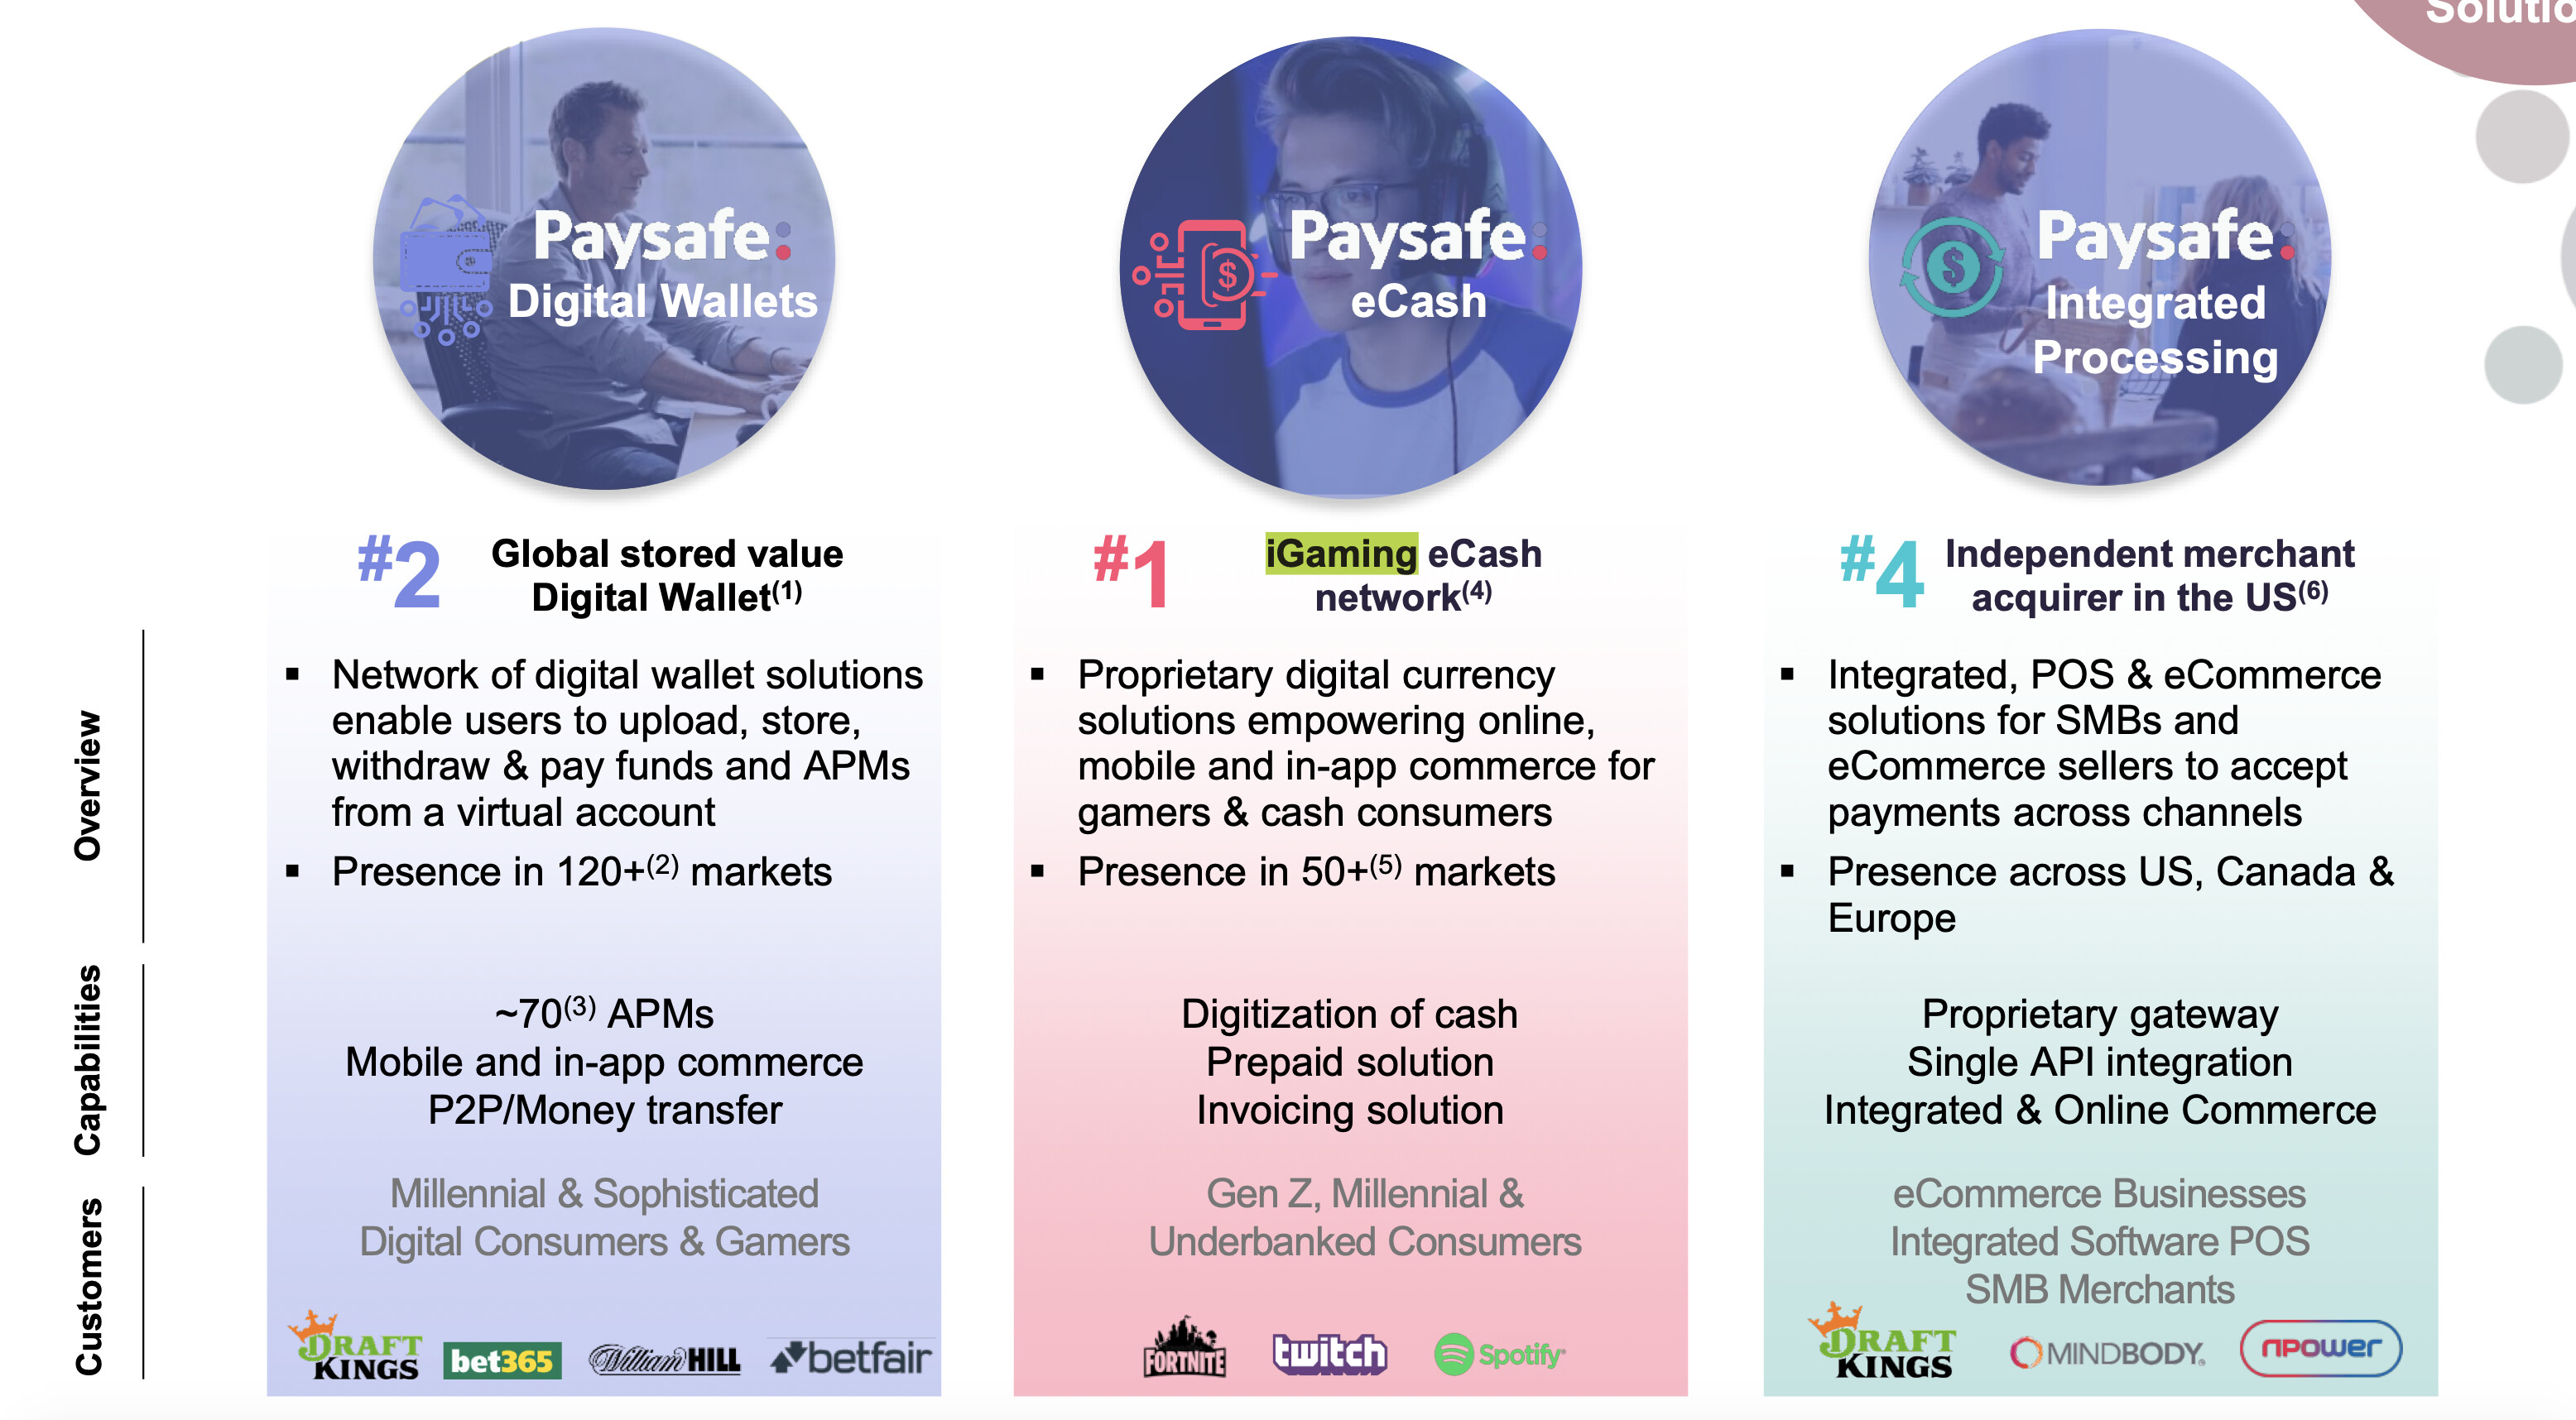
In Europe, Paysafe is best known for its Skrill and Neteller services, which are popular money transfer methods between online gaming and betting sites. What makes the listing particularly interesting, in my opinion, is the ongoing shift in the US towards online sports betting and gambling. States need more tax revenue after COVID-19, and betting is seen by many as an opportunity. Most recently, NY Governor Andrew Cuomo has floated this possibility https://www.legalsportsreport.com/46604/ny-sports-betting-cuomo-statement/

The online betting market alone is projected to grow at a CAGR of 14.78% from 2020-2025. North America Online Gambling Market to 2025: Market is Projected to Register a CAGR of 14.78% and on top of that, the entire online gaming market, digital wallets, and payment services (partners include Twitch, Fortnite).

Evolution Gaming has attracted many here precisely because of the explosive growth of online casinos. Paysafe’s backend systems also act as accelerators in this transition.

More data on the growth of online gaming and gambling: "888 Holdings expects a 45% rise in full-year revenue for 2020, while the operator has also secured market access agreements to roll out sports betting in a trio of new US states.** https://igamingbusiness.com/888-forecasts-strong-fy-growth-seals-us-market-access-deals/
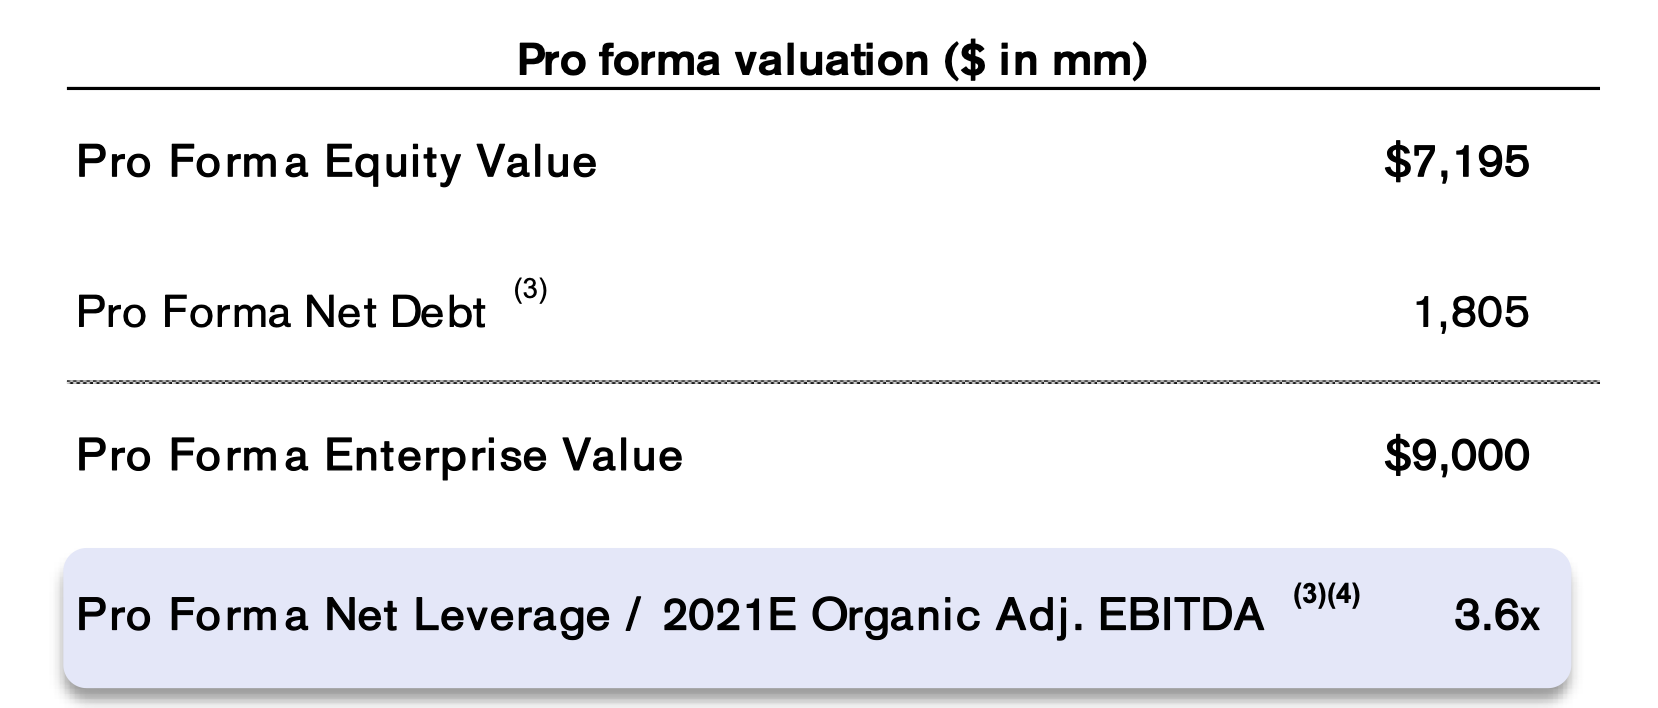
Compared to PayPal and Square, the valuation is still reasonable at this point:
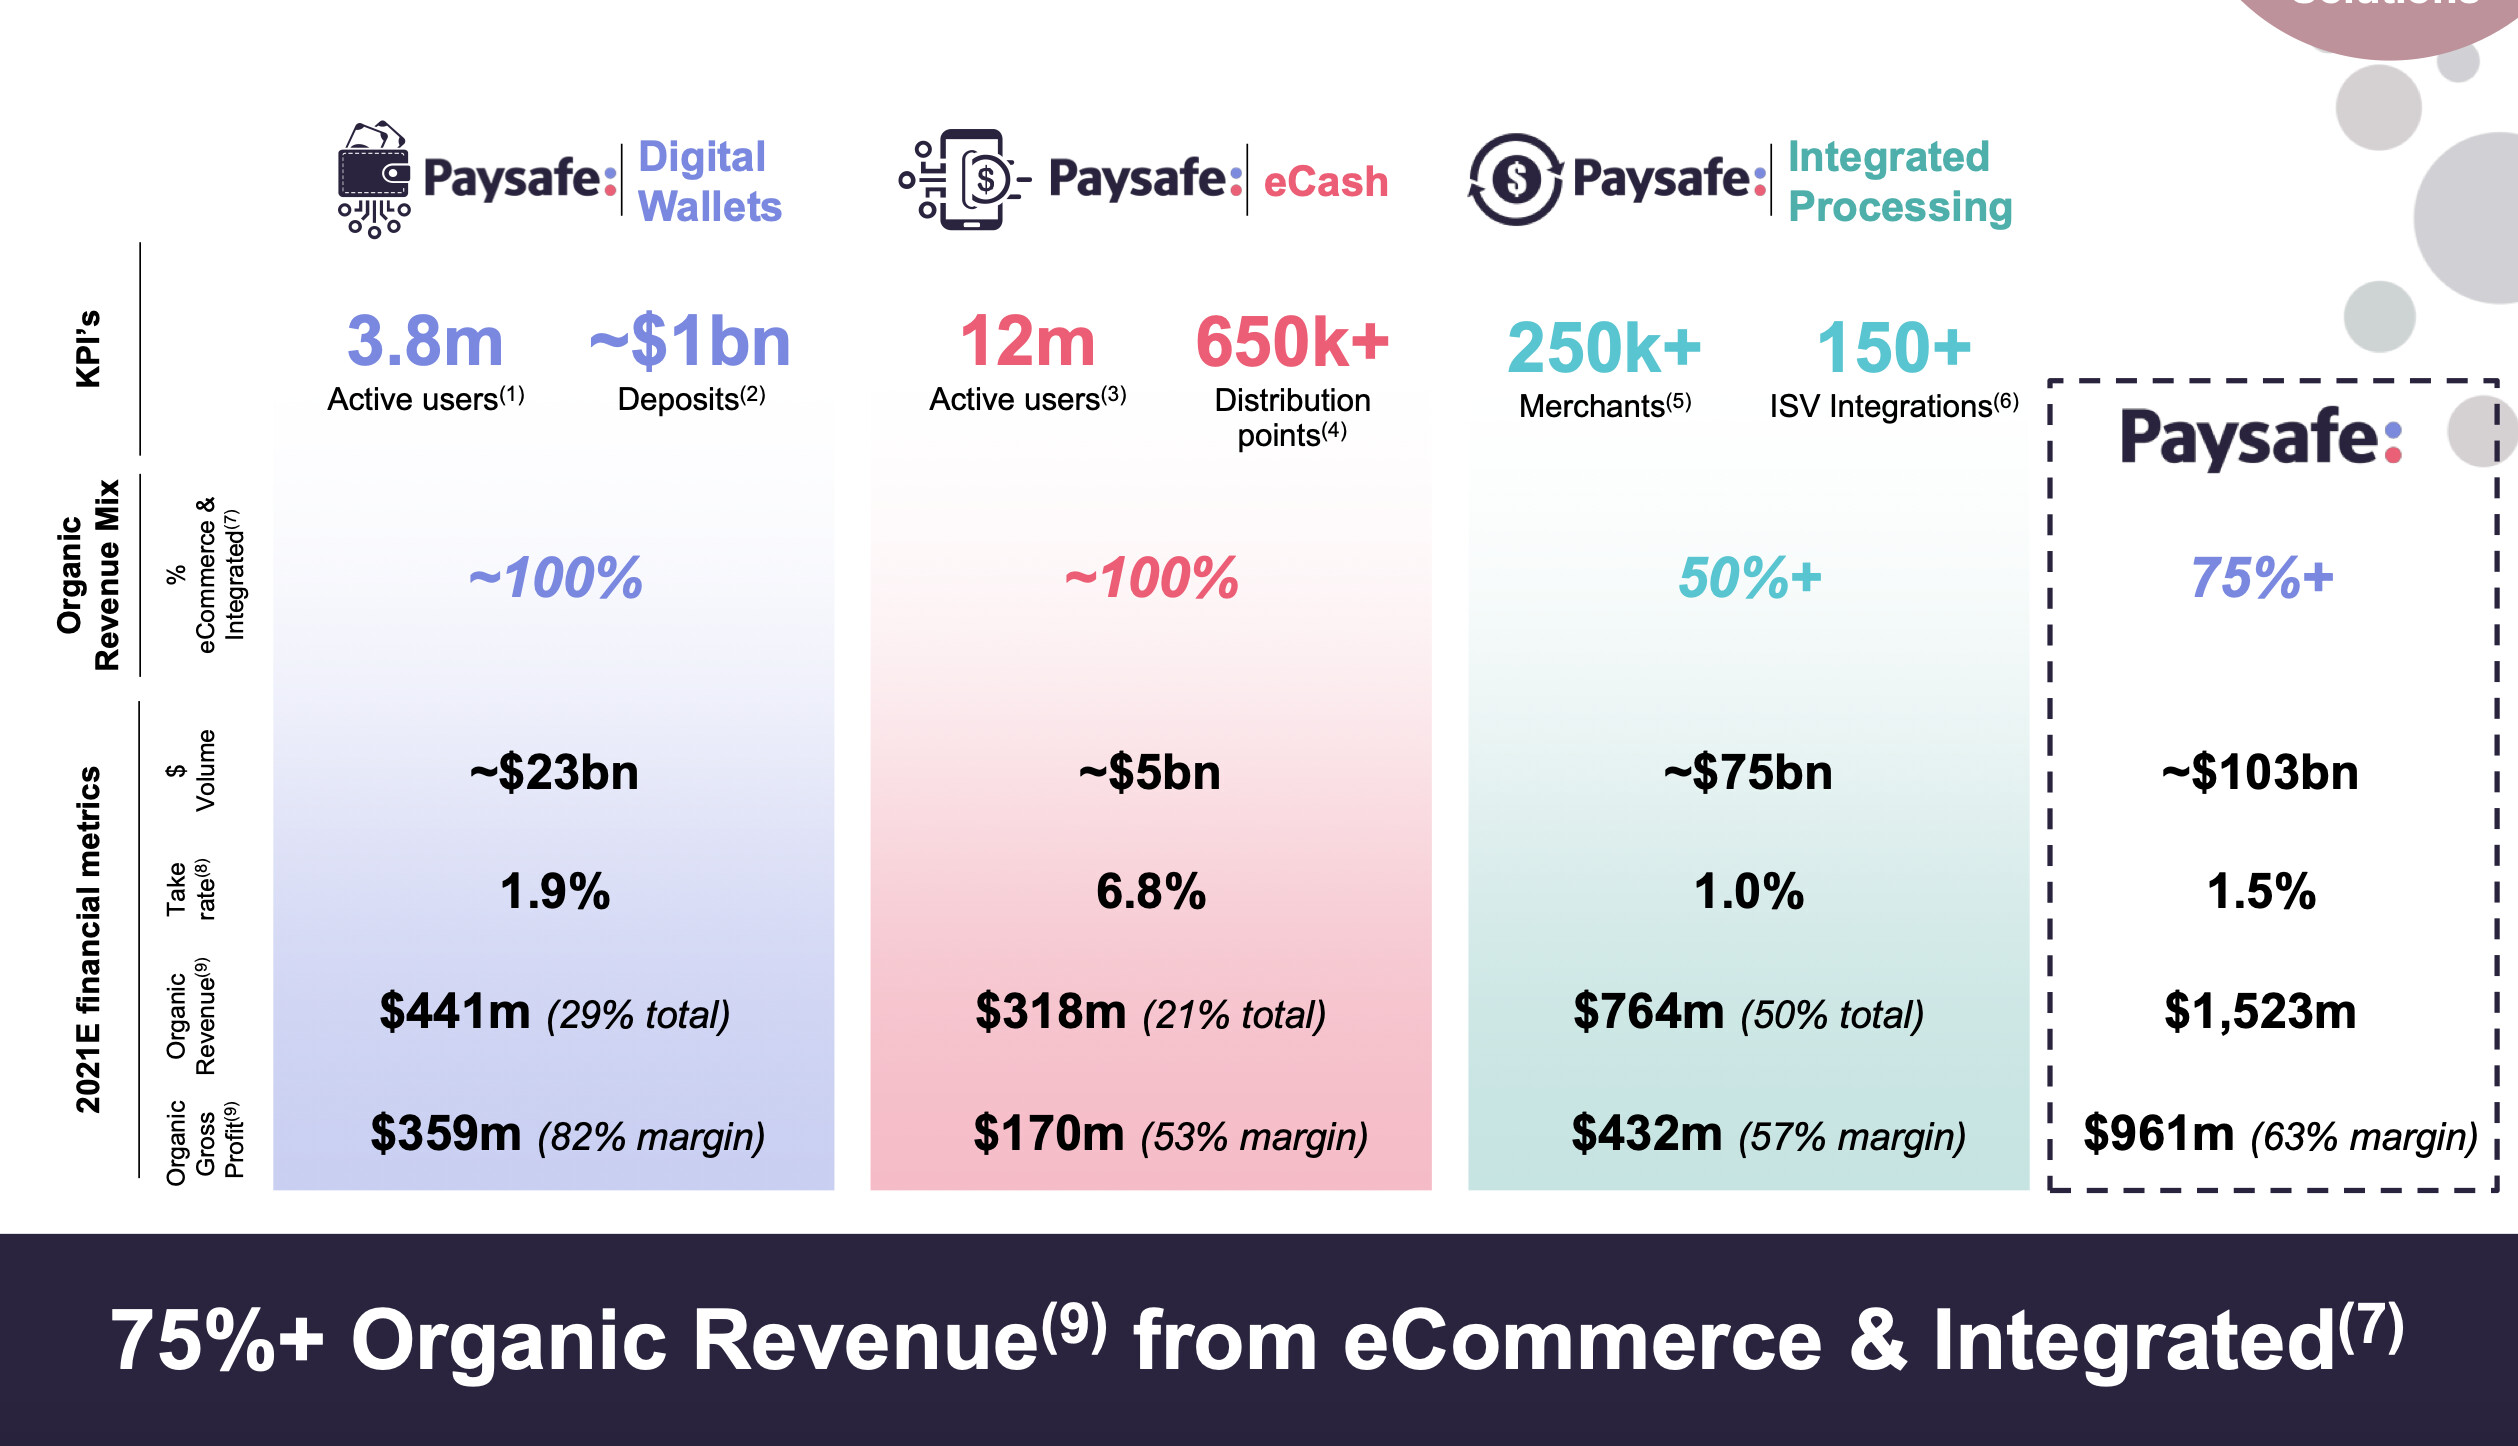
If the 2021 forecasts materialize, the case is, in my opinion, extremely interesting:
All images above are taken from the Paysafe and Foley Trasimene investor presentation, which is worth reading through:
https://s25.q4cdn.com/579018173/files/doc_presentations/2020/Foley-Trasimene-Acquisition-Corp.-II-and-Paysafe-investor-presentation.pdf

40 Likes

The pace is picking up in the US all the time. News from the last week:

13 Likes

They’re heavily threatening the value to be around $35 in March. We’ll see then :smiley: I put a pretty good package in my portfolio though.
6 Likes

If all these targets hit (which I’ve seen in my own notes), there’d be big income coming in :smiley: There’s a lot of potential for growth here.

1 Like

I’m talking to Bill Foley here, apparently a big name in the US. Good start to the thread.

1 Like

Probably a stupid question, but I’ll ask anyway.
Could someone clarify for me what the difference is between these?

Bft yes wpf some shares, in =-ending ones, in addition to one share, a warrant (warre) is included, or parts of one warrant.

The matter is as the Emperor said. There was something related to this in the SPAC thread a while ago, read a few messages down from here:

Thanks for the reply​:slightly_smiling_face:
Do you know what’s behind this story​:down_arrow:

It’s nothing important, just basic ambulance-chasing law firm activities and attempts at frivolous lawsuits. Almost every space is targeted by these.

So, BFT’s owners will get about a 20% share of the company after the merger? At the current share price, BFT is valued at around 2.5 billion, meaning Paysafe is being priced at close to a 13 billion valuation. How much could ownership potentially be diluted as a result of warrants, has anyone looked into this?

From appendix, page 4 of the presentation:

" Represents transaction values at $10.00 per share price. Excludes dilution from 74.8 million public and private placement warrants struck at $11.50. No incremental earnout shares to be granted to selling shareholders.

  1. (1) Assumes no redemptions. Excludes 8.0 million forfeited founder shares (~22% of initial founder shares).
2 Likes

Really interesting. However, organic growth has been quite subdued in recent years, just over 10%. For such a hot sector, that’s surprising. Or is fundamental analysis the wrong focus area when it comes to SPACs :sweat_smile:?

1 Like

It’s good to note that Paysafe also exited the Asian market due to its volatility.

In Europe, the market is already quite strongly held. Games are happily running practically everywhere. In the US, this same transformation is only just happening, and that’s where they are heading now. That’s where the big growth will come from.

2 Likes

Regarding that growth, the corona year has been an exception in this growth trajectory, but I see the new US market as an angle that enables the same or even higher growth than in 2017-2019, when revenue grew from 800 million to 1.4 billion (27% CAGR).

Adjusted EBITDA margin is 30%, which they aim to raise to 35%. If you believe in this growth story, does it still look weak based on fundamentals? :cowboy_hat_face:

Foley + Fidelity + financing arrangements, as well as the sports-related network, this company has a strong captain at the helm.

Paysafe is the market leader in the iGaming sector and number 2 in digital wallets.

9 Likes

New partnership with Microsoft. All Microsoft and Xbox marketplaces will now accept Paysafe cash https://www.paysafe.com/de-en/paysafegroup/news/detail/paysafe-enables-online-cash-payments-for-microsoft-customers/

27 Likes

The cryptocurrency exchange’s new Visa debit card, which is issued by Paysafe, is now available across the UK and soon to be rolled out across Europe.

19 Likes

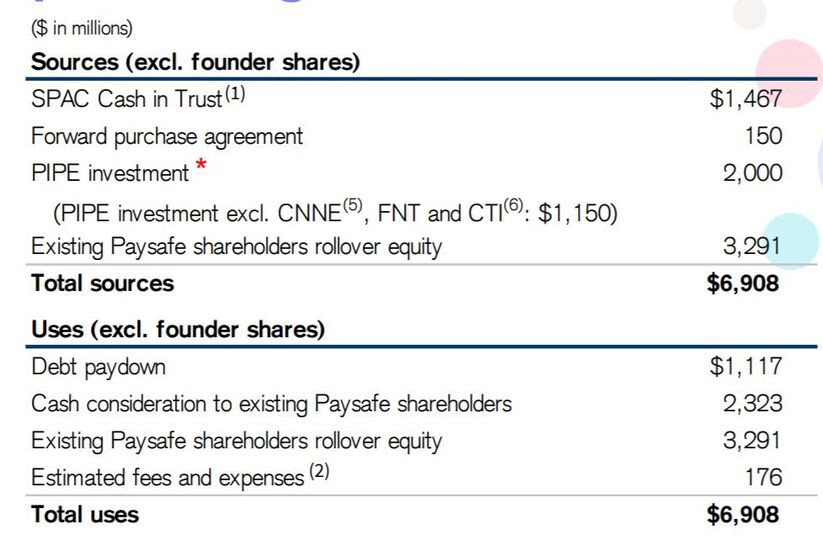
Have you considered this in the valuation and benefits of listing?

Most of it goes to the current Paysafe owners and for loan repayment. Instead of bringing in new equity and additional money into the company, now shares are being bought from owners – who previously took Paysafe off the stock exchange. The debt repayment itself is positive, freeing up capital and cash flow from that direction.

In addition, the PIPE (Private Investment in Public Equity) portion is truly significant. In connection with and after the merger, this adds more risk of a big dip in the share price. PIPE funds typically have no lock-ups and can sell as soon as the shares have been transferred. Owners and sponsors are a different matter; they usually have some form of sales restriction in place.

That being said, there’s a lot of good here, and new collaborations have been developed. I also have a small position. Because of these points, I initially almost decided not to buy and have constantly been on the verge of selling from my portfolio, but the share price has continued to climb, at least for now :sweat_smile:

16 Likes

Can you tell if the current owners are getting more than usual here? I’m more concerned about the business’s “double-digit growth” which is almost “single-digit.”

1 Like

It varies quite a bit depending on the target company, but generally, money is sought for growth rather than for current owners.

Paysafe has been on the market for a long time, so achieving significant growth is more challenging. I should probably research more to see if I want to take a stronger view or sell my shares :thinking:

Edit:

So I sold it without further delving into it. I have a new target and a couple in mind, so I need cash. Still keeping an eye on it, though.

5 Likes