Today, Bourdon’s discovery was announced. Approx. 25 million barrels of recoverable crude oil - a new field is taking shape.
Another piece of news is that OPEX, using the old calculation model, decreased from the $18.50 level to the $16/barrel level in Q1. Great, even though the new reporting method of $9.9 is really cryptic/misleading.
3 Likes
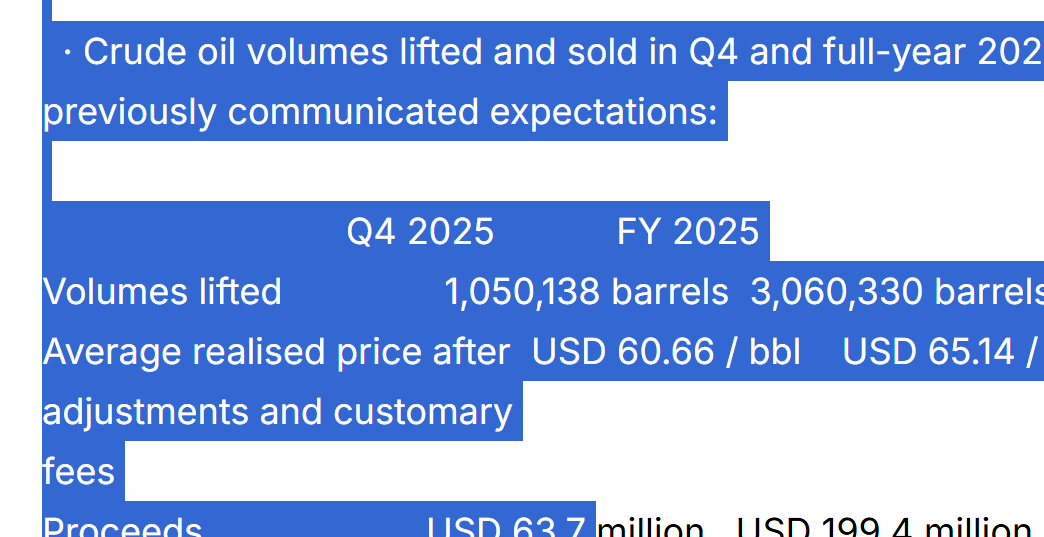
The update released today suggests that last year was quite solid. The shareholder returns and outlook (unspecified) are also encouraging.
What are your thoughts on Panoro’s ability to generate returns for shareholders in 2026? What about African oil in the current global situation? Personally, I am hopeful that this provides oil security for Europe (including PNOR) in a situation where various global blocs are securing oil with self-sufficiency in mind. Europe’s own resources (excluding Russia) seem to be insufficient, so when it comes to oil, we will have to supplement our needs from other blocs – at a premium price?
6 Likes
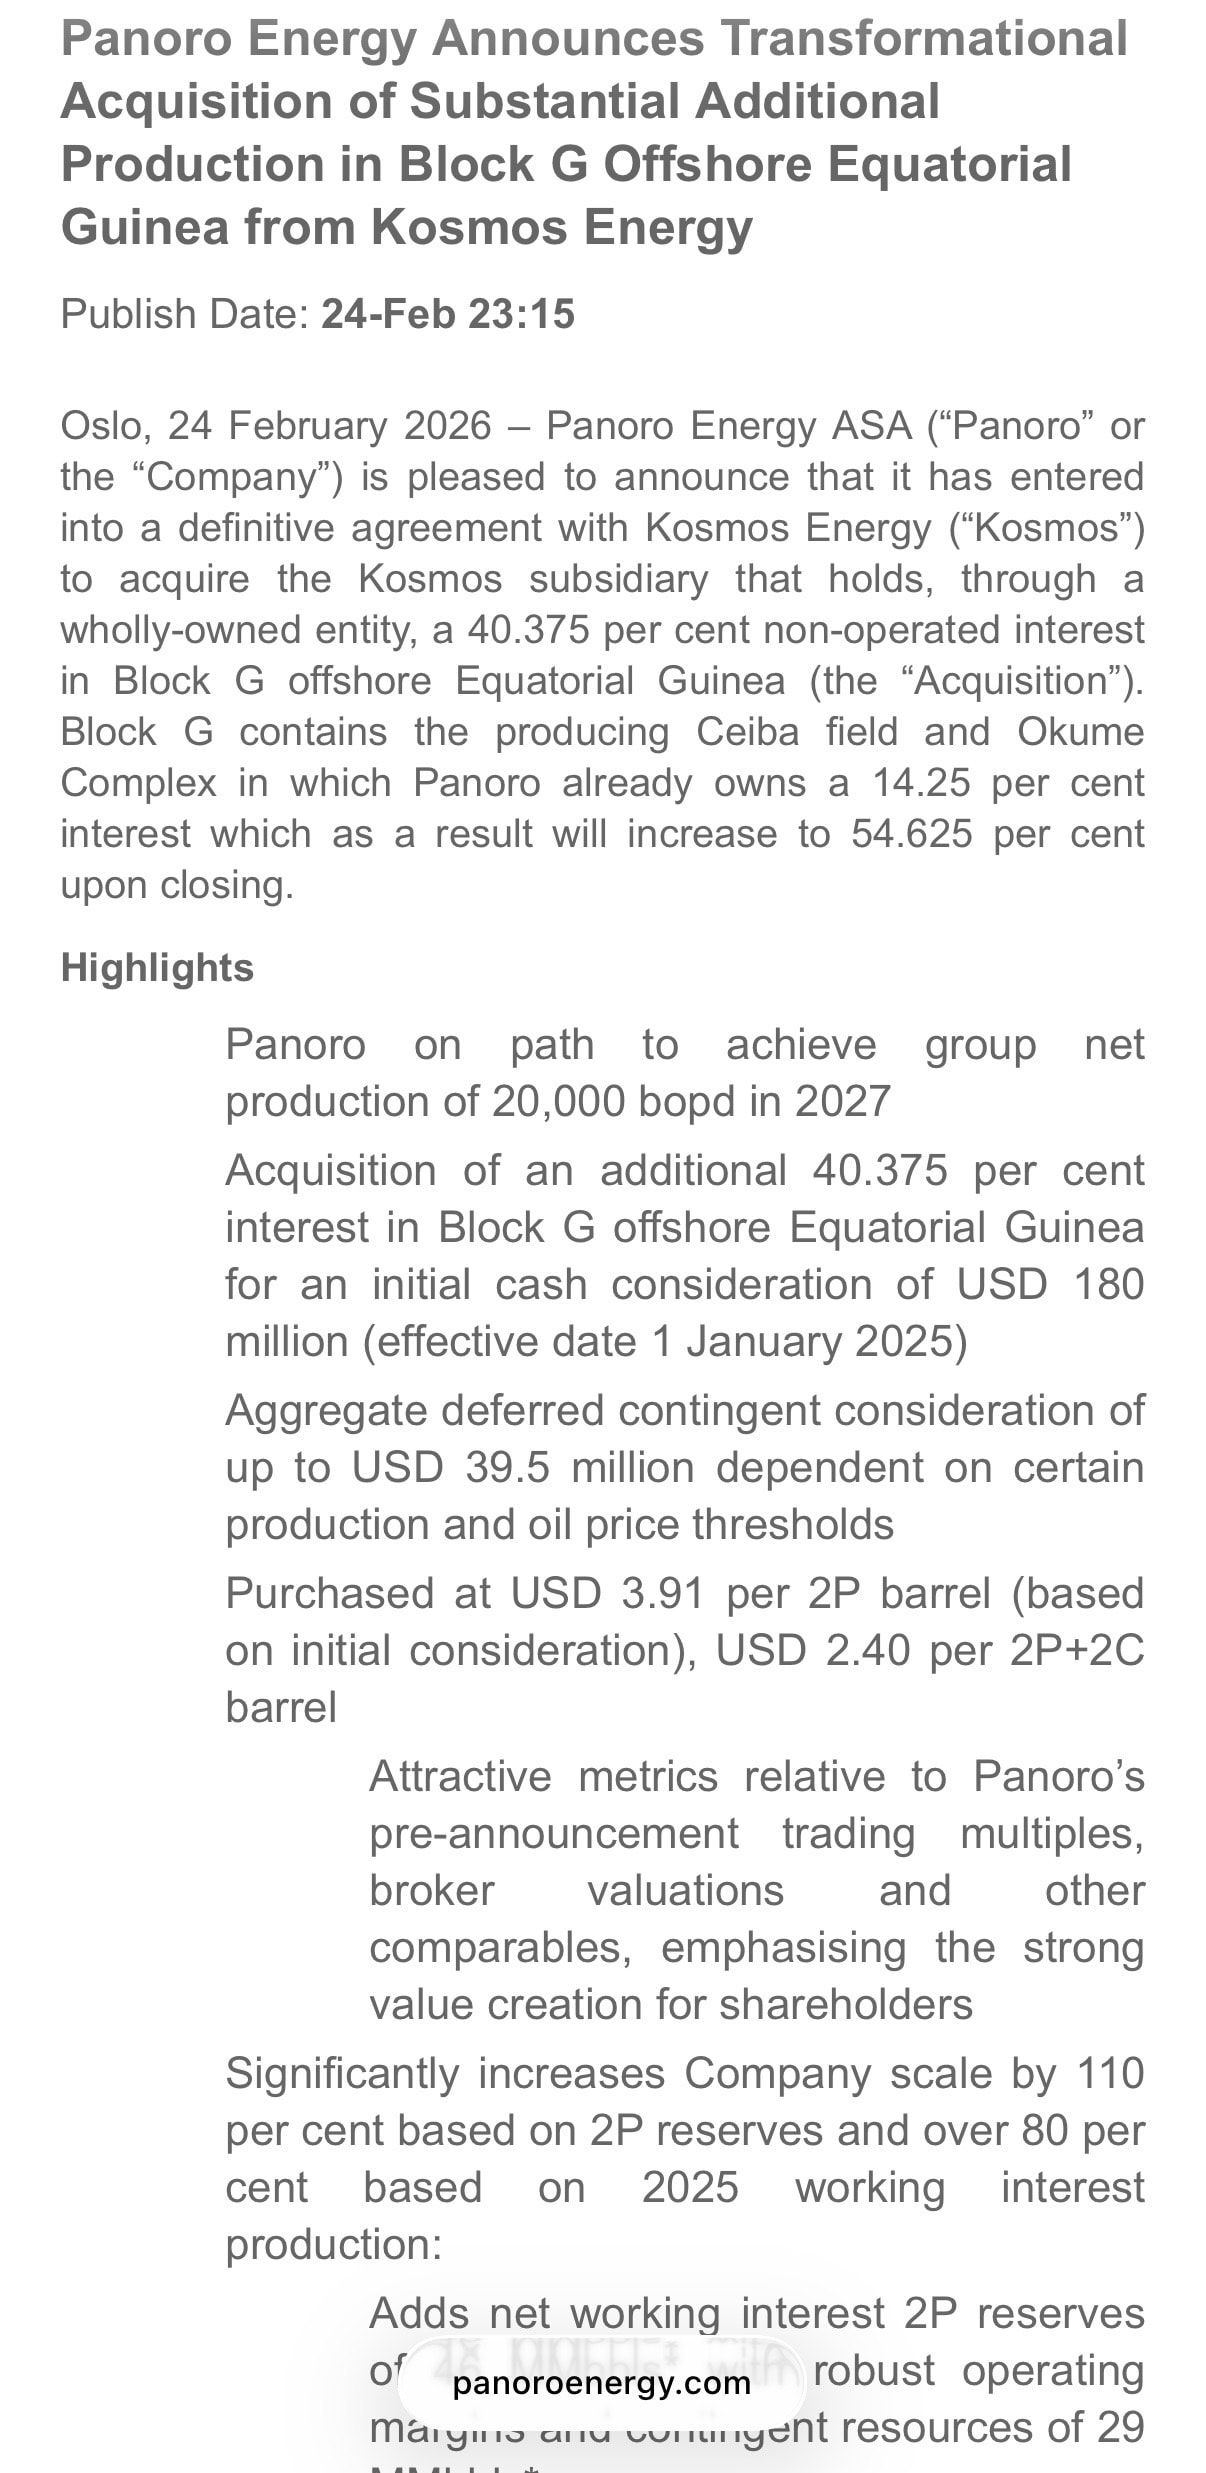
Panoro had some pretty big news about 3 weeks ago when they acquired 40.375% of Block G on top of the previous 14.25%. As I understand it, it’s quite a big leap in production. At the same time, there was a USD 49m share issue. It hasn’t sparked much discussion here 
7 Likes
Analysts have raised the target level to 37-45 NOK. Buy recommendation prevails - other peers mostly have a hold. This KOSMOS deal and the low price hedging % are the cornerstone of the position. PANORO looks very good right now - the Star of Africa - far from the Hormuz boiling pot…
5 Likes
Panoro seems to be trading at around a 500m USD market cap right now. The Brent - WTI spread currently seems to be widening and showing a supply/demand imbalance lurking outside the United States.
I didn’t feel like cranking out an Excel sheet, so I asked ChatGPT how much the company would make with Brent at $100.
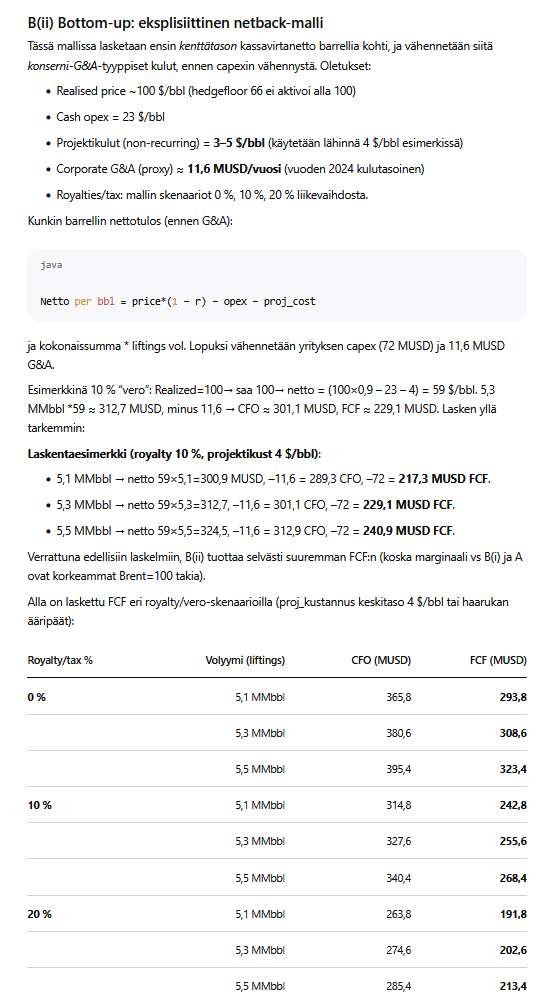
P/FCF 2-3?
The basic assumption is probably slightly bullish since the price curve is still downward sloping, though at last glance the August contract was also around 90 USD, so production disruptions are being priced in until the fall. The company has a suitable amount of debt, so the leverage should be pleasing to the shareholder even if the price disruption only lasts for a year.
Somehow it just feels like the stock is a value trap after all. Small market cap and an esoteric exchange. I would be surprised if the stock started performing better than Saturn Oil & Gas or Kosmos, which have practically the same tailwinds as Panoro.
Maybe the stock will start outperforming the others down the line  .
6 Likes
After a long time, Panoro & Brent have taken a bigger dip. The start of the year has been magical. Eka (alias Foreigner, I assume), what are your thoughts on the outlook after the Tullow deal and the private placement? The target price has been slightly lowered to around 35 NOK, but in my opinion, the capacity growth and the increase in oil reserves from the deal will support Panoro well into the future. Dividend-paying capacity will improve significantly at these oil price levels. The world understands that the era of fossils is by no means over. There also seems to be a broad consensus that oil far from Hormuz and the Red Sea is (increasingly?) valuable, at least for the foreseeable future. Having added a bit to my position myself, I’m curious to hear the views of other enthusiasts in the sector. Could Panoro be an acquisition target? In my opinion, that possibility is a significant price driver, at least this year…
3 Likes
Using some very amateur math, I’ve been thinking that if Panoro’s production (after the Block G deal) is over 5 million barrels per year, with neutral $80 barrel pricing, Panoro could be thought to make a profit of around 90-100 million dollars.
And currently, Panoro is valued at around 415 million dollars. If Panoro were sold in a fantasy scenario, one could perhaps imagine a sale price of something like 600-750 million. But then there is the debt, which is a chunk of 250 million at the moment.
So, a relatively neutral valuation in my opinion. On the other hand, if oil stays at the 90-100 level for longer through the end of the year, the situation is different. Of course, oil companies might otherwise start pricing in a premium for production outside the Middle East, so there could still be upside.
3 Likes
It’s also good for Panoro that PEAK OIL is being pushed into the distant future. If for no other reason, then at least regarding the hefty dividend (also due to the impact of growing production), there shouldn’t be any problems in the coming years.
In my opinion, this shock will keep the oil price high even after this year. Russian & Gulf infrastructure won’t be restored to its former state in a year – maybe not even in two,
2 Likes
The reserves report was released today. Current P1 (proved) as of 31.12.2025 is 27.28 MMbbls, whereas including Block G, P1 is 57.94 MMbbls. With the deal, reserves will therefore more than double! The share price still has room to rise to a clearly higher level.
Regarding the valuation and possible premium for Panoro, it should be noted that we cannot underestimate the importance of stability, let alone freight and insurance costs, compared to operators in the Gulf region and their freight costs.
In my opinion, Panoro is becoming the Star of Africa 
4 Likes
Panoro’s management is truly magical when it comes to the timing of those acquisitions. The EG assets and the stake in Dussafu were bought from Tullow in early '21, just before prices skyrocketed in '22, and now more ownership was bought from Kosmos right before Trump’s attack on Iran. Last time I asked Hamilton (CEO), he was very eager to grow the company to a larger scale and focus on ramping up production. The general trend has been strongly towards divesting from African oil production, with Western companies focusing on American shale and South America. As undervalued assets are constantly being put up for sale, it is logical for Panoro to be a buyer. I don’t believe Panoro is interested in selling at these share price levels, but a merger with another player (for example, BW Energy) could be possible if terms can be agreed upon.
At the moment, I’m most interested in what John Hamilton plans to do next, as Panoro’s success has been down to good management. There has been some turmoil there, but his appointment as Chairman of the Board of Magnora indicates that his personal crisis is apparently starting to be over:
Magnora ASA:
As the new Chairman of the Board, the committee has proposed John Hamilton, currently a Board member (since 2018). He is CEO of Panoro Energy ASA and previously CEO of President Energy PLC, Managing Director of Levine Capital Management, and CFO of Imperial Energy PLC, plus spent 15 years with ABN AMRO Bank.
I would see Panoro as being best treated primarily as a growth dividend case with excellent cash flow yield, as there are no acquisitions (buyouts) in sight and the market is unlikely to place a very high valuation on the share price of a small oil company specializing in Africa in the future either.
7 Likes
Hamilton has certainly divided opinions as well. Panoro has also been in a long slump and the management has received quite a bit of criticism. However, one cannot disagree regarding the acquisitions—although the Tunisian adventure should have been avoided.
You are admirably well-informed about the company’s affairs. Somehow, I personally hope that Hamilton does not return—Balkany has handled both roles well. It might be good for someone else to oversee the next phase. That BWE combo would indeed be a very high-leverage combination for Dussafu. Could PNOR end its misery by cooperating with Panoro again (after Aje)? I believe this year will still bring positive surprises—there are so many bright drivers in the air—any one of them could well provide further positive momentum.
The opening of Hormuz in the near future will certainly cause the share price to dip, but in the long run, I completely agree with you.
2 Likes
Panoro made another interesting strategic acquisition in the late summer as they seek more predictable cash flow from gas through the deal with DNO.
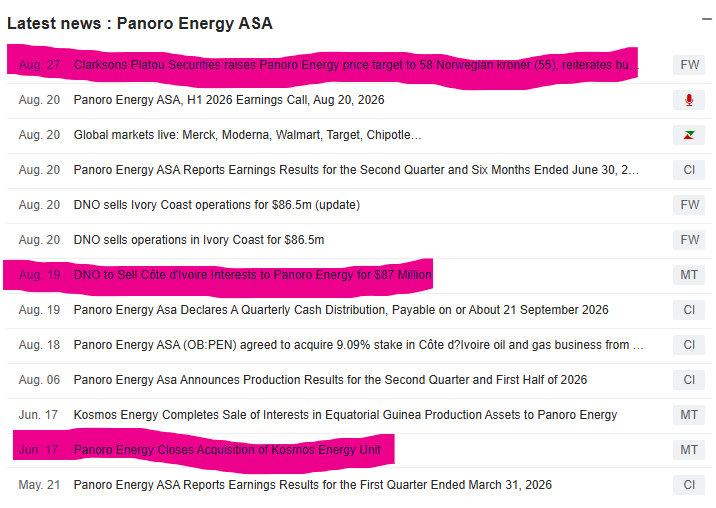
Analysts’ price forecasts haven’t been anywhere near the $100 per barrel mark for H2 2026. The majority of Panoro’s liftings are scheduled for the second half of this year. The upcoming earnings reports are likely to show massive figures, and 2027 will be even wilder if the conflict(s) continue.
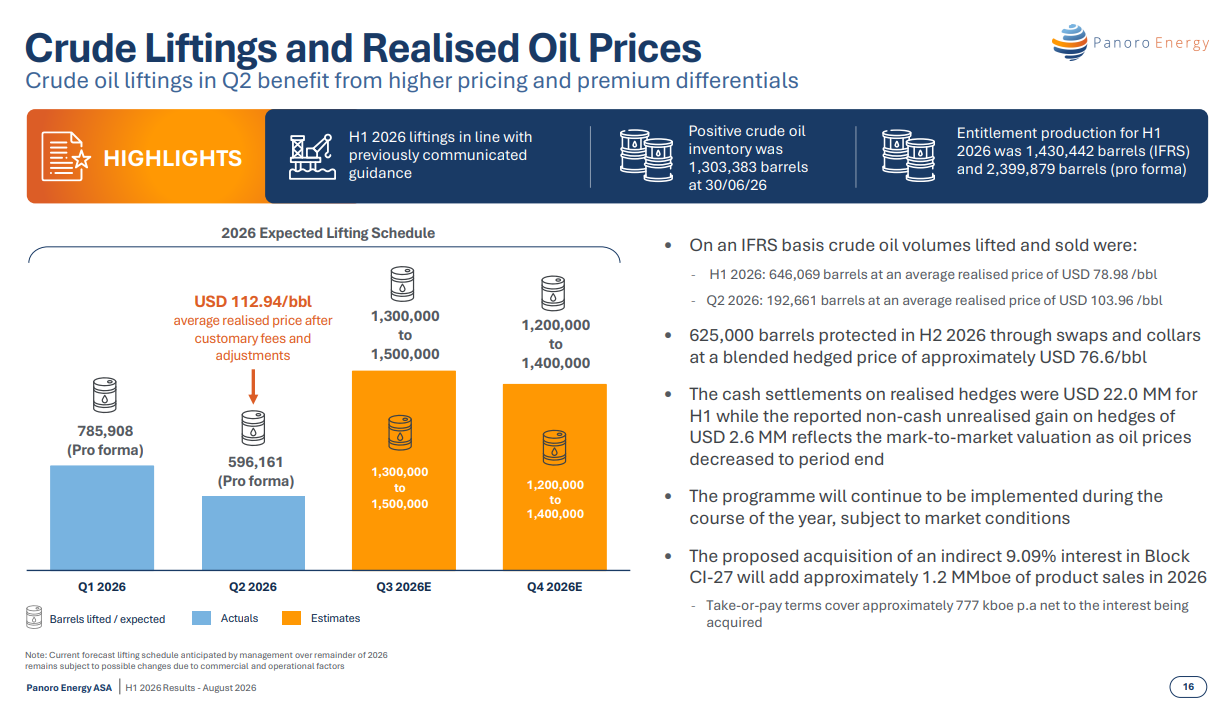
The global economy may eventually stall so severely that the demand for expensive oil will decrease sooner or later, but in the short term, Panoro is in an excellent position precisely in this geopolitical climate.
4 Likes
Unfortunately, the strong performance of the Norwegian krone against the US$ dampens about 20% of this brilliant potential right now and perhaps also in the near future. At NOK 31.5, the current share price relative to those prevailing target prices of +NOK 55 is in too large of a mismatch to make sense. Let’s hope that the Q3 & Q4 results create a sustainable foundation for a rise somewhere into that middle ground. A lot independent of Panoro can happen over the next six months, so based on belief and hope, there is admittedly a very attractive upside potential left.
3 Likes
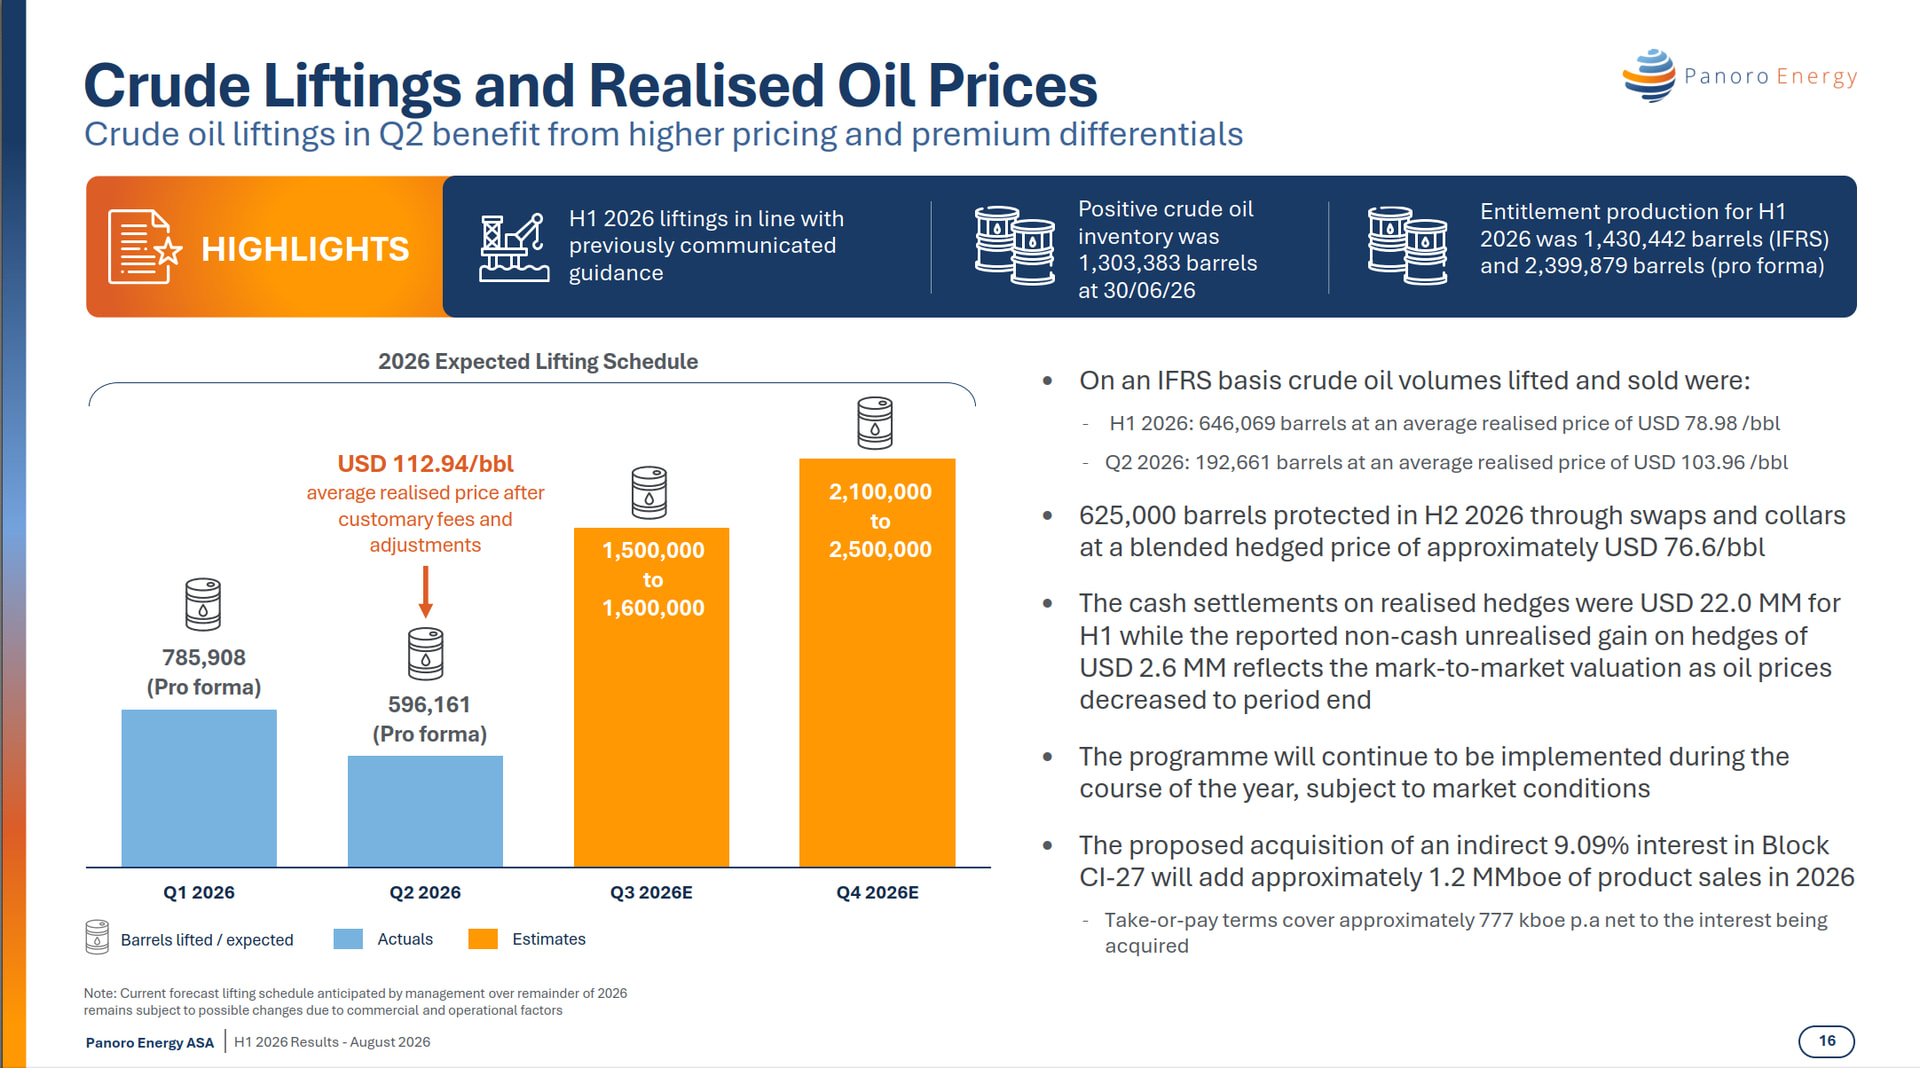
Here is the same slide corrected regarding future liftings. The corrected Q2/26 presentation can be downloaded from the company’s website https://www.panoroenergy.com/presentations/
7 Likes