A small addition of Enento to the securities account, 10 pcs @ 14.56 €.
At the same time, with this tactical move, I managed to prevent the after-party of the Christmas party today by citing “- Sorry, can’t do it, went to the stock market”. Saves money and health, even life (that modern nightlife is scary and dangerous), and the old investor uncle can’t handle such things anymore…
Tripled my Tokmanni position, which I opened earlier at around €8. It’s starting to look quite cheap, but that’s how a discount retailer should be. In my opinion, a large part of the share price reaction is due to the cancellation of the dividend payment, which I don’t attach any importance to. The money stays with the company and into next year with a stronger balance sheet.
Storaenso added. I wonder about the share price reaction, now that it’s finally clear that the forests will be listed and shares distributed to current owners (current value of forests something like EUR 5-6 billion). Will buy more if it drops further…
Hmm. I already had a lot of it, but to my eye, this falling wave could be nearing its end – at the very least, a support level has now been reached in Helsinki’s quotation.
Why is this?
I see that Nokia’s business excluding its mobile division is well worth the current share price – and in fact, including patents and software, even more. The Infra (Infrastructure) side is where there is significant value right now – in terms of market value, it should be priced at a minimum of 20 billion euros.
The Nvidia deal has already been more or less priced in. And thus, the mobile side remains a significant option. However, in my opinion, the value of this option will only become apparent within 1-2 years at the earliest.
CMD (Capital Markets Day) is now on 19.11, and in connection with this, there are now somewhat mixed feelings due to the Nvidia deal. The outlook for the Infra (Infrastructure) side will be a positive surprise, but growing investments in Mobile in the coming years might bite into this joy. Everything really depends now on how convincingly things are communicated, and what the long-term goals look like. What can be said about Mobile when the strategy received a new alternative? However, the targets must be high, so I suspect a rather bullish presentation.
In my opinion, at the current share price, it is more likely to see a significant rise than a fall.
I have shared technical analysis related to Nokia from time to time, and in my opinion, the upside potential has not yet been fully realized. Much, of course, depends on what kind of time horizon one is willing to use. When stretched sufficiently, the risks decrease in this case.
Btw. There are currently 33 different analytical bodies covering Nokia, not all of whom have yet updated their forecasts and target prices. Those who have updated have all raised their target prices (after the Nvidia deal), and even with incomplete updates, the average target is currently €5.742. Of these 33 forecasts, only 5 are negative. And three of these five seem to come from Finland – from this land of Nokia syndrome.
I try to be brave when others don’t dare to be. And sometimes I’m wrong, so this is not a recommendation.
Edit: Oh, I forgot to write that it seems likely that Huawei will be banned from the EU network markets. This opens up a multi-billion annual potential for Nokia to achieve additional revenue, and in fact, with the ban, that is even probable. This could serve as a deserved driver for the stock in the near future.
Sold the remaining 1/3 of Intellego (500 pcs) for 47 SEK. The numbers and reported information don’t quite match up. I racked my brain trying to decide what to do, but the choice fell on selling. When trust in the honesty of the company’s management is lost, it’s difficult to continue together. The stock price can go anywhere, but the gambling has stopped now. Originally, I invested in the company and didn’t speculate on the stock’s direction, but now it feels like being involved is mostly gambling. There’s a slight fear that a new short report or red flags will emerge over the weekend, as the story doesn’t quite match up. OJ got out of a difficult situation because of gloves that were too small. Sometimes a small detail can change everything.
I ultimately made a good profit from this, as I had put 1172.5€ into this batch. The amount received from these is approximately 2130€. If the rise had been steady, I would feel better. Such a rollercoaster, always up to 220 SEK and down to 36.2 SEK → 47 SEK, feels different. The end result is the same, but the human mind processes these differently, even if there isn’t much logic to it. I try to think positively that I still got the highest returns of my investment history from Intellego and a hell of an experience.
Special thanks to @ValkoinenPeura for bringing up the discrepancies.
Added small batches of Tokmanni to a falling stock price for myself and the children.
Dollarstore’s problems have been acknowledged, as have the upcoming seasons. Christmas lights, decorations, and gifts are already selling well. At least in local stores, the door is constantly busy. In small towns, it’s often the only place where you can get, for example, oil for a Toyota or
Got back into SSH, 500 shares/€3.10. In the long run, it is believed that trades coming through Leonardo will turn the results positive and the share price
I see a fairly long (perhaps about 3-4 years) transition period, but with network updates, contracts will need to be renewed significantly earlier. And thus, well in advance of the end of the transition period, changes will start to emerge. Now, the ban just needs to come into force so that Southern and Eastern Europe, Germany, Finland, etc., would start to accept the change.
And if the ban were to be approved, for example, in spring 2026… it would likely cause a so-called maintenance backlog as companies start to stop purchases from Huawei, and by the end of the decade there would be quite a replacement boom - perhaps even earlier.
VanEck Quantum Computing UCITS ETF, bought roughly a month ago @22.82, now sold @20.8. Loss of approx. 10%.
Probably at a bad time, but the idea is that those where returns are still potentially further away might react a bit more violently than others in this uncertainty.
Edit. Also sold Terveystalot, acquired after the dividend dip, at @9.18, a bit of a loss from this too. The ongoing discussion around occupational health is not adding a positive sentiment, at least.
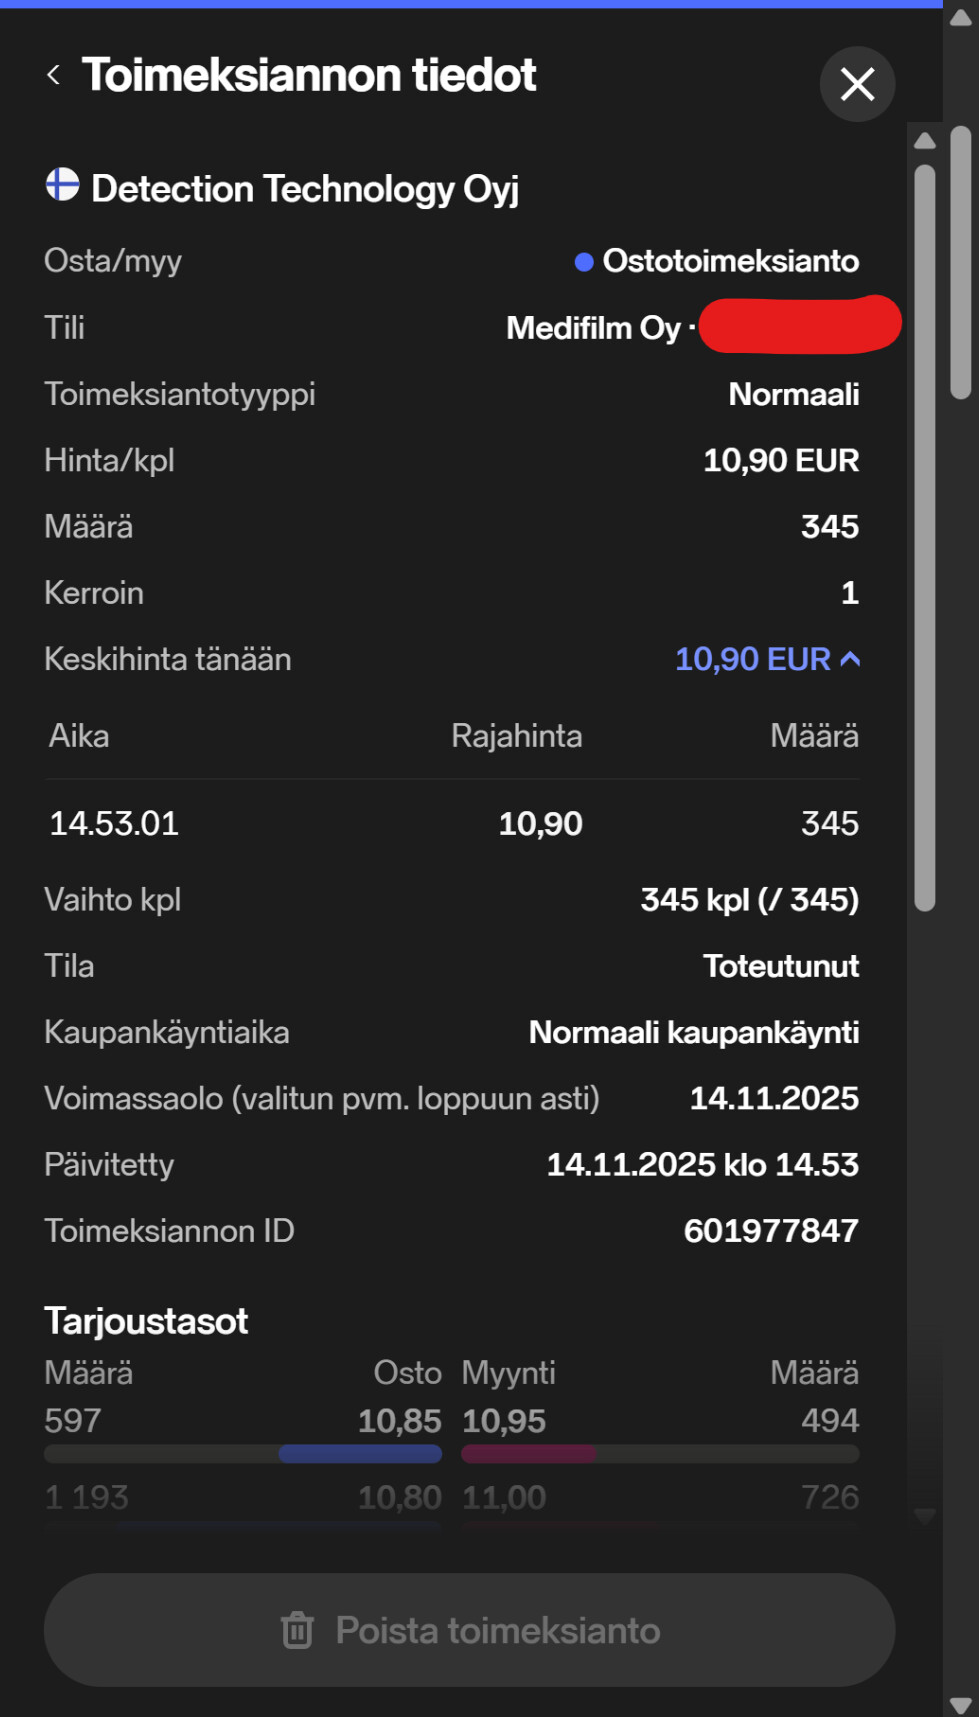
Added a minimal amount of DeeTeetä below the Model Portfolio’s entry price: 345 units at €10.90. It could still develop into a weekly bull flag if it doesn’t drop much, and then a monthly
All foreign wonders sold except Iren - i.e., crox, celh, oscr, pluxee.
I had decided to sell Pluxee because risks (at least seemingly) materialized, this time in Brazil. Yahoo ist Teil der Yahoo-Markenfamilie. I don’t have time to follow it at all. I had just been waiting for a bounce, because the initial reaction seemed overblown compared to the available data.
The aforementioned US firms are all good and moderately priced in my opinion - although oscr carries additional administrative risk on top of an already stormy US market.
I might buy them all back very quickly, but now is a very risky time to own US stocks in my opinion - I need a breather. I really only left the queen of the hill. Before I expand back, I need to get some clarity on where things are going. If market closures and other continuous fighting become the new normal, the bottom is low.
It doesn’t help that I’m so busy at work and home that I barely have time to breathe
For following Iren, I have my own network or, in Finnish, echo chamber.
Following LapWall, Fodelia & NGH is easy through the forum.
Other sold investments can be bought back from the stock market when it feels right. It might take a while before fundamentals and execution across the pond have an impact on the price. I’d gladly be wrong.