Adding Qt for the first time since November 2022. It feels bad to add, but I’ve been considering this addition from various angles for months.
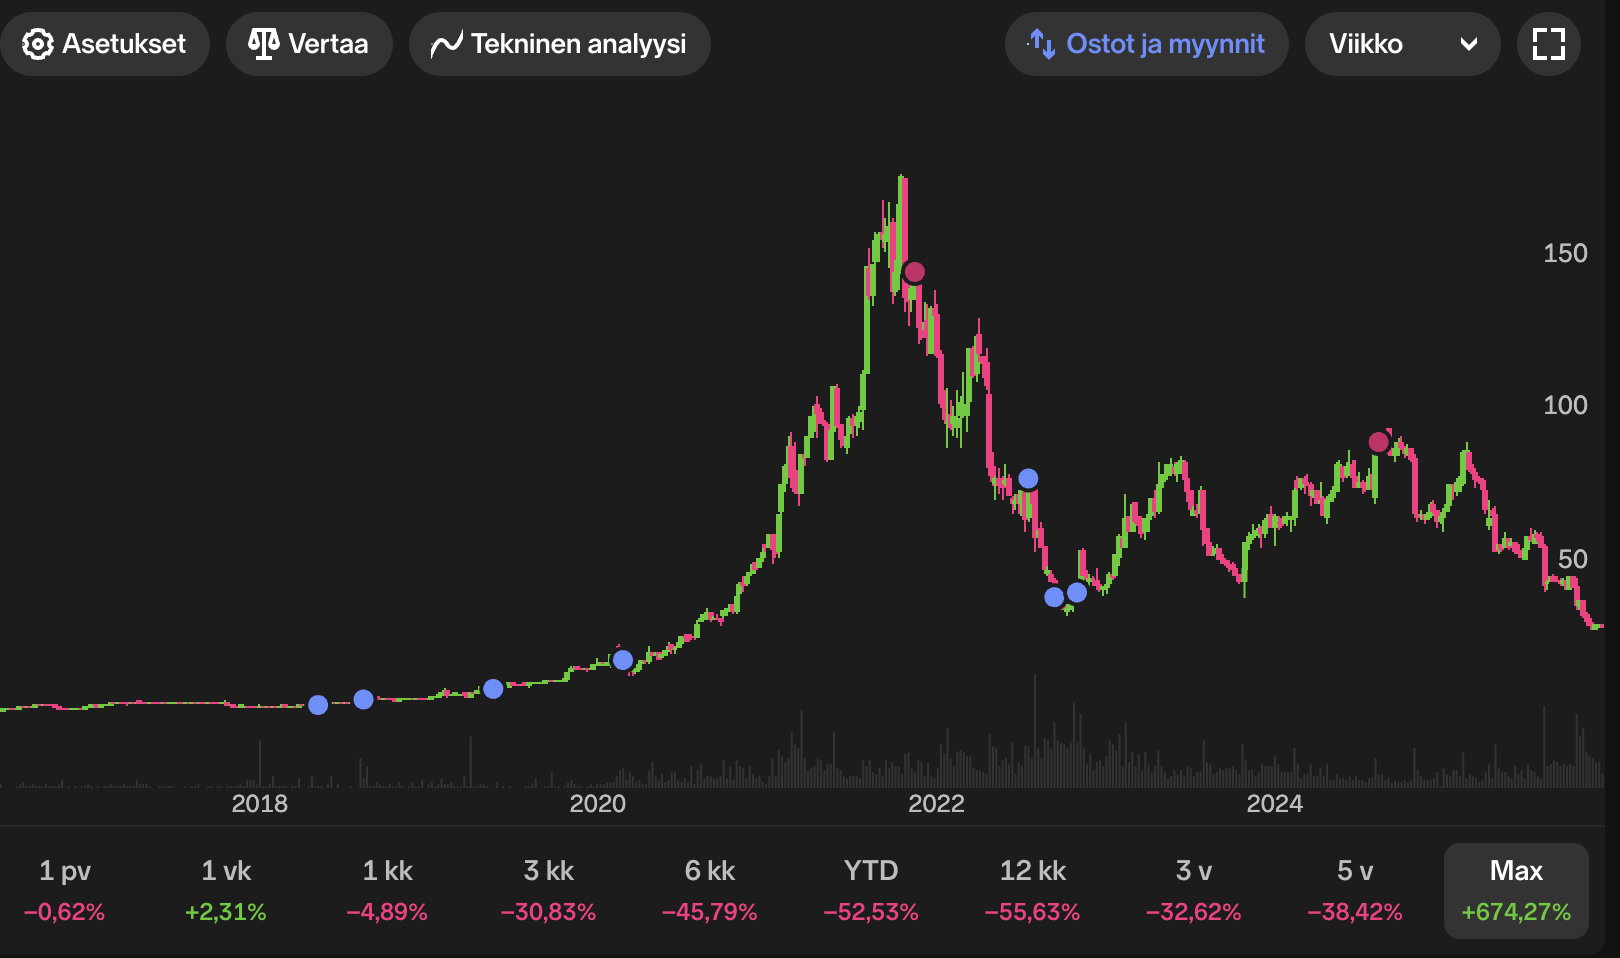

A few scattered observations I jotted down for myself.
-As I understand it, the company is suffering from customer caution and a weak market situation for consumer goods, not increased competition.
-The big picture hasn’t changed: the number of graphical user interfaces is growing faster than the number of developers. Developers therefore need to become more productive, for which Qt is an excellent solution.
-Data management is becoming increasingly important. A product made with Qt can keep its own data, unless the manufacturer wants Google to be involved.
-The company’s niche is quite small in the big picture, which limits the enthusiasm for competition anyway. Niche stuff.
-The stock trades at EV/S 4.5x. The company should be able to achieve 40% margins in a mature phase, so implicitly the stock trades like over 10x EV/EBIT.
-Sentiment is pitch black. The forum thread is in a state of apathy. Institutions globally are talking about “it’s a scam”. There are short sellers in the market. The latest rumor I’ve heard in the industry is that the company didn’t do proper DD (due diligence) regarding the IAR acquisition.
-The company’s fluctuations between one-year and three-year licenses have intensified the revenue hiccup, but this effect will level out over time.
-The main owner is reliable, and even though investors’ trust in the management seems to be wavering or even gone, the current management has built Qt into an international success story and sales machine, which is rarely achieved in Finland.