Wishing everyone an exciting start to earnings week! Last week was very turbulent. And the stock is now sitting at the bottom of its trend channel, so no more declines, please!
I’ll start off the posting with an apparently fresh 2027 capex chart from Morgan Stanley. Looking at the names here, Nokia seems to be in a distinctly favorable position with Google, Microsoft, and CoreWeave. Their combined capex would be 631 billion. I suspect Nokia’s slice will be several billion.
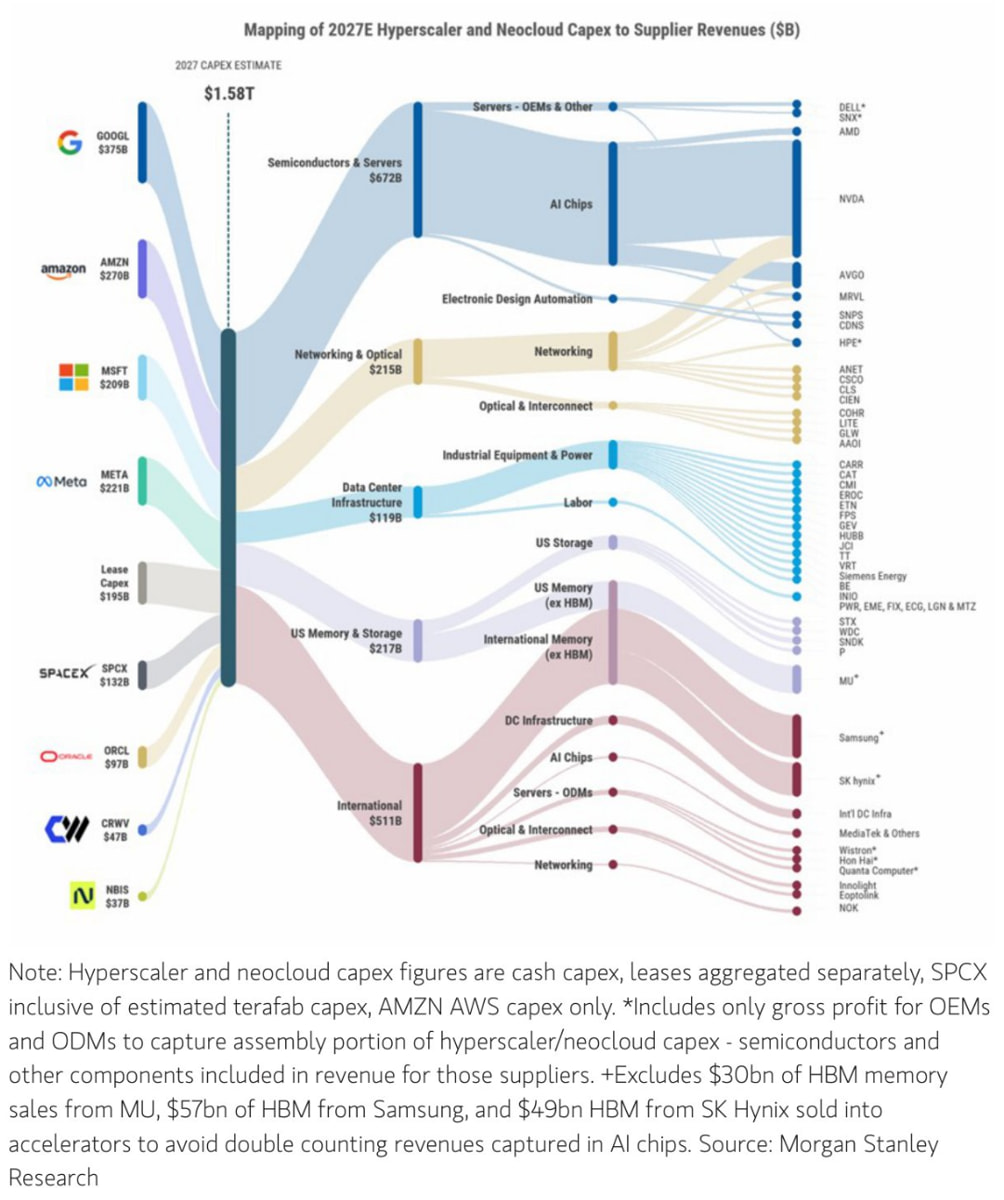
In my opinion, there is no fluff in the forecasts—quite the opposite.
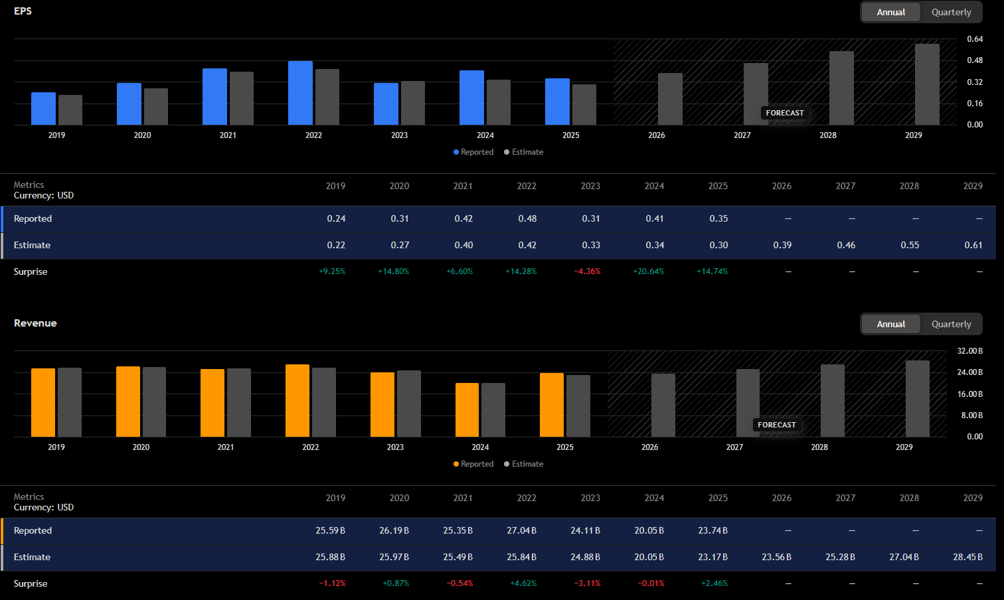
The key points of interest for the Q3 results will be future guidance and AI orders, where the hope is to see figures over 2 billion on a quarterly basis. I would really like to see estimates revised for future years—other players have already done so. Personally, I don’t believe Nokia will change its 2026 guidance yet; they would rather demonstrate their strength in full next year. And for 2028, the big picture should be repainted entirely.
Also related to this, the ramp-up of InP capacity in San Jose is under the magnifying glass. In Q2, it was stated to be on schedule. It should be ready soon; however, ramping up 6-inch wafers has been problematic for competitors as well, so this is by no means a given.