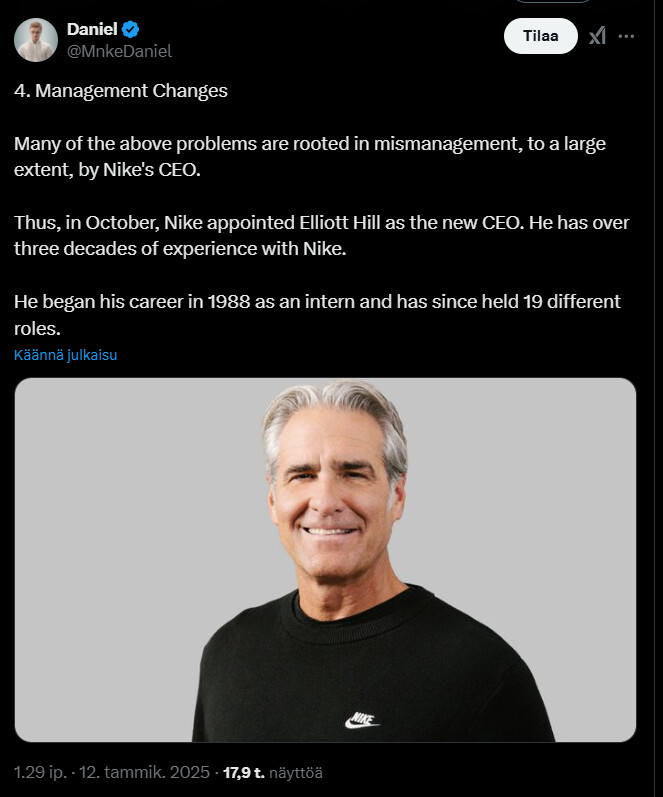
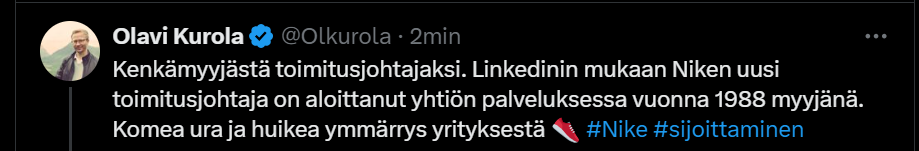
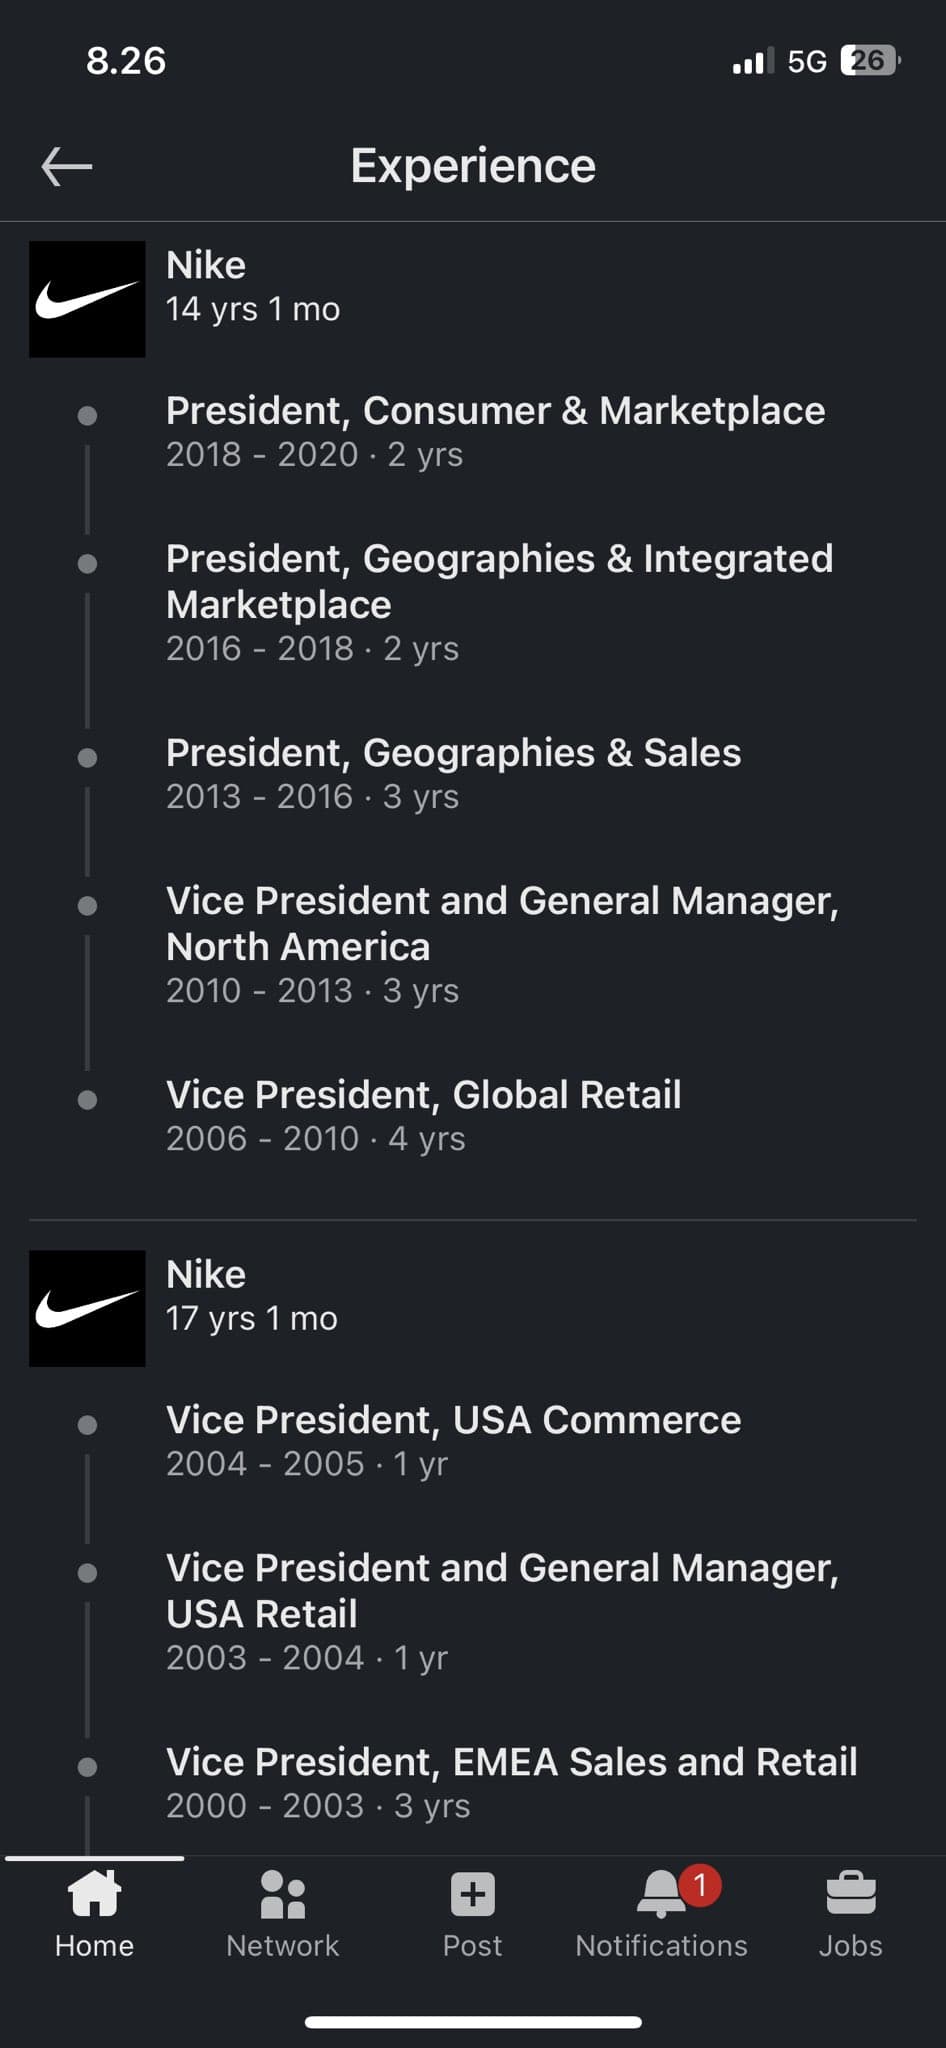
Yesterday, news broke that Elliott Hill has been appointed as Nike’s new CEO, replacing long-time leader John Donahoe.
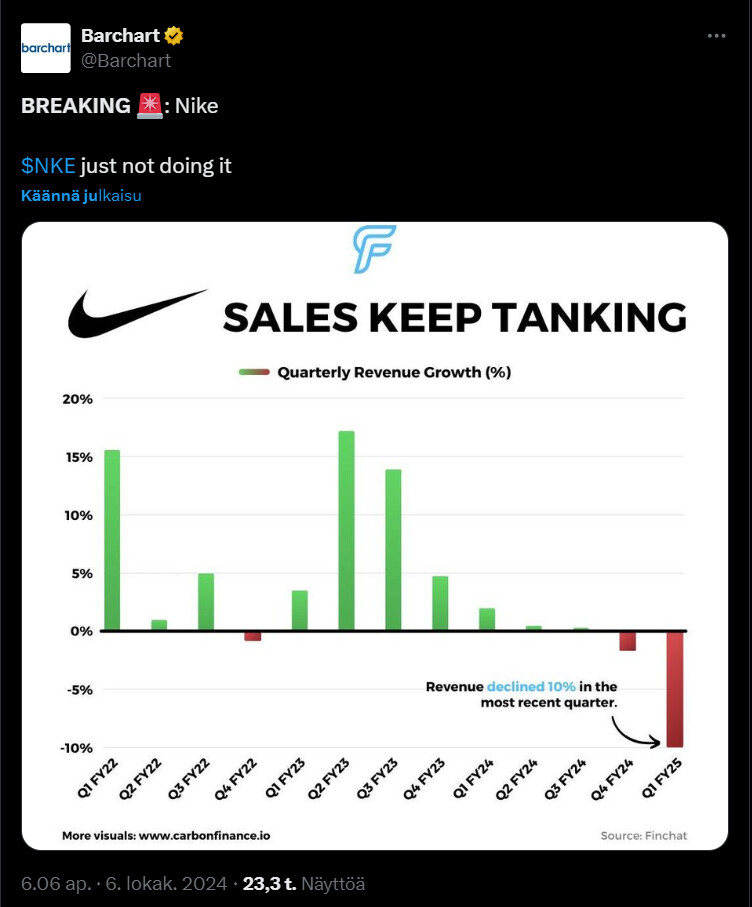
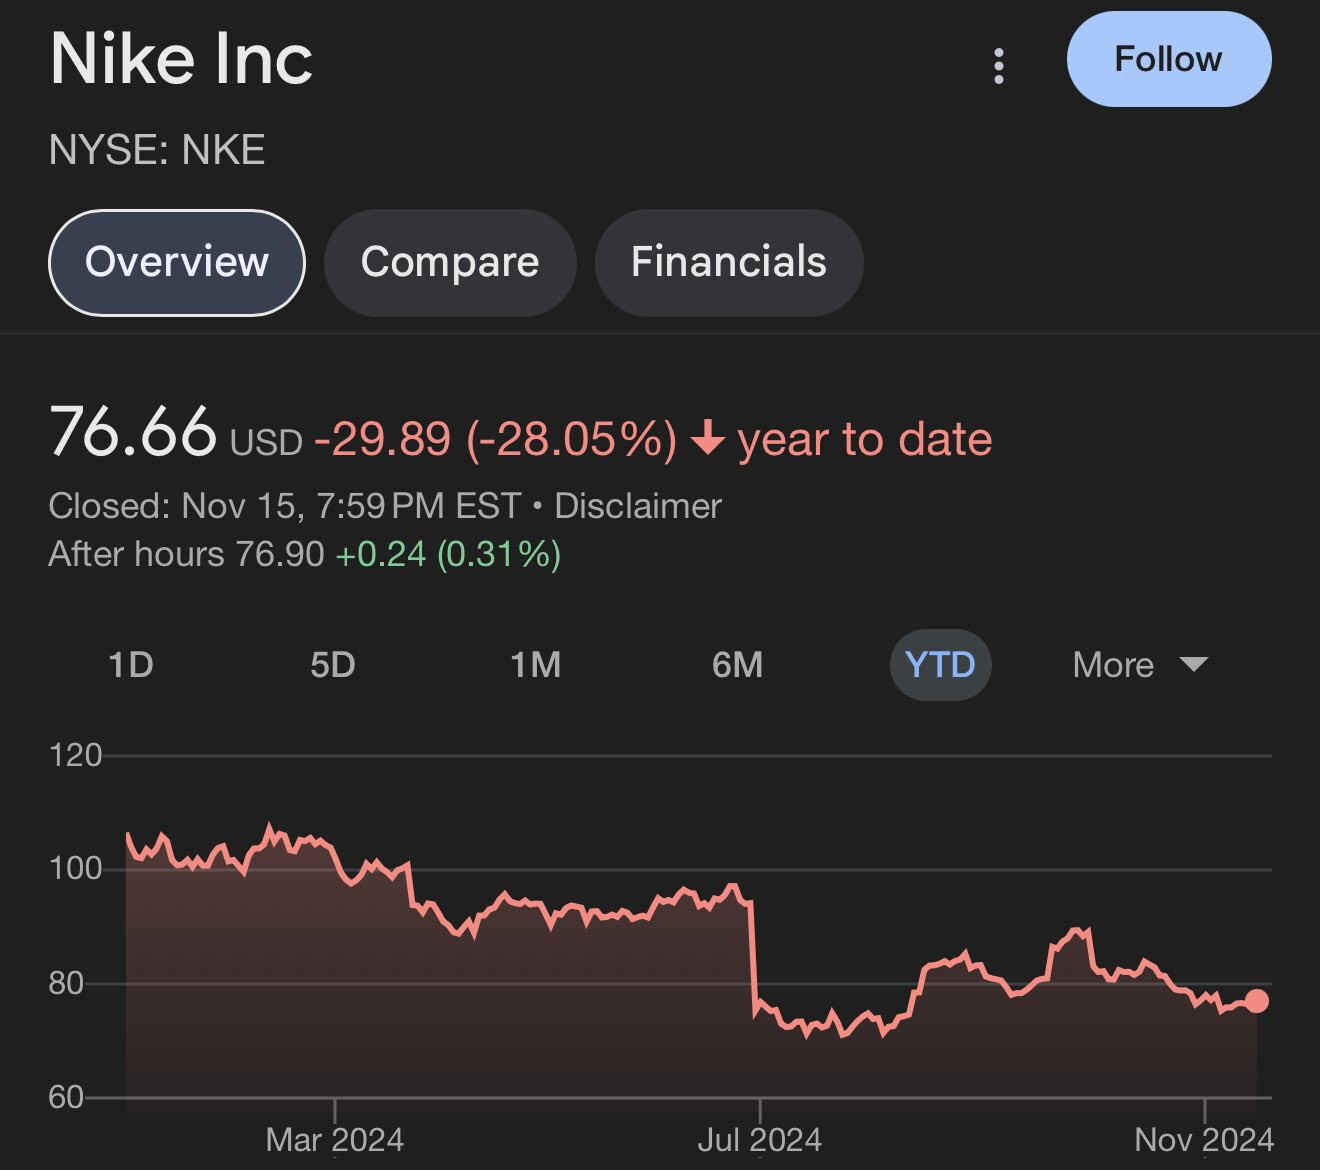
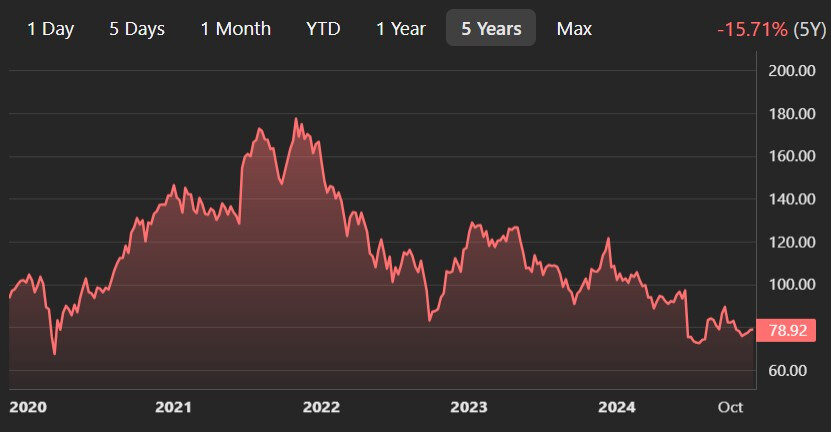
Hill admitted to staff that the company has faced difficulties and encouraged swift action. Nike reported weak fourth-quarter results in June, which led to a crash in the share price. Under Donahoe’s leadership, the company also initiated a $2 billion cost-saving program and staff reductions.
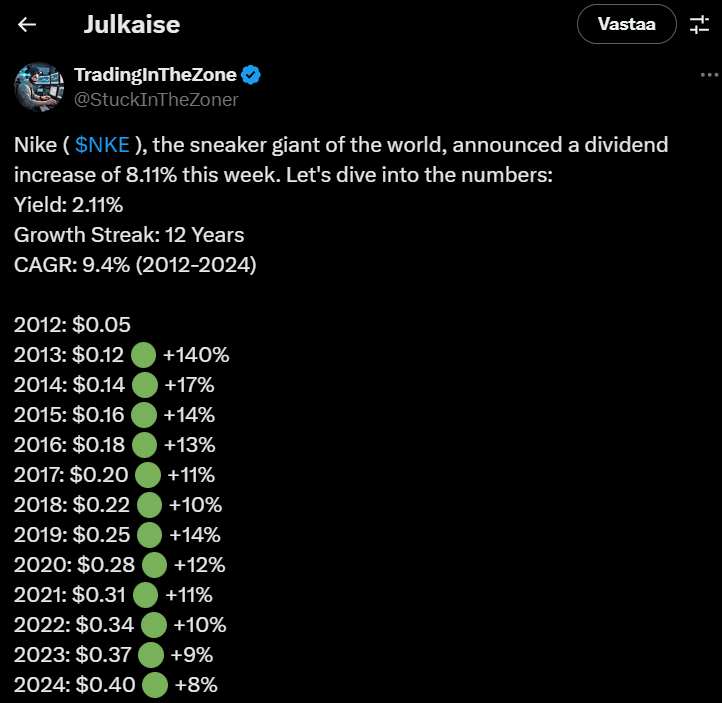
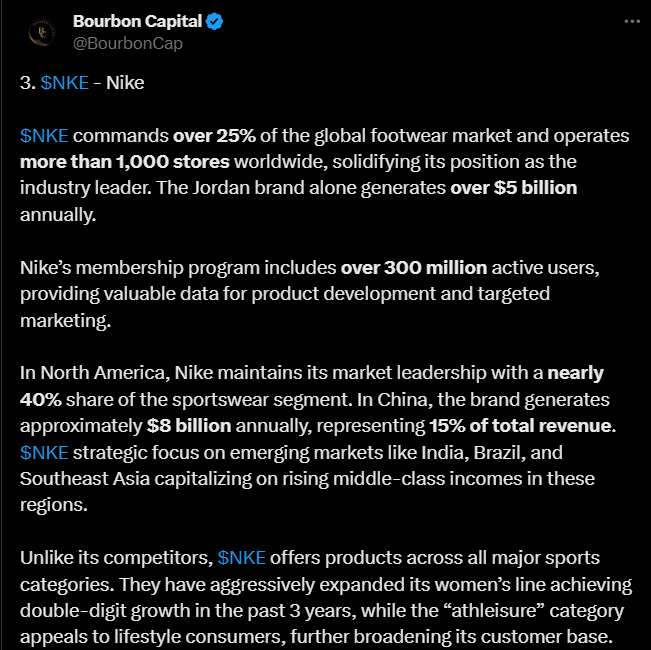
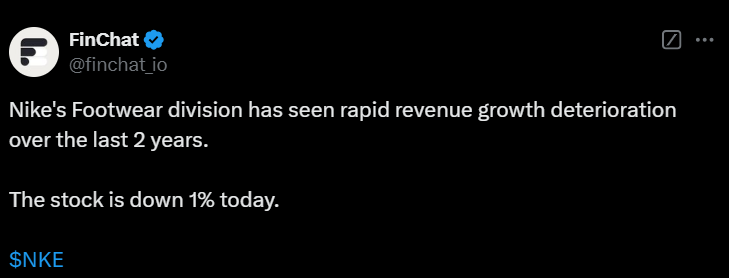
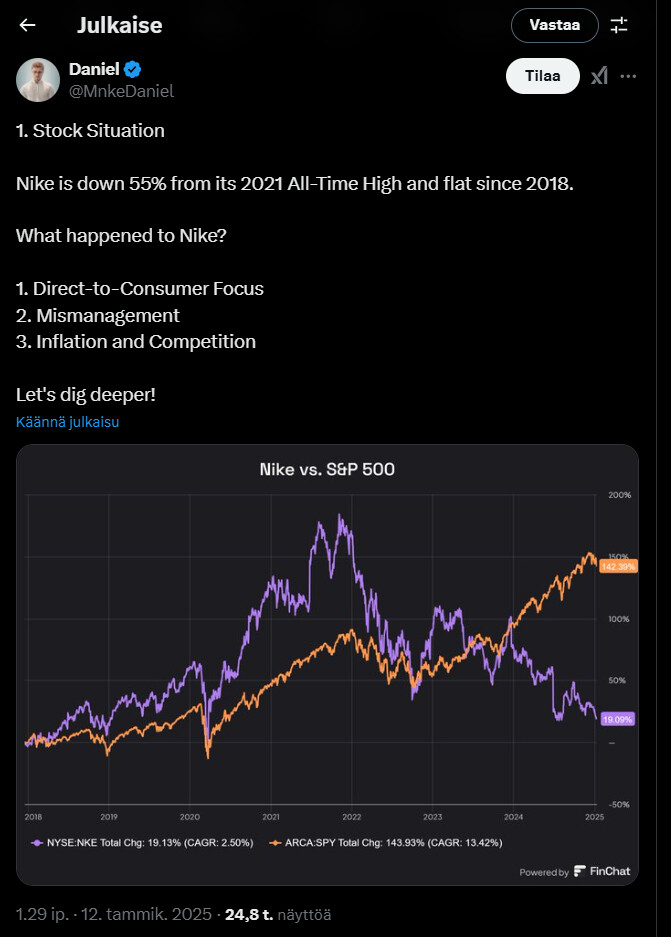
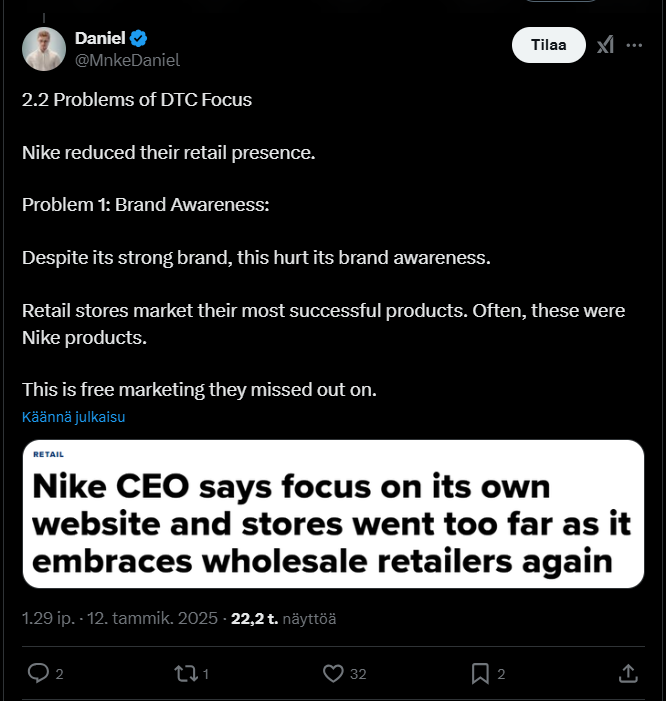
According to the tweet, Nike may be an interesting stock, especially with the appointment of the new CEO Elliott Hill, who starts in his role on October 14 and brings with him a solid understanding of Nike’s corporate culture and market situation. He has the opportunity to fix previous strategic mistakes made by the company, such as focusing too much on direct-to-consumer sales, which in turn weakened relationships with retailers.
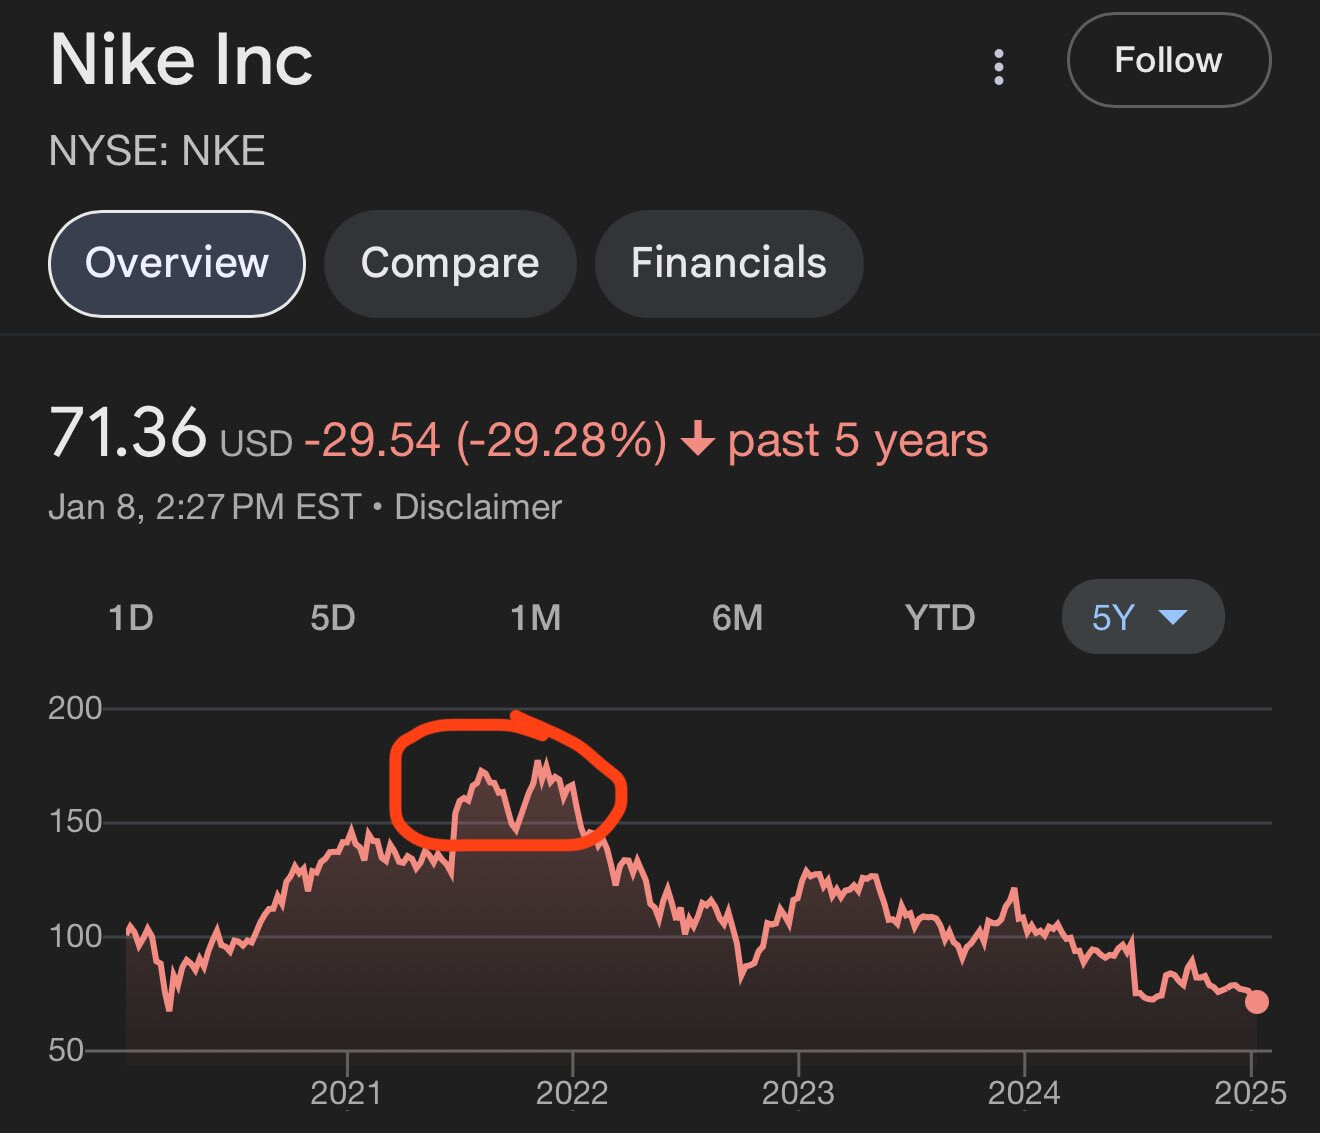
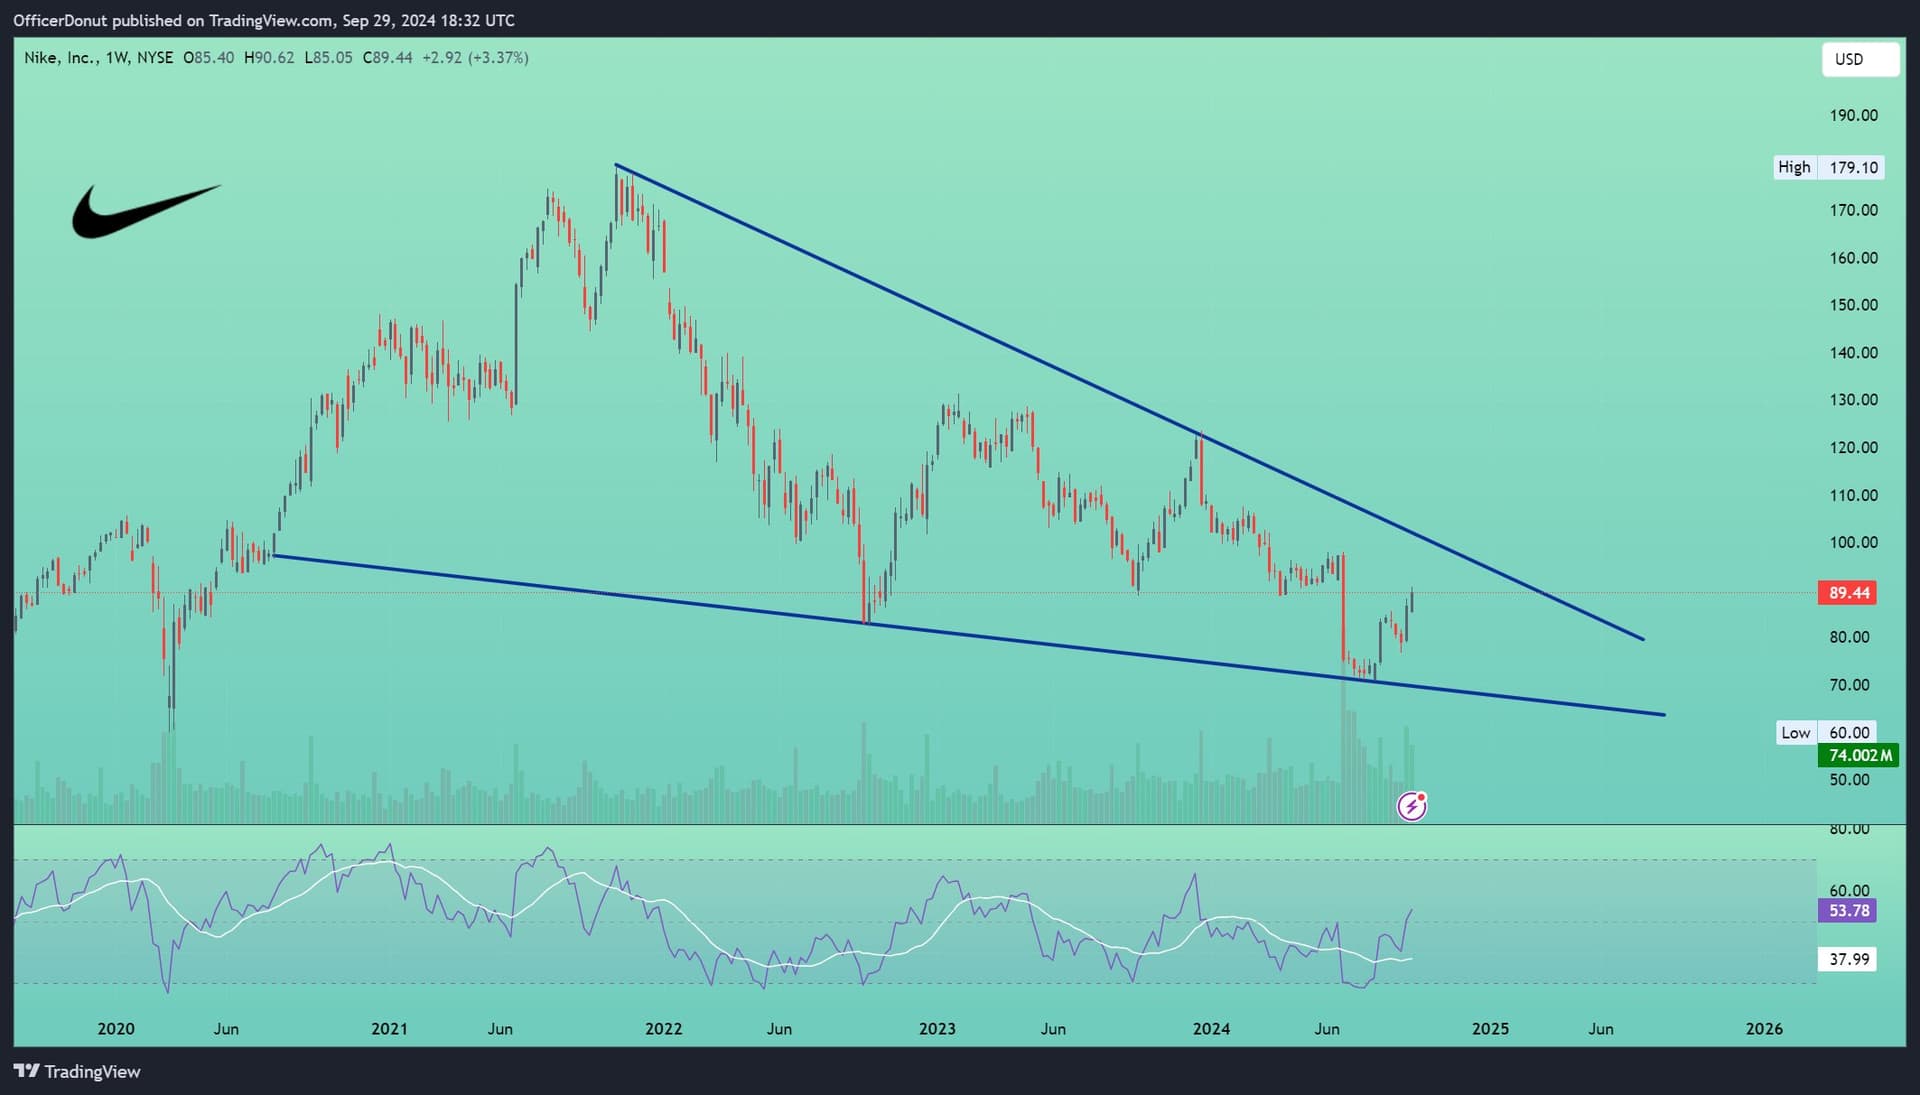
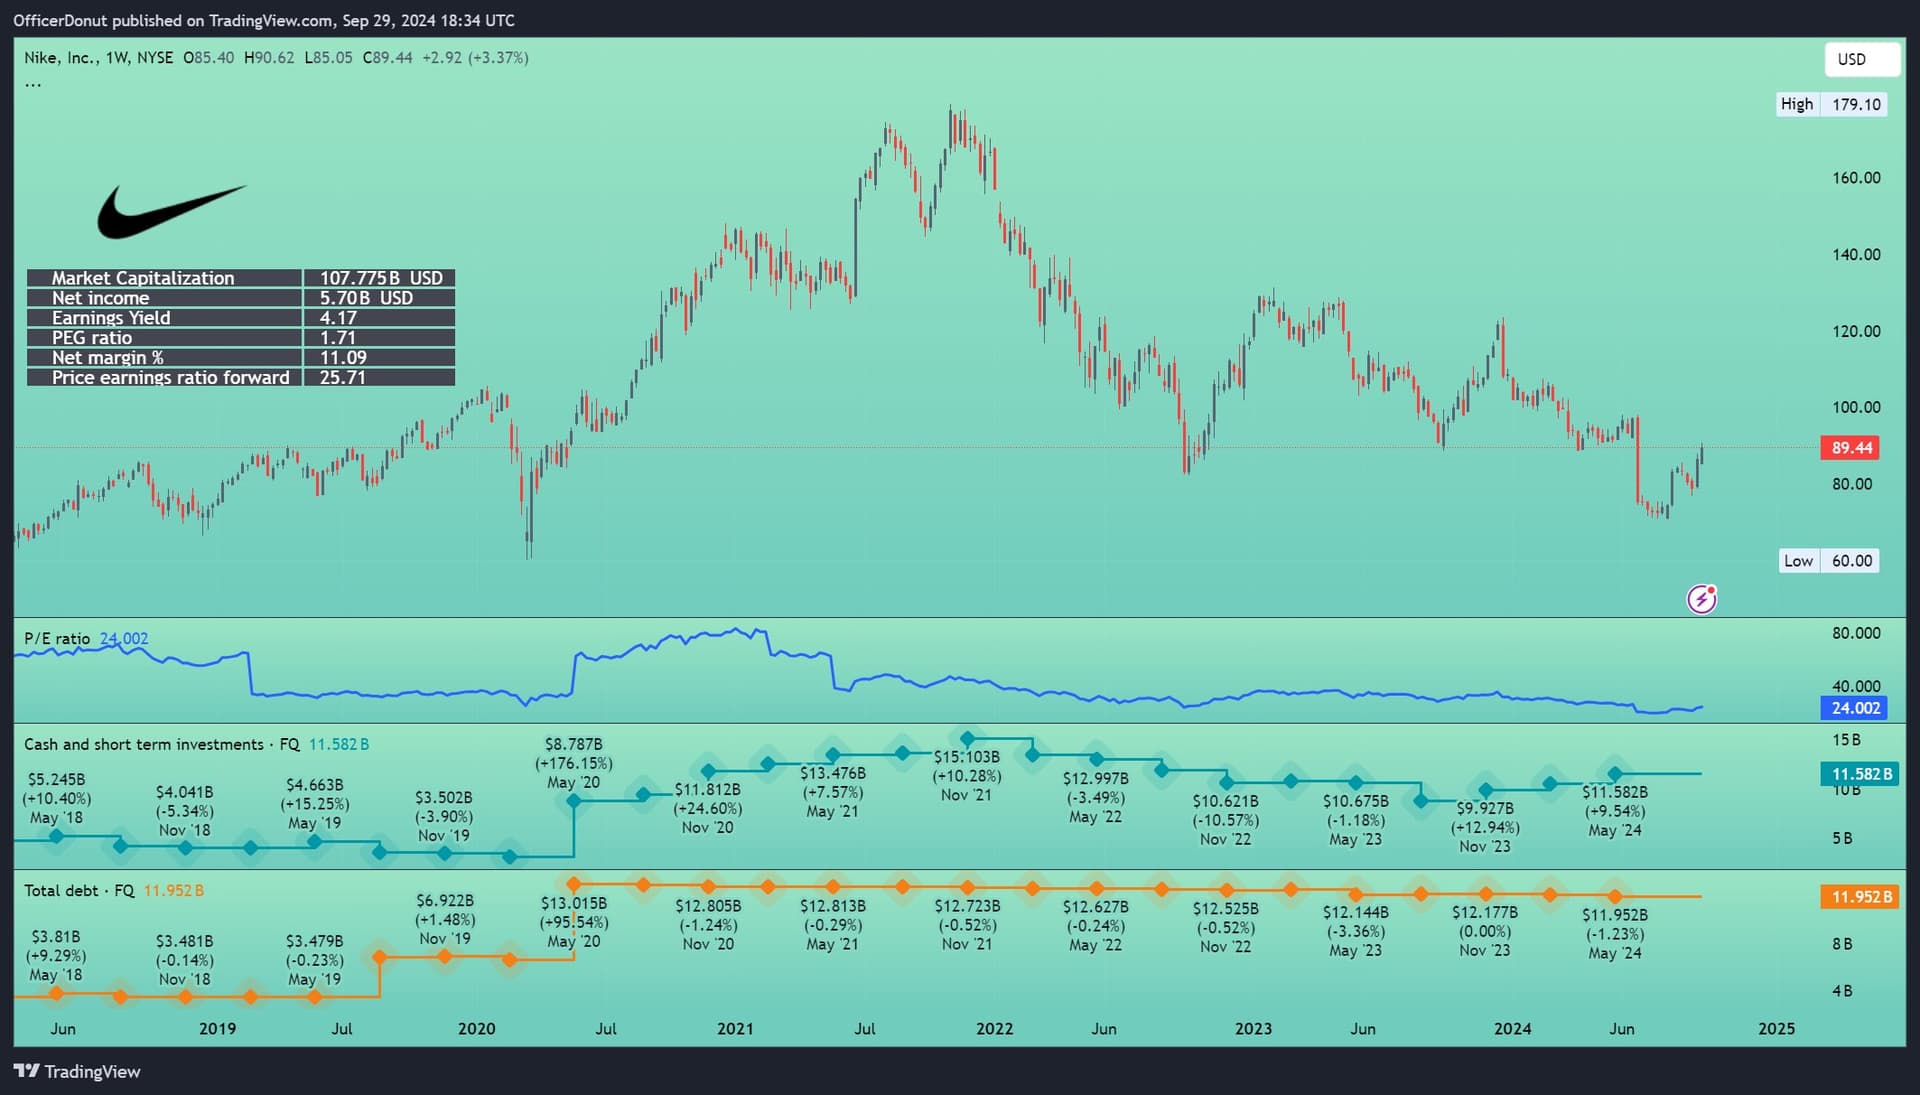
Technically, Nike’s stock is moving in a downward trend (?), but a positive earnings report could lift the stock back to the $100 level. On the other hand, the tweet suggests that a negative result could lead to a decline to the $70 level. Nike’s P/E ratio is 24 and its growth prospects are modest, at about 3% annually.
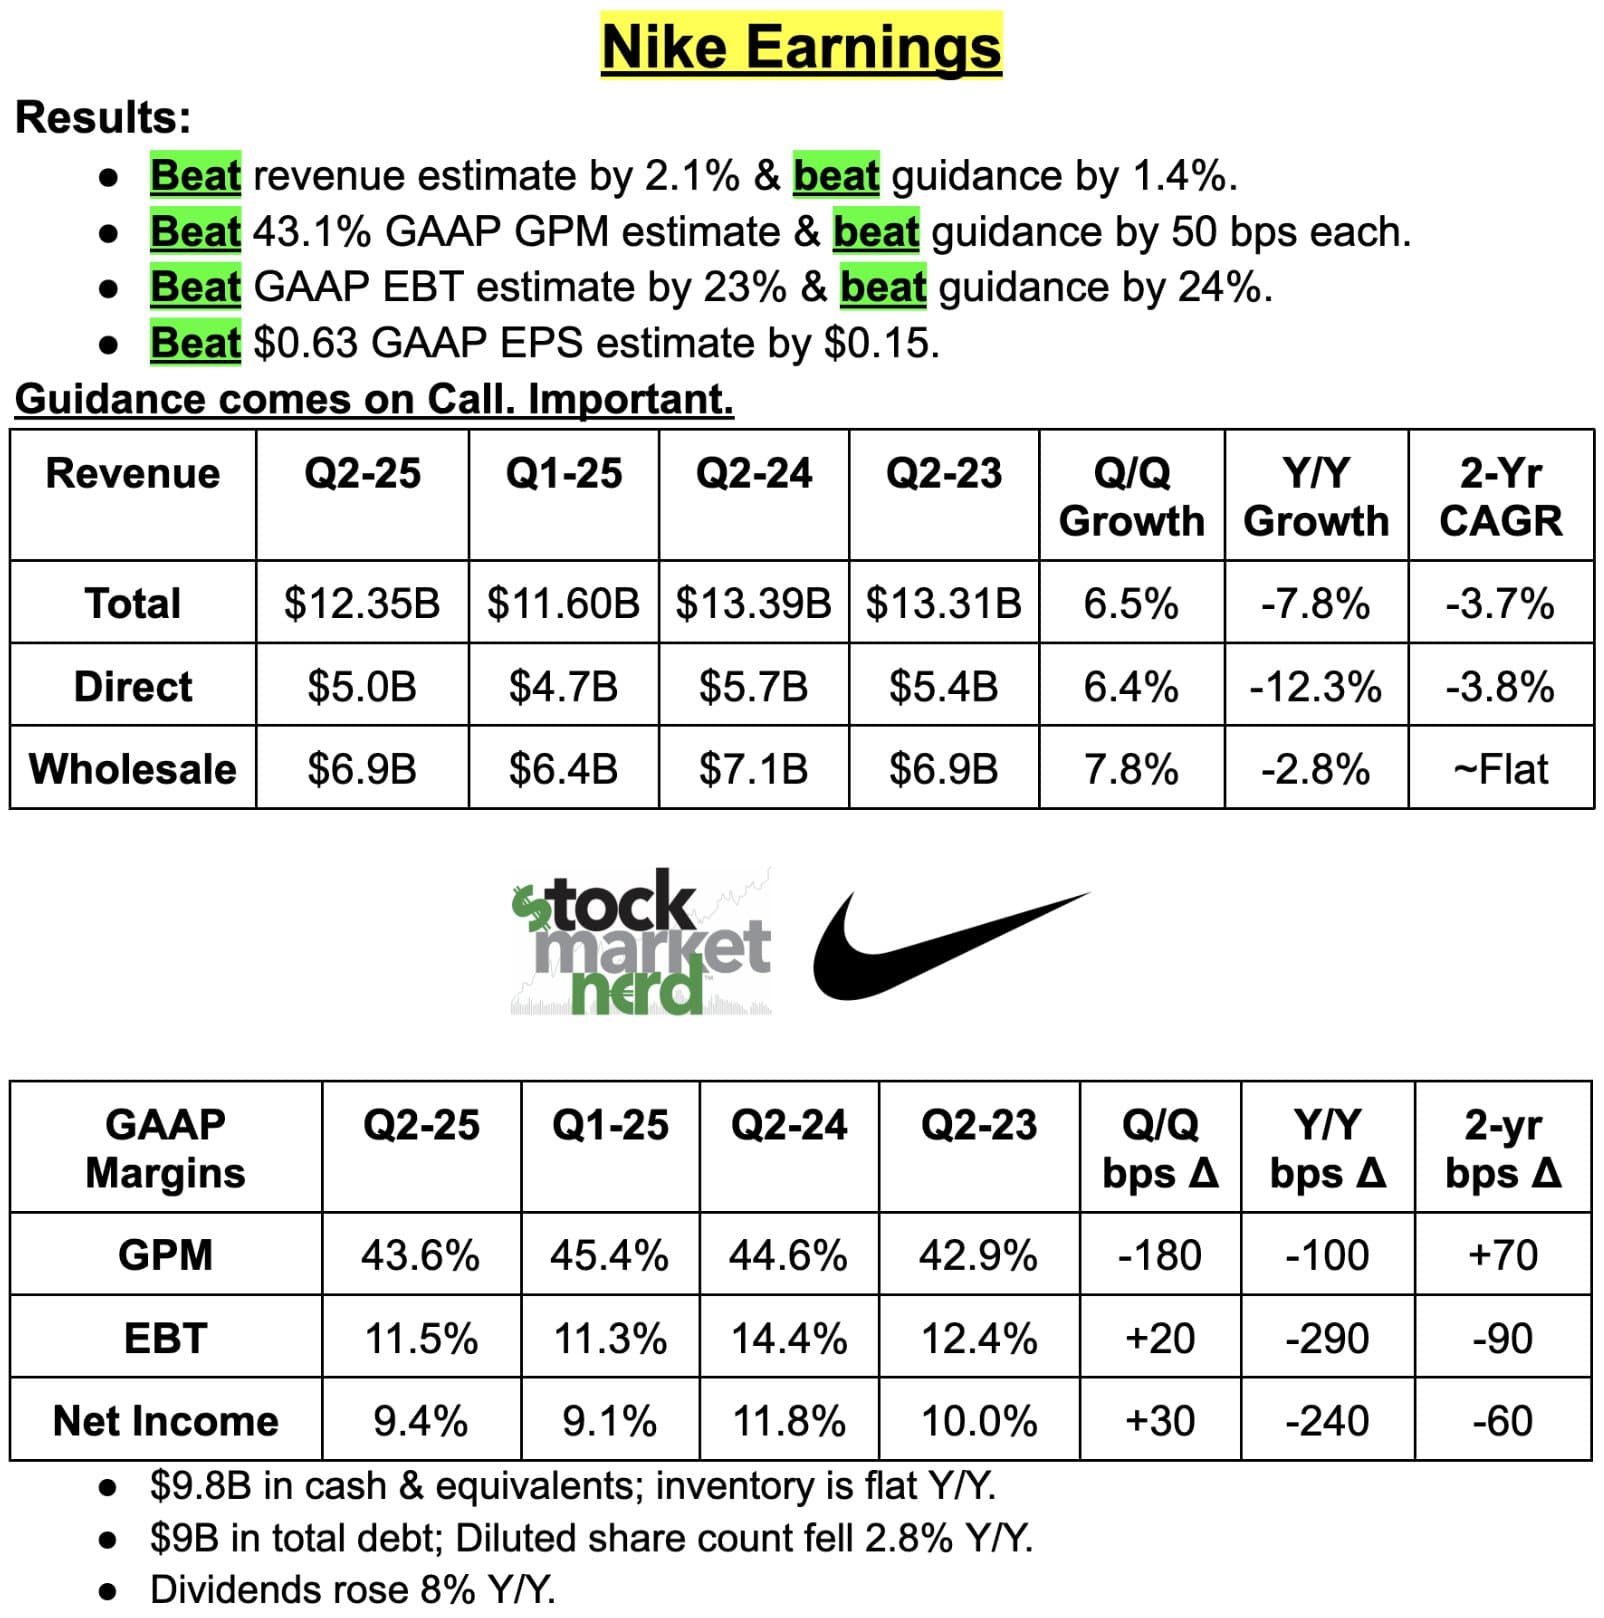
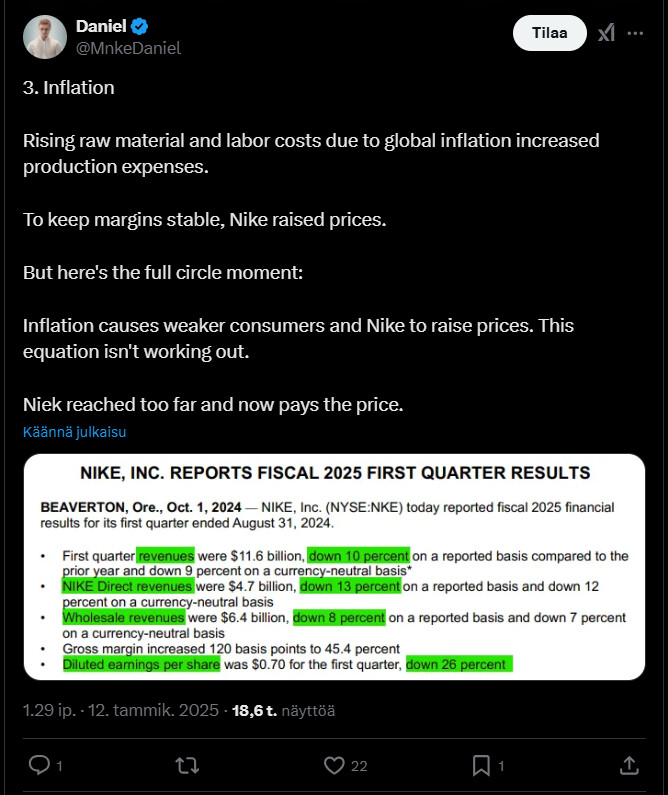
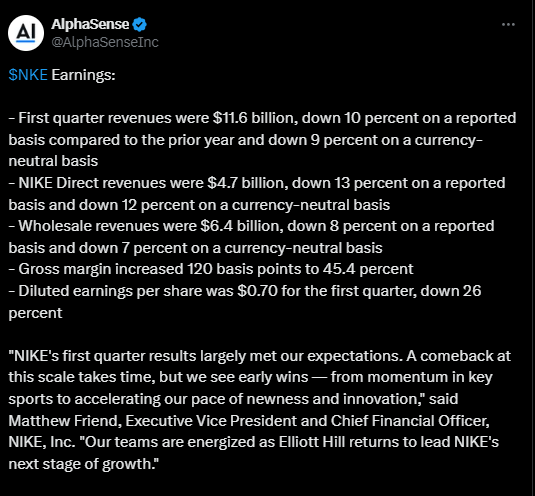
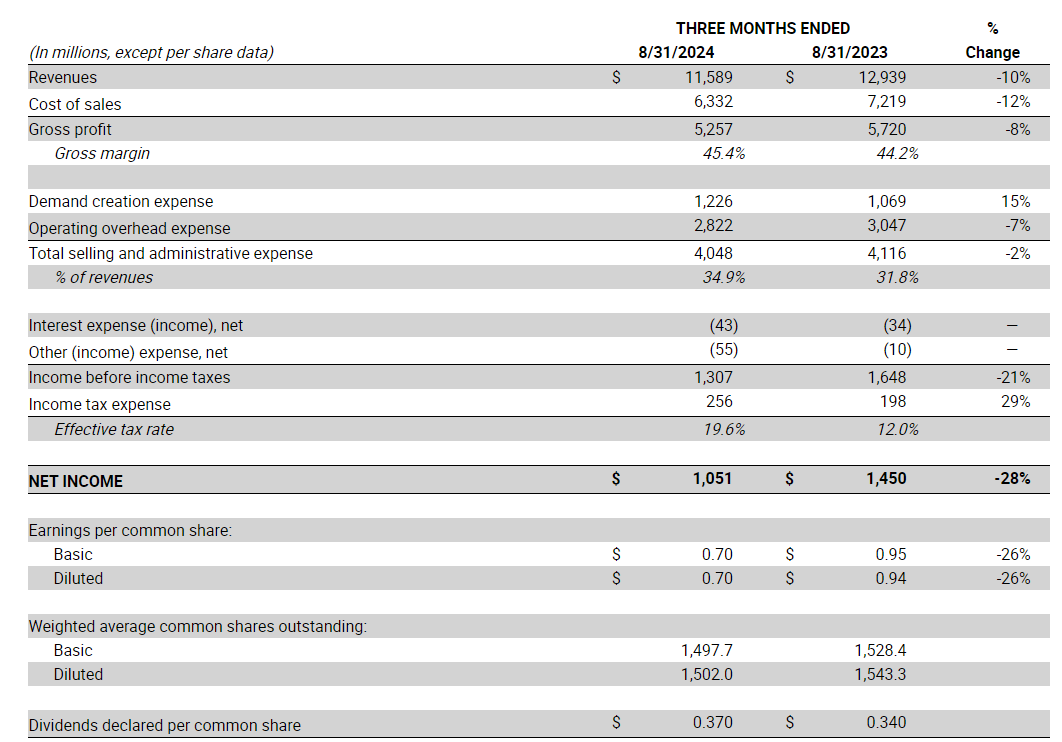
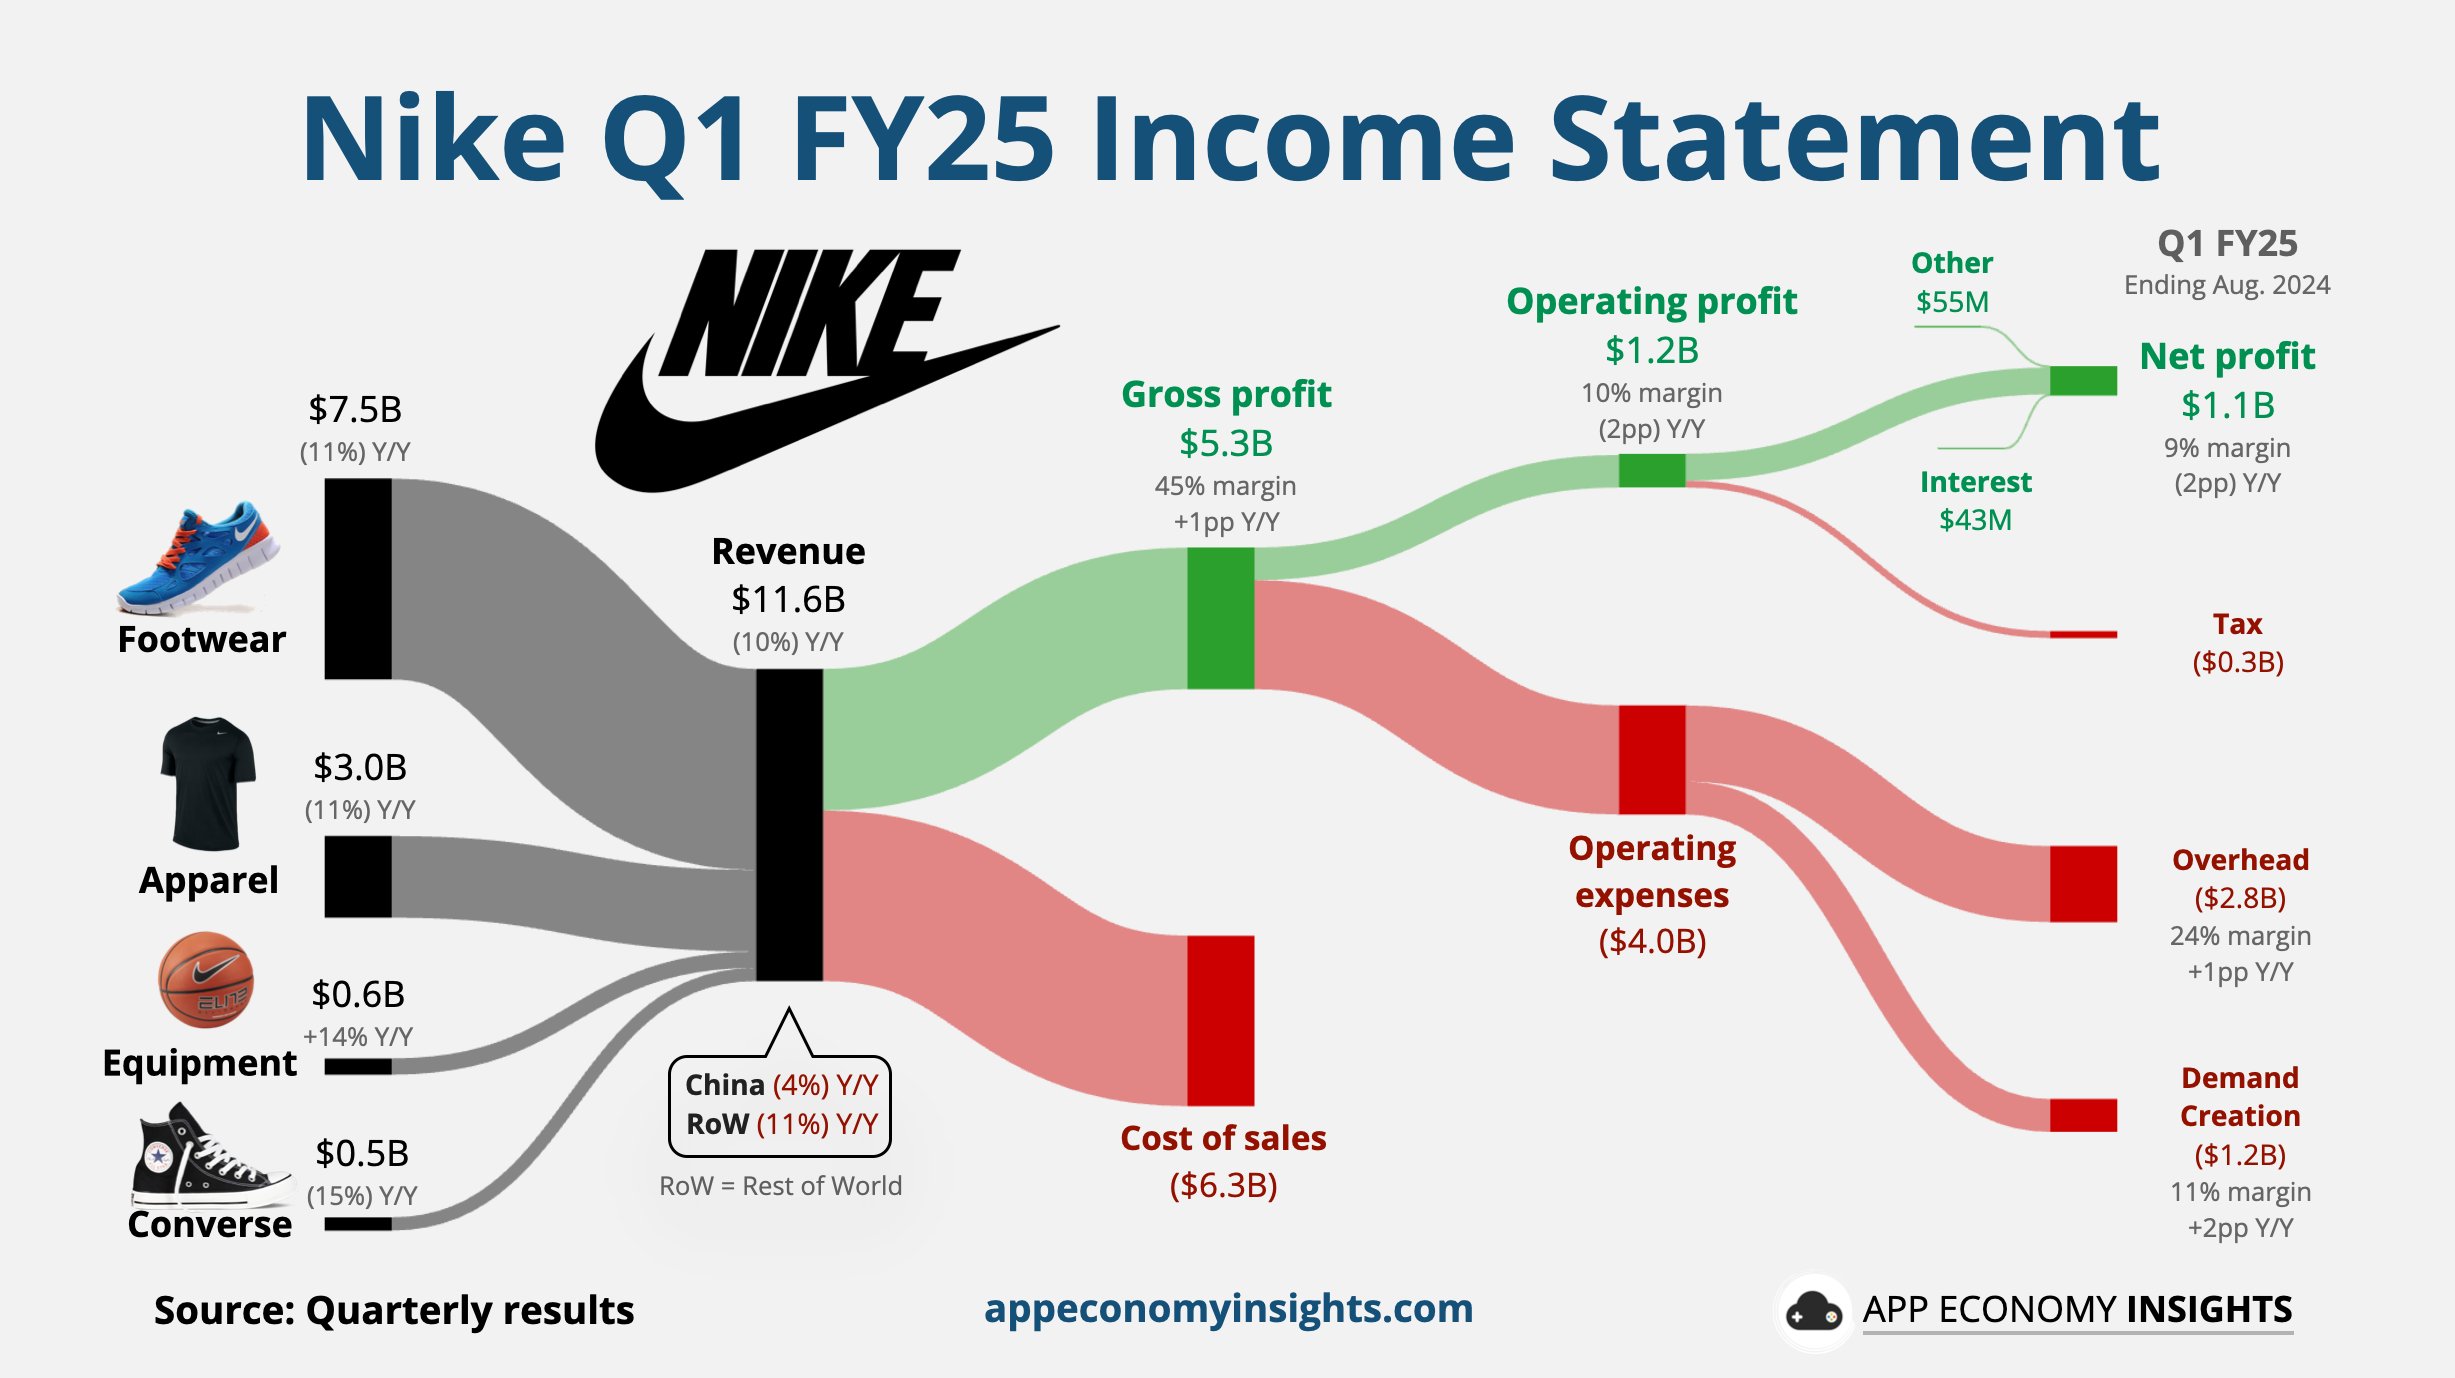
Nike’s first-quarter results declined in terms of revenue, Nike Direct sales, and wholesale sales, but then again, the gross margin grew, while earnings per share weakened significantly.
The company, however, sees positive signs in the areas of sports and innovation.
The Bloomberg article discusses how Nike, under its new CEO, needs the kind of changes comparable to Adidas’s success with the Samba and other retro shoes.
The new leader should follow the example of Adidas CEO Bjorn Gulden, who has successfully reacted to challenges proactively and stayed on top of new trends. Nike has faced declining sales and a loss of popularity in its key models, such as the Dunk, Air Force 1, and Air Jordan 1.
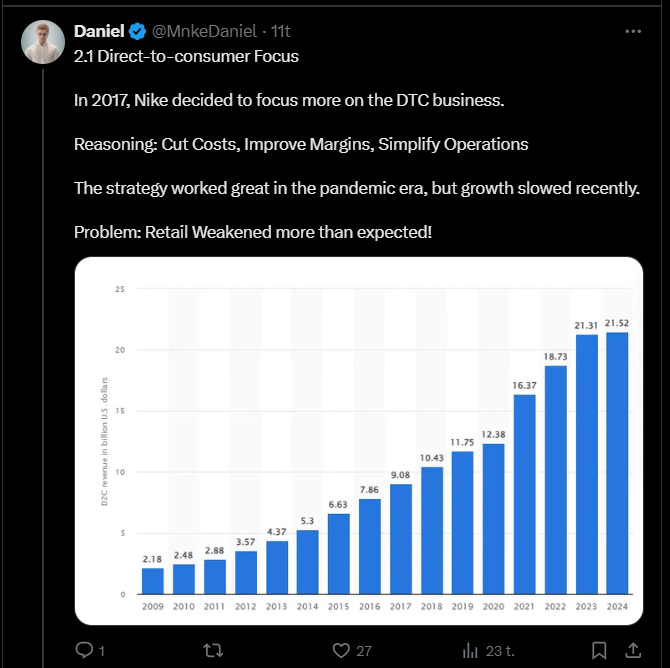
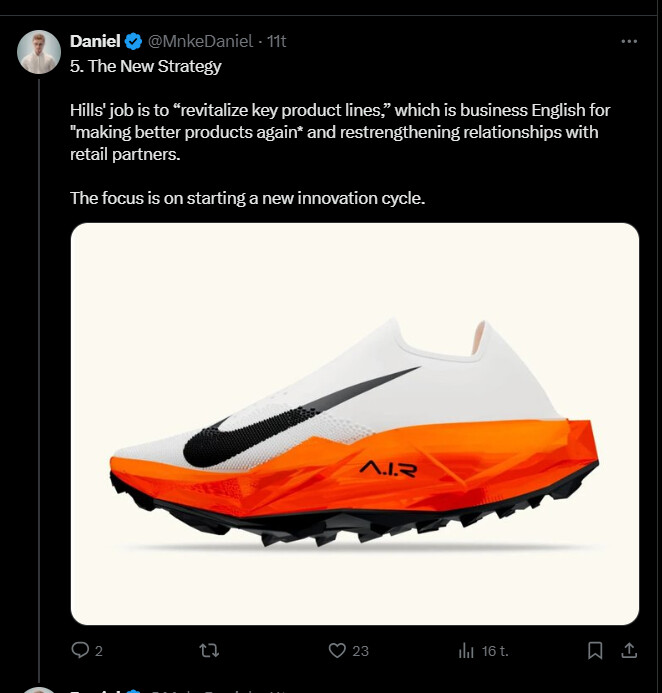
Hill is expected to reconnect Nike more closely with retailers and refresh the product lineup, but the process takes time. In previous years, the company struggled with retailers, for example, by focusing too much on its own “direct sales” (DTC).
When Gulden arrived at Adidas in January 2023, he found a company in crisis. Adidas had ended its lucrative, almost decade-long partnership with rapper Kanye West, now known as Ye, and was stuck with a closet full of old Yeezy sneakers. Consequently, he warned that Adidas could make up to a €700 million operating loss in 2023, much worse than expected. Though this was painful for investors, it cleared the decks, enabling Gulden to rebuild, which he has admirably. The shares have risen about 70% since.
Nike’s dear competitor is on a different track; Adidas raised its guidance for the third time this year and now estimates currency-neutral revenue to grow by about 10 percent this year, whereas the previous forecast was for high single-digit growth.
Adidas CEO Bjorn Gulden has helped reboot the German sportswear brand since its break-up with rapper Ye two years ago abruptly ended its lucrative Yeezy sneaker line.
Nike hasn’t been doing well, and it has been reflected in the stock price too, maybe even too much…? Perhaps, however, Nike should be able to renew/change itself.
These are the kinds of situations where you can get a quality company and one of the world’s best brands from the bargain bin.
Fashion changes over time. So far, Nike has always overcome its opponents sooner or later. It’s nothing new that new attractive brands and models appear on the market. Will these stand the test of time? So far, that hasn’t been the case; instead, people have returned to being Nike consumers.
In visibility and marketing, Nike is completely superior. This is the result of decades of brand-building work that continues—whatever the cost. As a product, shoes are very simple and replicable. It then becomes a question of who has the best visibility and appeal in the eyes of the consumer.
A weakness of the company is, of course, its strong dependence on sneaker sales, which account for about two-thirds of its revenue. It would certainly be better if cash flows came more evenly from other categories. Still, in my eyes, such a strong and stable brand should be priced at a premium, perhaps around P/E 30.
As the consumer market recovers, the company could well return to a growth path, even a strong one. Everyone can, of course, consider whether Hoka, Lululemon, or Adidas will be the long-term winner and market share taker. My belief is that Nike, under the leadership of a new CEO, will make a U-turn and pull revenue back into growth. Now might be the best buying opportunity in years.
The market can certainly price Nike at P/E 30, but I might not base my investment decision on that.
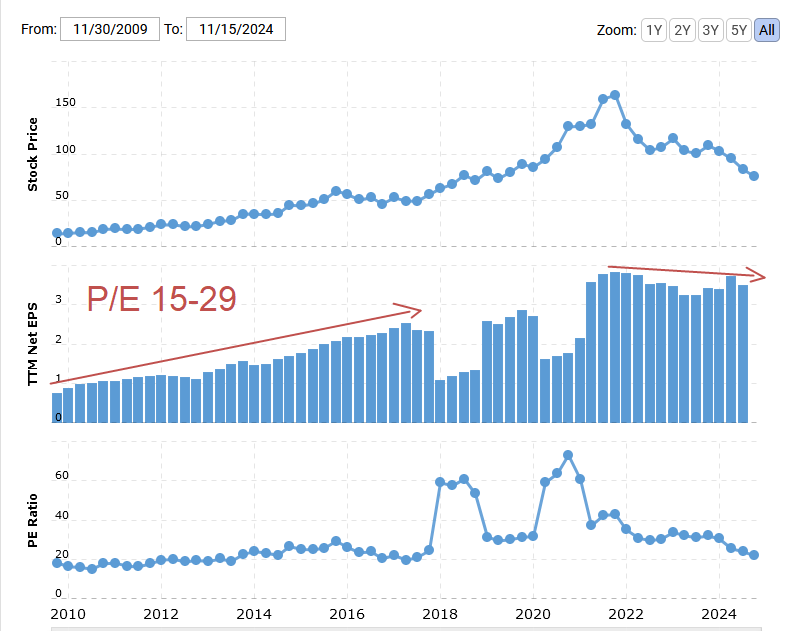
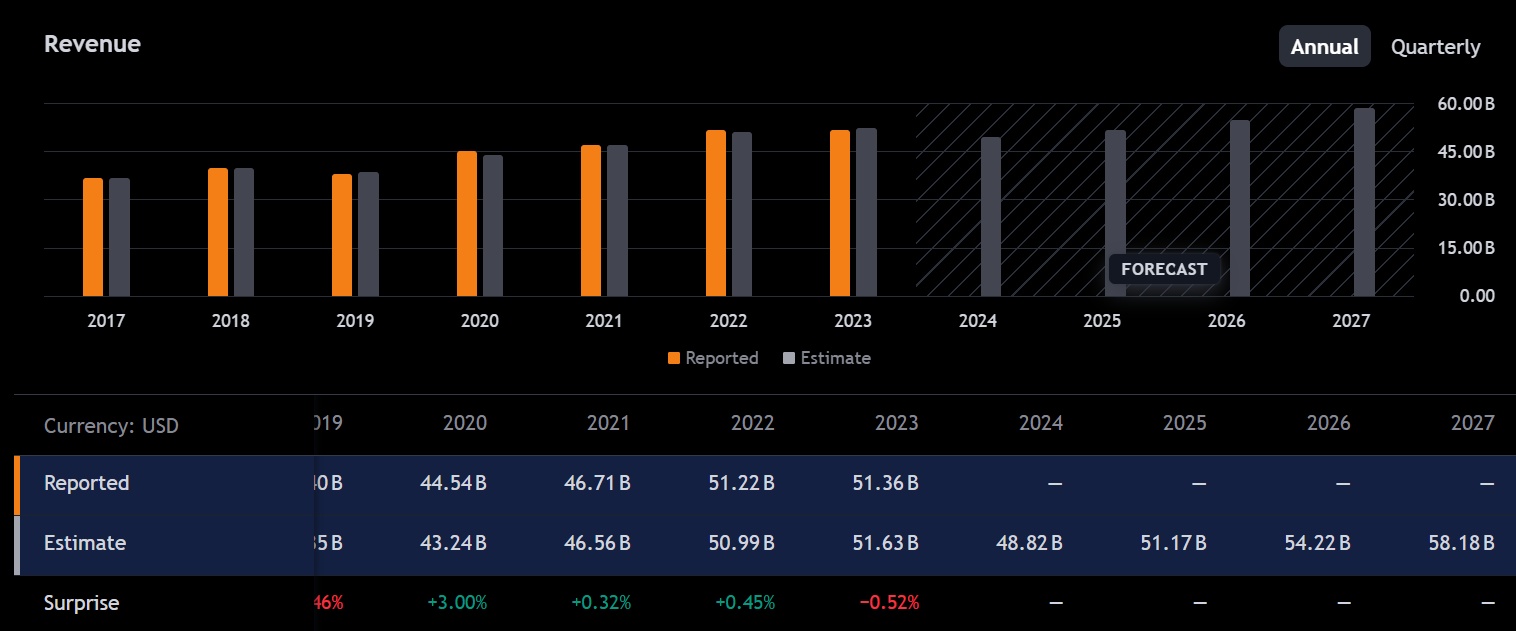
Between 2010 and 2017, Nike’s EPS grew very steadily, and the market priced this growth between P/E 15–29. In between, the P/E ratio rose to staggering figures a couple of times, but it seems the reason was a temporary drop in earnings. Due to COVID, the 2020 earnings dropped, and something apparently happened in 2018 as well.
From 2021 to 2024, Nike’s EPS has not grown; instead, the direction has been sideways, or perhaps some might even see a downward trend. Since Nike was valued at P/E 15–29 as a growth company, I don’t believe the market would price Nike above that range or even at the high end. Earnings would need to rise clearly for P/E 30 to be a sensible price in any way. Personally, I might be interested in Nike at around P/E 15–18.
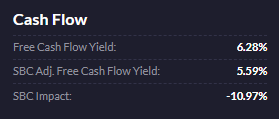
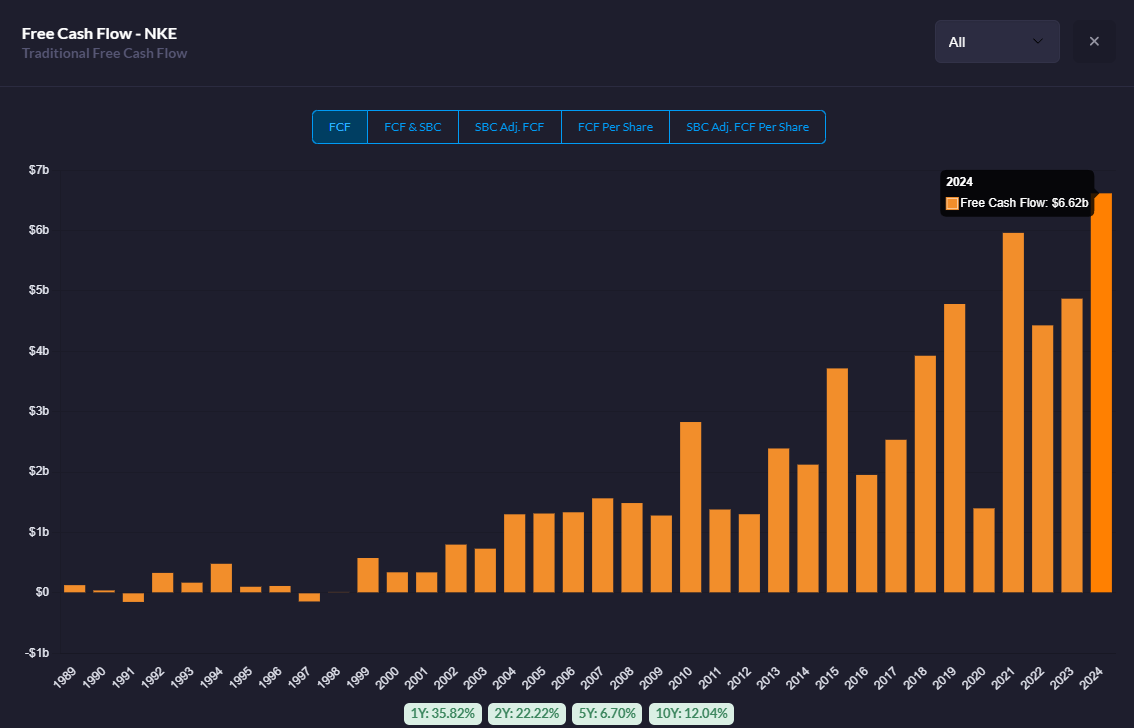
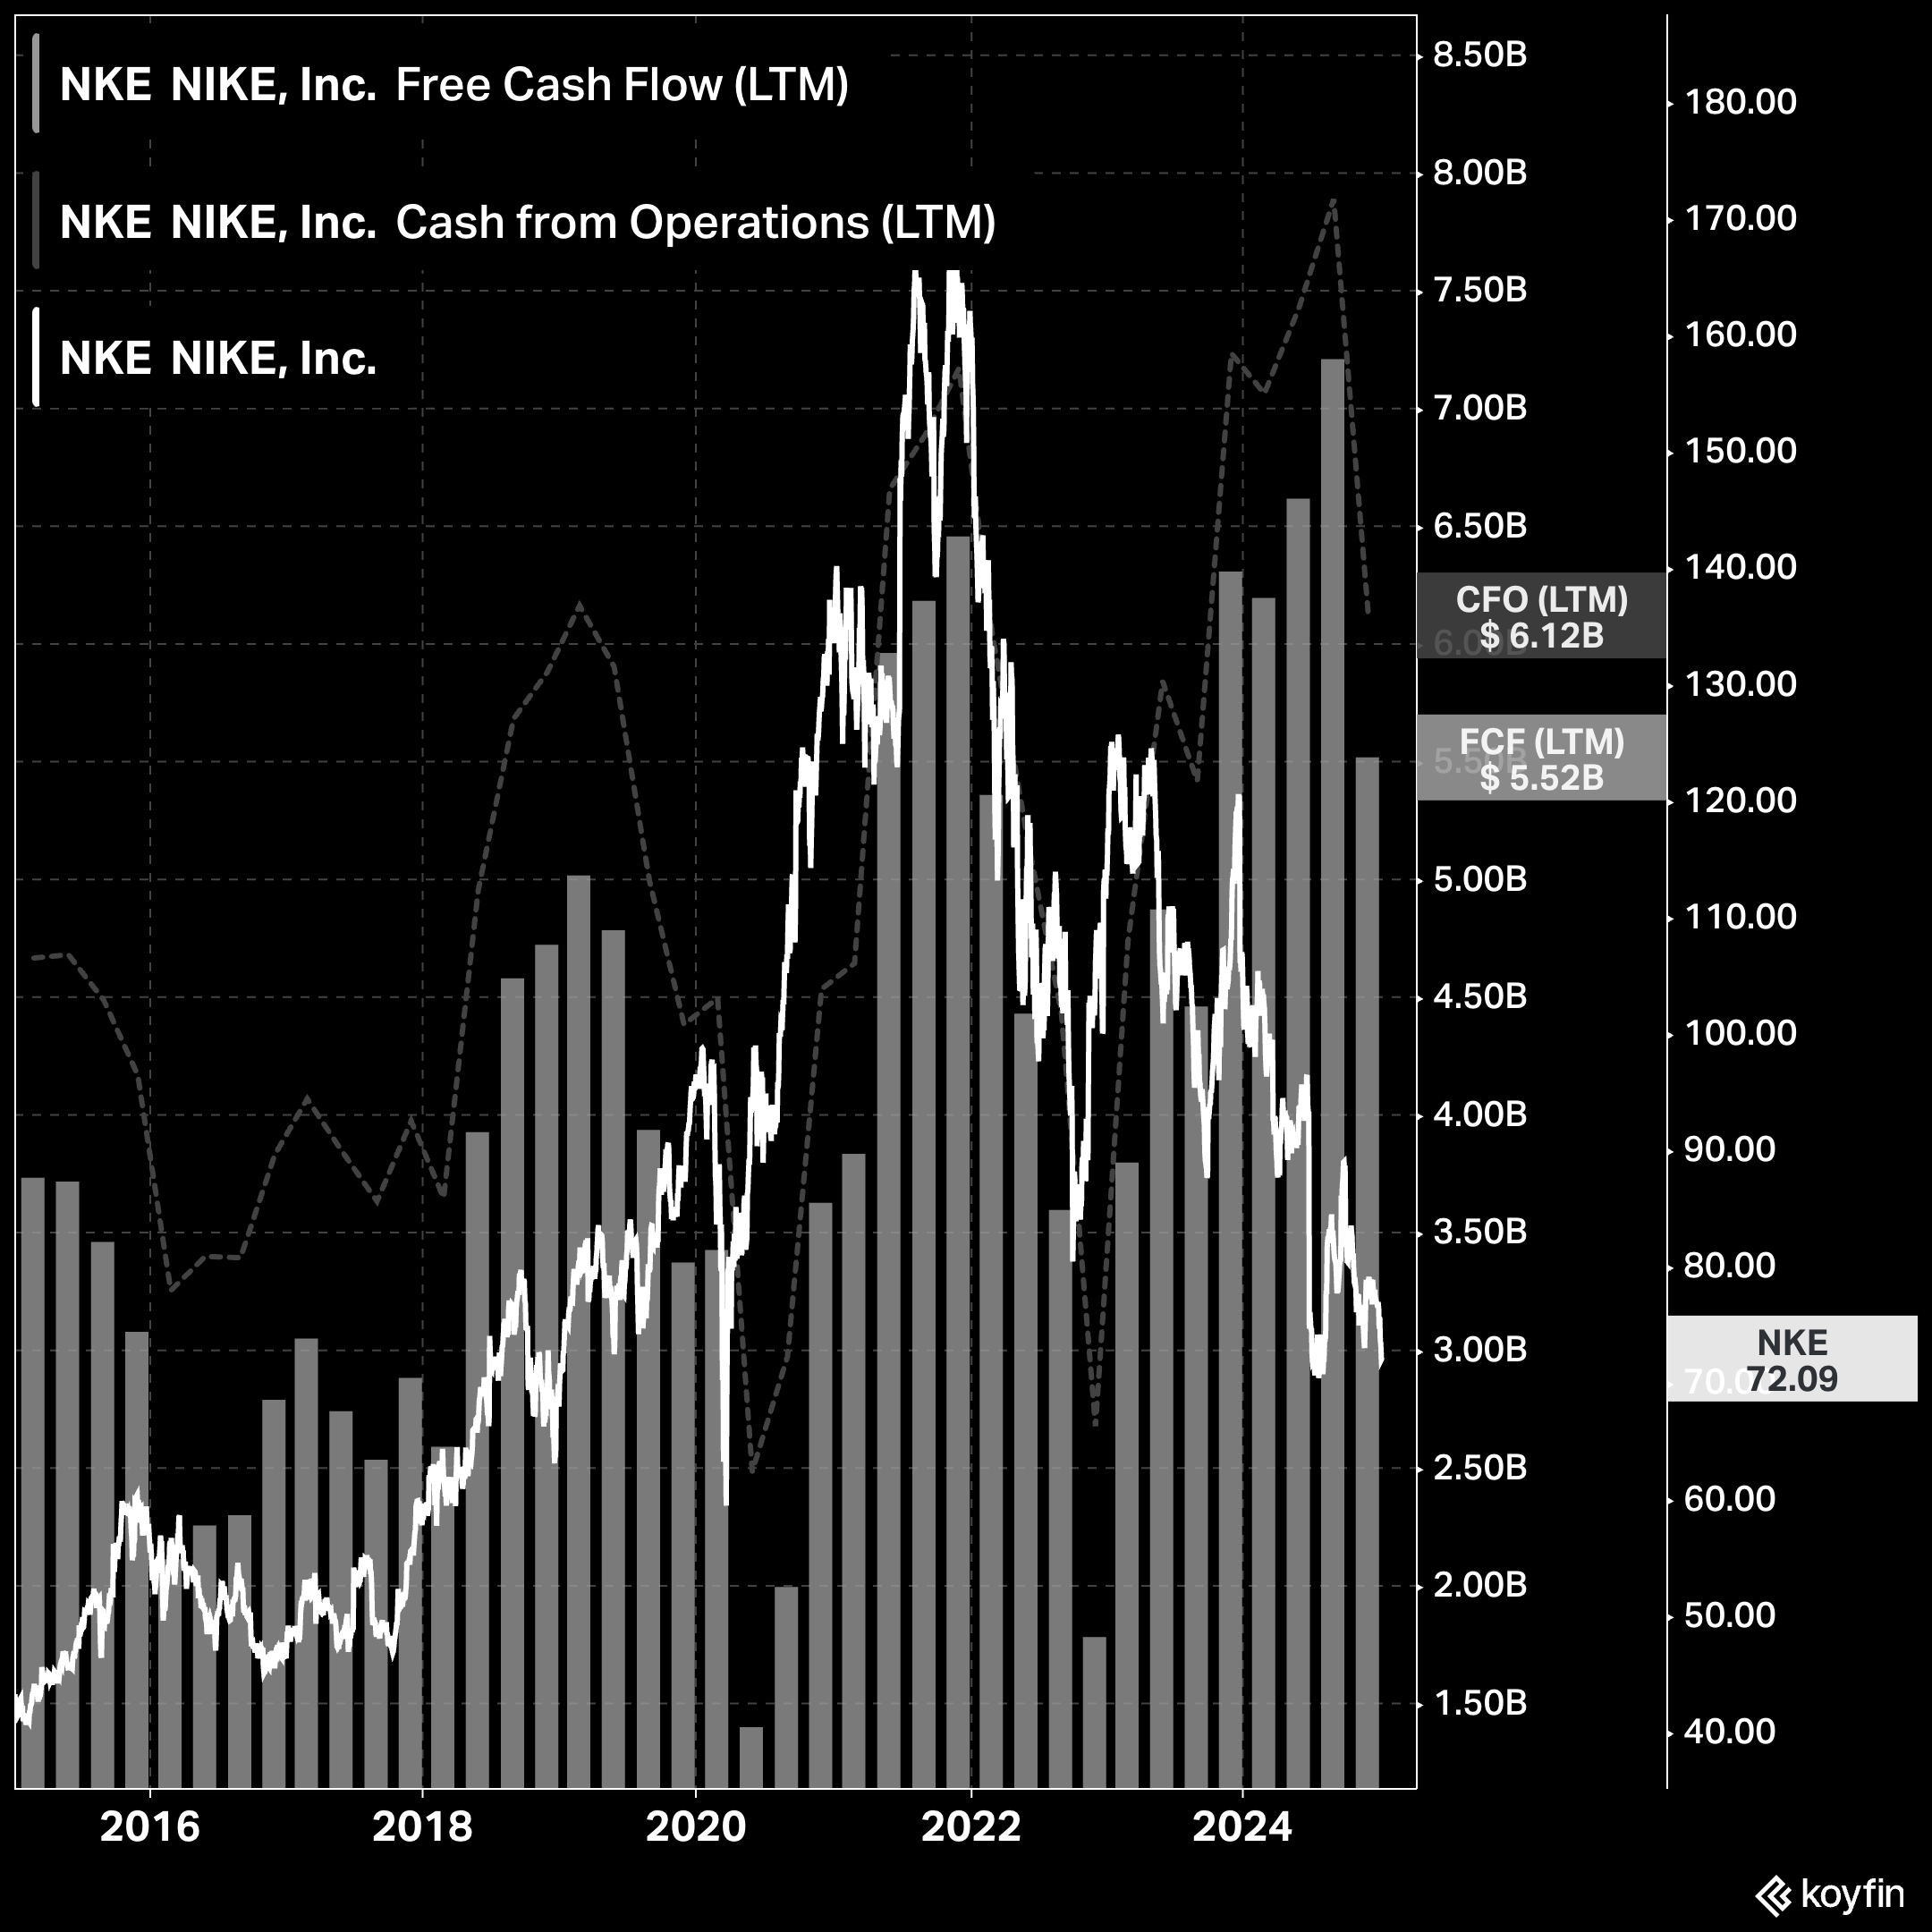
From a cash flow perspective, Nike looks quite cheap to me right now, as quality growth companies in the US are priced at a ~3% cash flow yield:
Of course, this is following a year when cash flow was strong:
If one were to use, for example, the 2022 cash flow, the cash flow yield would be around 3.8%. In my opinion, risks are currently elevated, and the market doesn’t like that guidance was withdrawn following the CEO change. But if you believe that Nike can turn the ship around and maintain/grow its market share and return to growth, then it is indeed available at a somewhat cheap price now. That’s the problem with these fashion companies—the business is cyclical, and what’s in fashion comes and goes. Of course, Nike has an exceptionally strong brand supporting it.
The tweeter considers Nike undervalued, additionally highlighting, among other things, the growing sales of the Jordan brand and the rise of the Athleisure category. He also points out that the company is involved in growing markets and continues to be innovative.
He also believes that the expansion of the Chinese market and e-commerce will boost Nike’s stock.
Nike just released its fresh quarterly results, which mostly met expectations.
Revenue declined slightly on a currency-neutral basis, which was due to weakening sales in all regions. Nike Direct and wholesale sales decreased, and gross margin also weakened due to rising costs. The CEO emphasized bringing sport back to the core of the business and growing long-term value.
The company plans to streamline its operations and adapt its strategy, aiming for stronger growth and market position. However, operating income remained relatively stable with tight cost control.
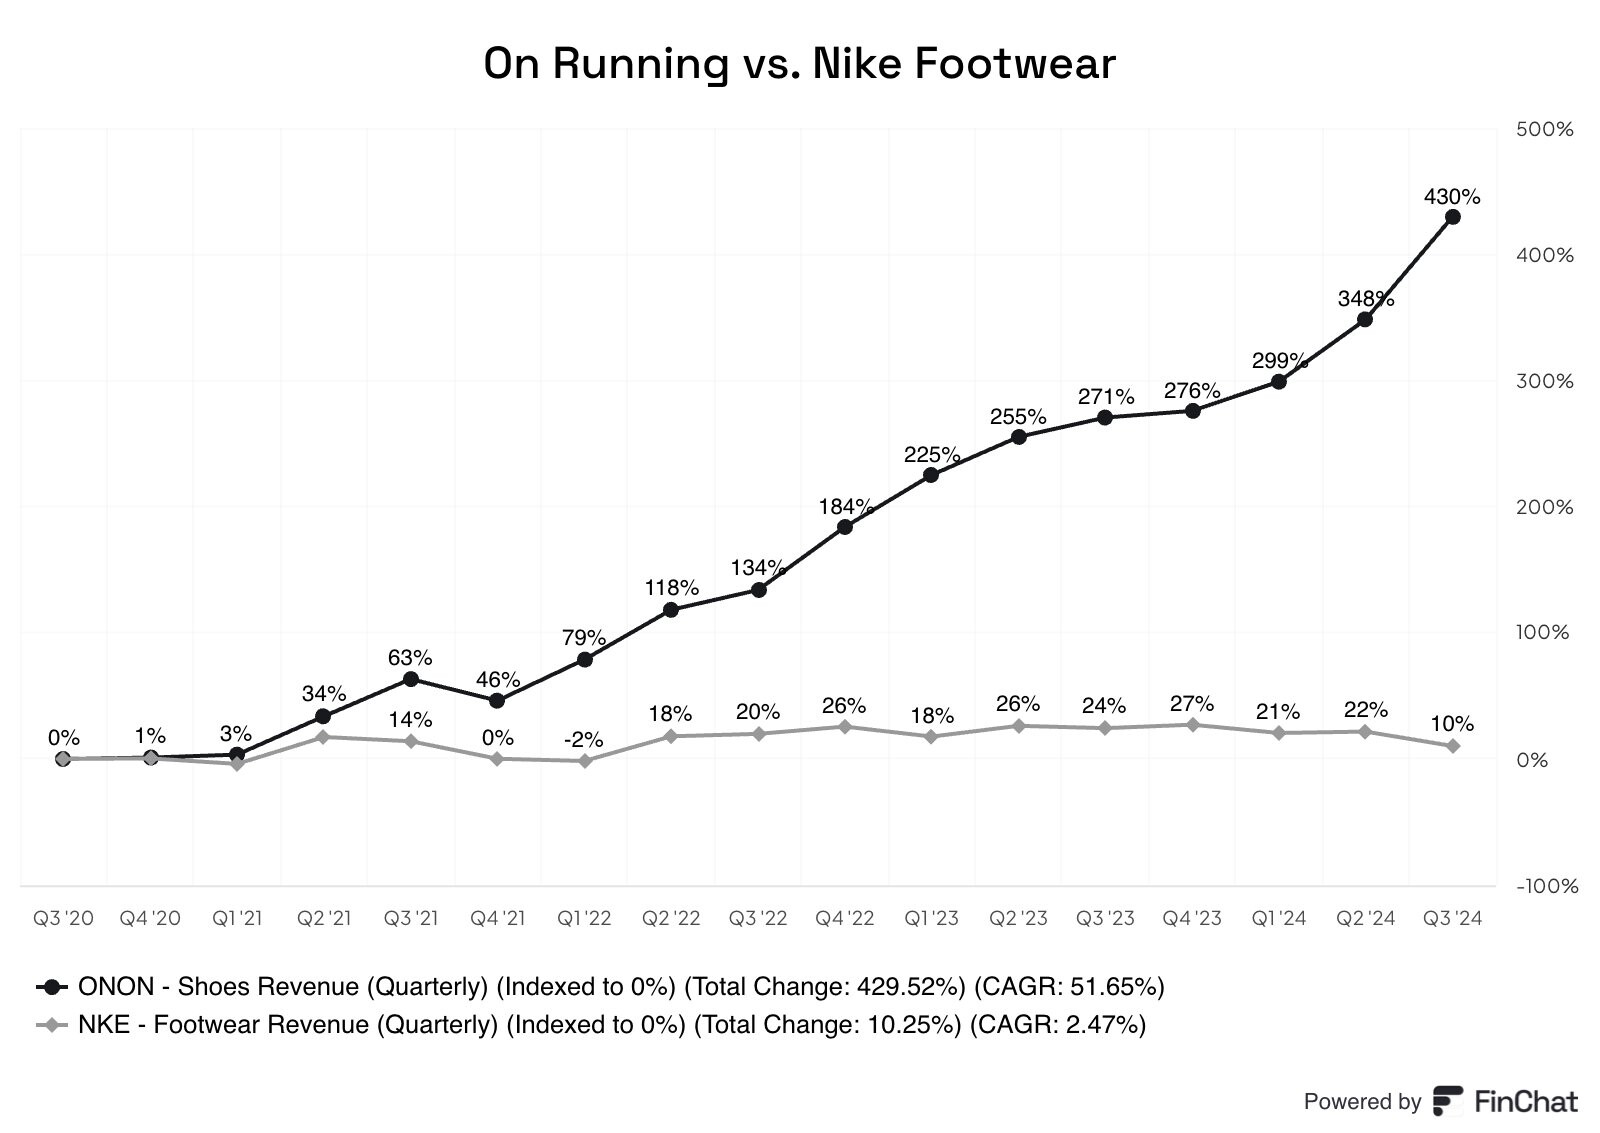
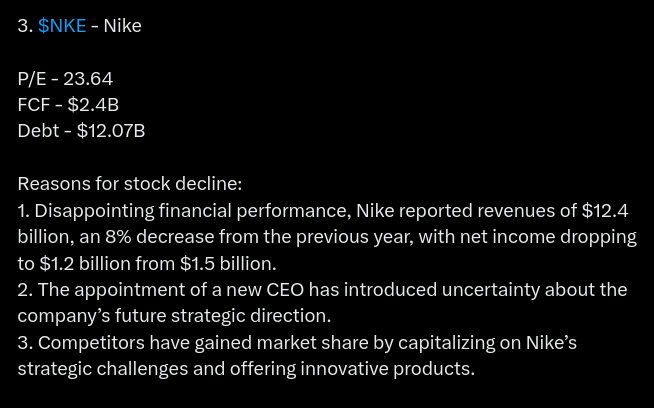
Here’s a quick look at Nike. In brief, the tweet’s main points are; the reasons for the stock’s decline are weak financial results, uncertainty brought by the new CEO, and increasing market shares of competitors. Positive aspects include expansion into China and India + strong cash flow and a global distribution network.
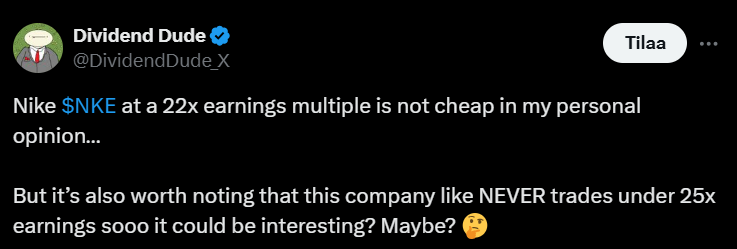
Nike’s P/E ratio has averaged 35 and is currently 21.
Nike’s stock has come down, and for good reason, of course, but Nike is Nike, so probably quite a few people are following this company and expecting some kind of turnaround/reversal.
Expansions into populous countries and perhaps potential “rationalizations” by new management might take the company in the right direction.
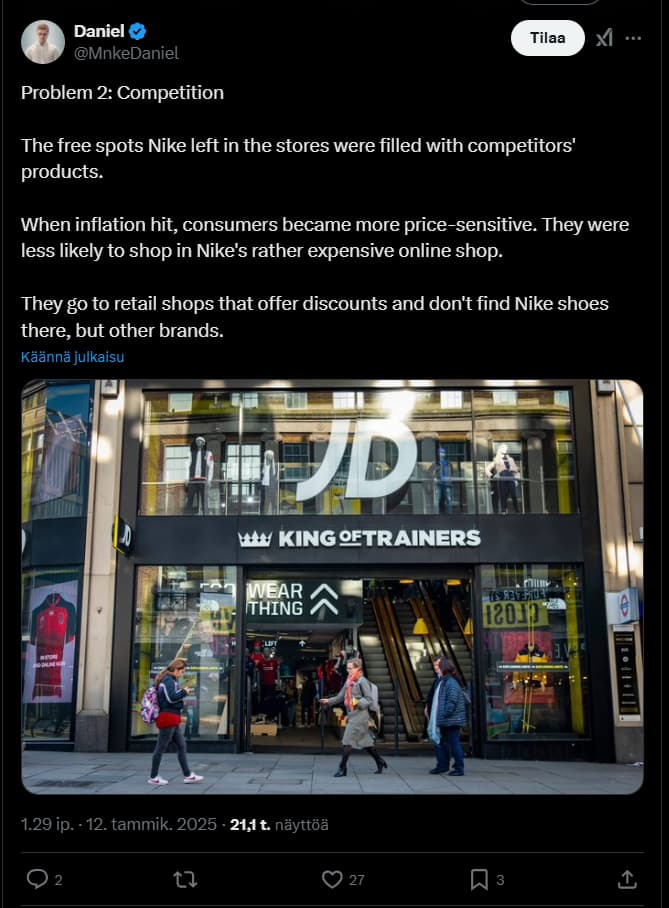
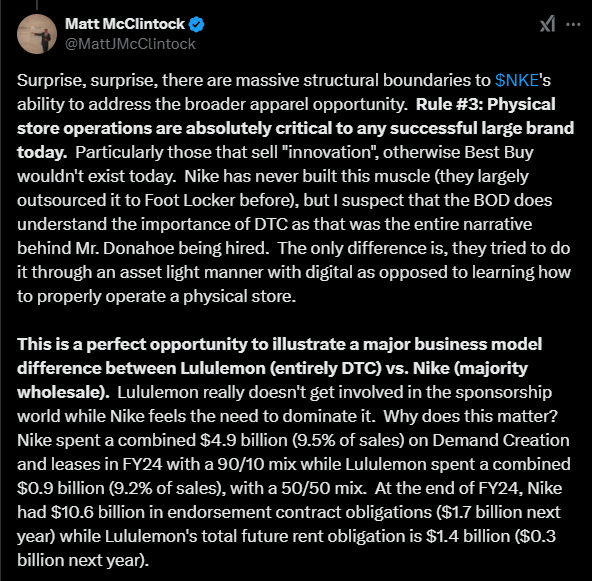
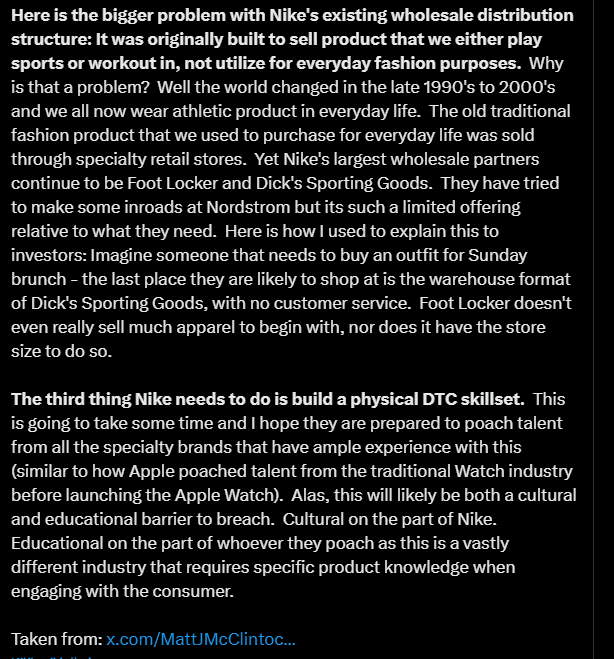
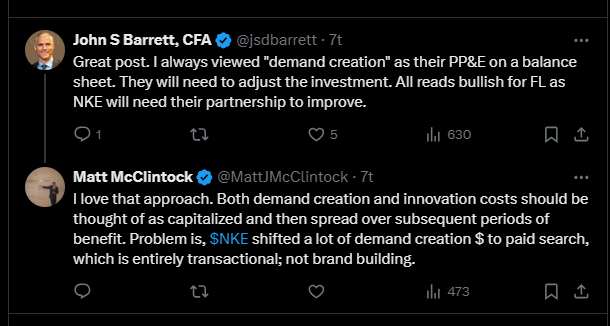
According to the tweet below, Nike will still face significant structural obstacles in expanding its apparel business. It is generally thought that physical stores are vital for large brands. Nike has traditionally outsourced this expertise to Foot Locker and has not developed its own store expertise.
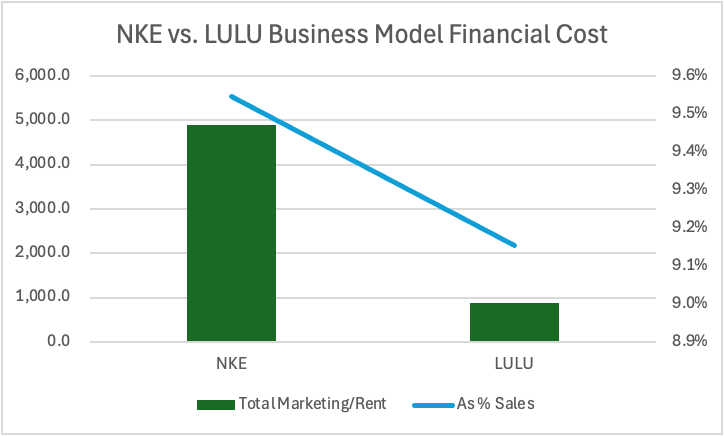
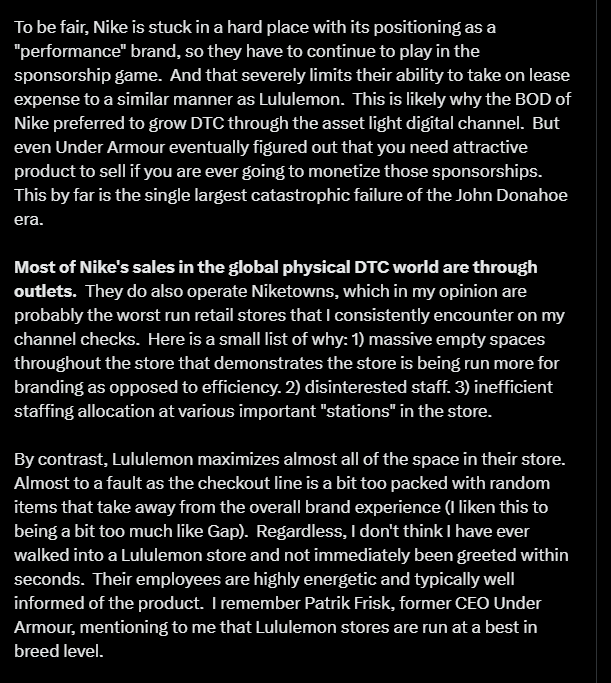
The DTC (Direct-to-Consumer) model is important, but Nike focused on a digital solution without a proper physical presence. Lululemon, which is entirely DTC-focused, uses its spaces effectively and invests in customer service, while Nike relies on wholesale distribution and sponsors. This limits their ability to lease physical spaces more broadly. The poor performance of Niketown stores generally reflects Nike’s challenges, such as inefficiency and lack of interest.
It should also be noted that Nike’s traditional wholesale network is built for sports and training apparel – not for everyday wear. According to this tweeter, this requires a strategic change. Nike needs expertise in developing a physical DTC model, which may require cultural and educational changes, as well as financial investments.
This tweeter has had tweets about the company and similar companies before, so it’s worth following if this company and “industry” interest you.

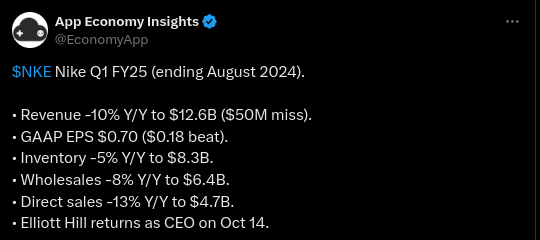
 gut feeling, I don’t think Nike is leaving the game in the near future either.