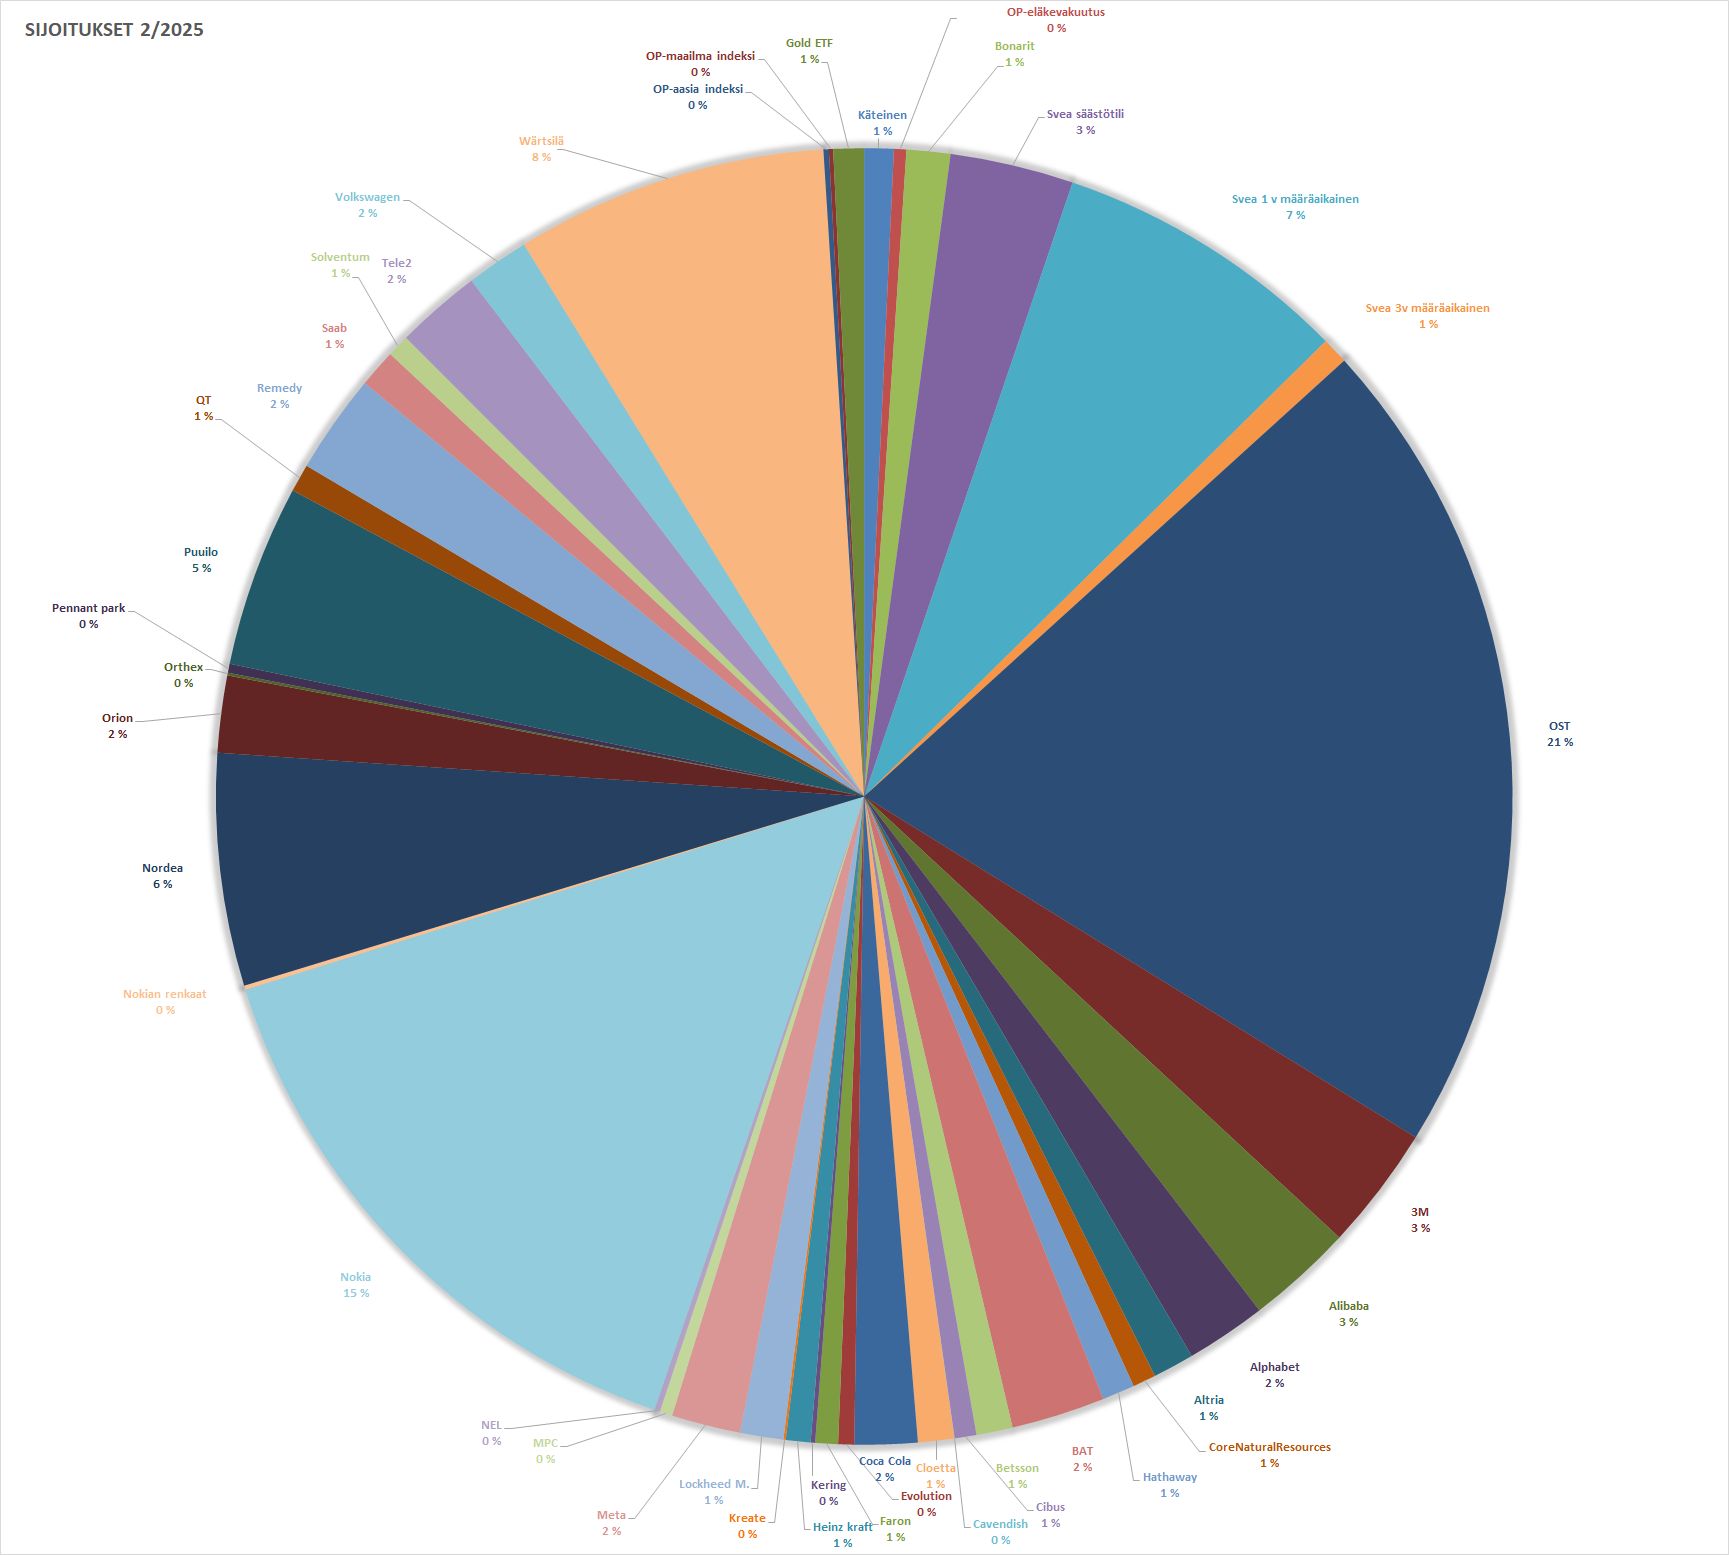
Equity Savings Account:
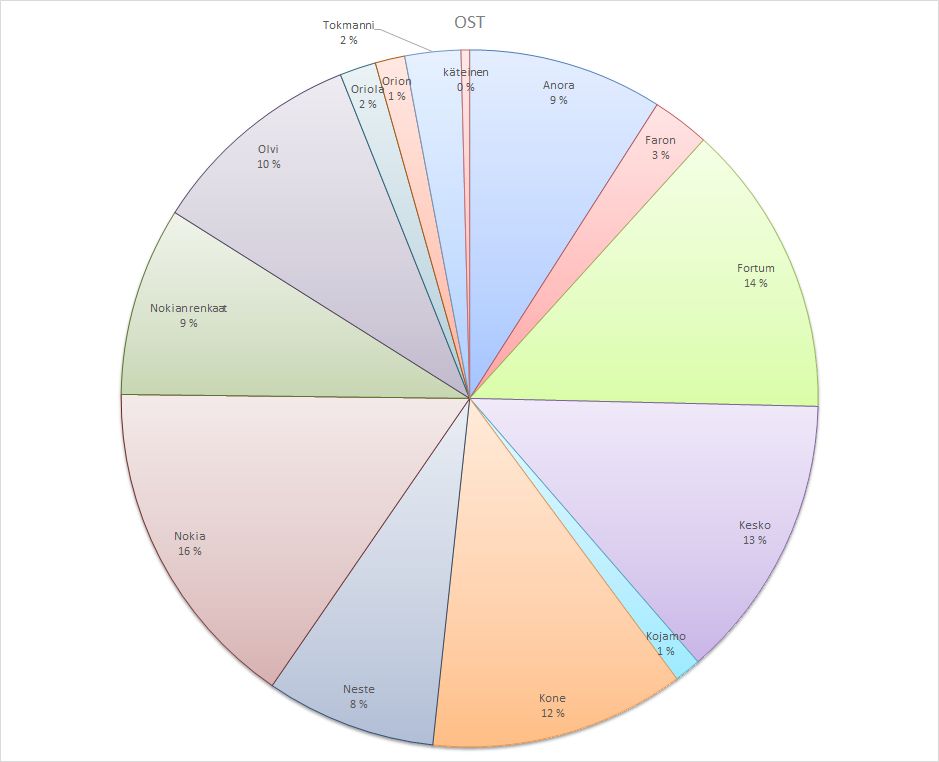
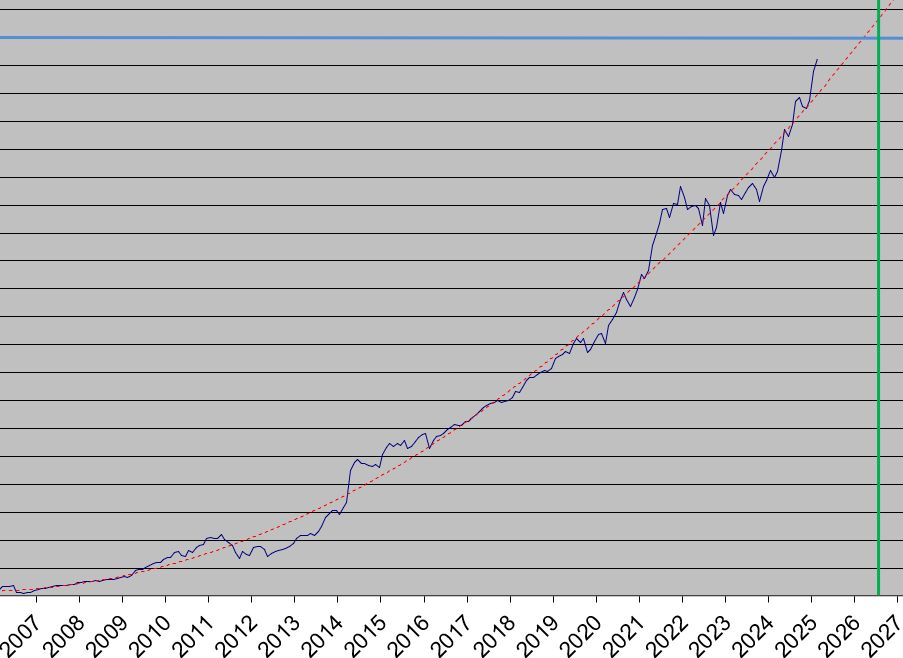
The target level for long-term saving and investing is already in sight. There have been good investments, and there have been bad investments along the way. And the journey continues… The intention is to retire from working life in the summer of 2026.
70 Likes
I did a little analysis of my portfolio again, outlining the sector and country distribution (for the equity portfolio, cash is not included here). I got these figures:
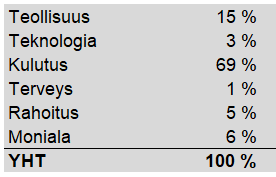
I have added “multi-sector” to the industries, because Berkshire doesn’t directly fit into any single sector.
Now I’m starting to have some thoughts regarding diversification, both geographically and (especially) by sector. Initially, I’ve considered adjusting diversification partly with funds, partly with direct stock investments, on a case-by-case basis as makes sense.
There is simply too much choice nowadays, it easily leads to the phenomenon of analysis paralysis, meaning it’s difficult to choose suitable investment targets from the endless supply.
8 Likes
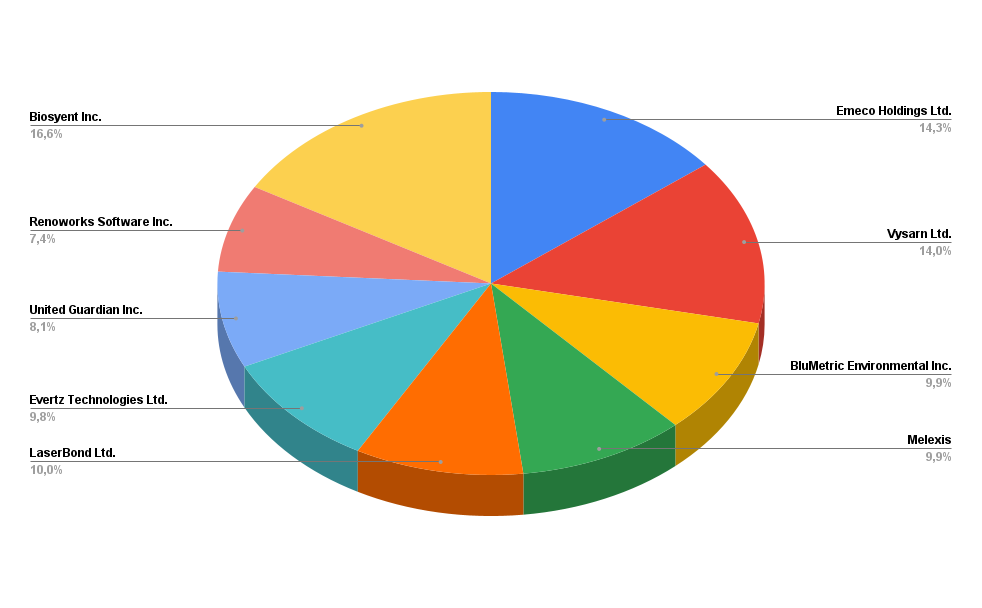
Mandatum portfolio with brief company introductions. The intention is to collect foreign companies (mainly small-caps) here, and to focus the Nordnet portfolio on Finland, Sweden, ETFs, and funds in the future, so that Superluotto (Super Credit) remains at gold level when needed.
 Emeco Holdings Ltd. provides heavy earthmoving equipment rental solutions and maintenance services to mining companies and contractors in Australia. Their services include, among other things, the rental of trucks, excavators, and bulldozers, as well as the refurbishment of machinery and parts.
Vysarn Ltd. offers comprehensive water management and infrastructure services, particularly for the mining, industrial, and municipal sectors. The company has expanded its operations by providing increasingly diverse solutions, such as water distribution, drilling, and maintenance services.
LaserBond Ltd. specializes in surface repair and protection technologies, particularly laser cladding techniques to extend the lifespan of industrial components.
 Melexis is a semiconductor company that designs and manufactures sensors and microchips primarily for the automotive industry.
 United-Guardian Inc. develops and manufactures specialty chemicals for the cosmetics, pharmaceutical, and industrial sectors, among others.
 BluMetric Environmental Inc. is an environmental company that provides solutions for water treatment, environmental consulting, and waste management.
Evertz Technologies Ltd. offers hardware and software solutions for digital media and broadcasting.
Renoworks Software Inc. provides visualization software for the construction and renovation industry, helping customers design and visualize their projects.
BioSyent Inc. is a pharmaceutical company focused on the development and marketing of innovative and specialized medicines and healthcare products.
33 Likes
A few thoughts on my investments. Last year (2024) I cleaned up my portfolio quite thoroughly, selling off the ‘eternal promises’ and also profitable stocks that had risen nicely but had been stagnating for a long time. Among the growth companies I owned, Incap and Revenio have been good; I managed to sell them opportunely and at the right time. Other purchases in growth companies have been dismal, and I will not buy them again in the future, as my skills are not sufficient to evaluate them.
Now all investments in my AOT are profitable; in my OST, Consti is the only losing stock (approx. -10%).
After last year’s “cleanup,” the balance of sales was slightly profitable (+1000 euros). In previous years, I have also realized profits to supplement my small pension.
So I have returned to a more traditional investment path: diversification, investing abroad primarily through investment funds, companies’ solvency, dividend-paying ability, etc…
14 Likes
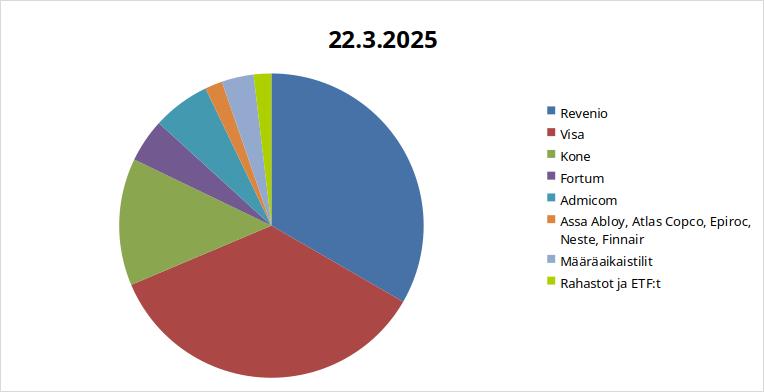
I have been investing with my current philosophy for almost 10 years now. I would dare to say I am a long-term investor; I don’t make changes for the sake of changing. 80% of the portfolio has remained unchanged for at least 8 years, and other assets have been added with varying success, and sometimes sold. Regarding major holdings, the idea from the beginning was to avoid political risk, as it is impossible to anticipate over the time horizon I consider for investments. A lot has happened during this time. The worst pandemic in a hundred years, I almost forgot to react to what happened in the stock markets. That dip passed so quickly. A large-scale war in Europe after an 80-year break. It didn’t cause a need to make any sales with my then-holdings. Then came this circus in January, and since then, I haven’t felt comfortable anymore. Alarm bells in the back of my head started warning about quiet signals.
Gradually, funds and ETFs started to be sold. All cases containing at least 40% US companies were sold to reduce risk. Accenture and Adobe too, remnants of former larger holdings. Additionally, I stopped buying the aforementioned funds and all US stocks. In their place, I bought a percentage of rare metals ETF as a spice.
Today, I calculated the origin of the revenue of the companies in my portfolio; approximately 35% comes from the USA. Fortunately, not a higher number, quite suitable. I wouldn’t want to sell Visa or Revenio unless absolutely necessary. Neither is prominent in the news, and the probability of becoming targets of politicians’ (of any party) or the general public’s passions is small.
Term deposits, savings for the next couple of years, and dividends will likely go into Atlas Copco purchases, depending a bit on what kind of storm is coming in the stock markets. With it, you can sleep peacefully at night, regardless of the social media frenzy.
43 Likes
Invested for 3.5 years. Here is the portfolio currently.
Enento  35.85% The largest weight in the portfolio and will remain the largest. I believe a takeover bid will come for the entire company.
Investor AB  17.17% There are no funds in the portfolio, so this serves as a very good “fund”.
Optomed 11.91% This year is very important, a ‘make or break’ case.
Faron 11.52% Important year. Partner deal or a takeover bid for the entire company.
Neste 7.68% Mistake purchase. For the long-term portfolio..
Ethereum 6.87%
XRP 4.2%
Tecnotree 3.22% The biggest fiasco in the portfolio. This will remain in the portfolio until the company is bought off the stock exchange.
Unusual Machines  1.57% Interesting American drone company. A growth company with great potential. Trump’s son owns shares and is involved in the company’s operations. That is either a positive or a negative thing..
Portfolio size 28,000e
Funds should be added in the future..
29 Likes
Why stick to mistakes? I myself also held onto Neste for far too long, but then finally switched it to better horses a month or two ago(?), and which have already returned some of the losses, and which, according to my own estimate, will also perform better in the future.
16 Likes
The last portfolio company has also published its quarterly report, and it’s time to take a look at the portfolio again  . This transition period between Puuilo’s and Admicom’s reports is very subtle, but a good moment to reflect on the previous quarter.
Portfolio building has continued; I think I wrote in the last quarterly report how my interest, as a sum of many things, has shifted from domestic companies towards international ones. I seem to be an unwilling contrarian, as the Helsinki Stock Exchange has been strong at the beginning of the year, and other markets… well, they haven’t developed as strongly  . When I started selling a significant portion of my Finnish investments last year, I took a conscious risk that I would sell cheap companies and buy expensive ones. This felt foolish, but I’ve noticed that sometimes that slightly uncomfortable feeling yields good results in the long run. This is, of course, entirely subjective, but for example, buying falling knives has previously given me a good feeling because I get something cheaper than before. On the other hand, buying Lifco at 200 SEK felt really bad because the price seemed expensive. If I had the same opportunity again, I would buy with both hands. Perhaps that’s why I try to resist this good feeling that buying falling knives gives me.
Falling knives are, of course, a tricky subject, because everything depends on your investment horizon; if your trust in the company remains and you can sit on your hands through the rollercoaster, you might make good deals in the long run. But in the short term, you’ll likely only face pain and discomfort. I’m not sure if I can endure that feeling. A falling knife is often also a signal that the market doesn’t trust the company’s future. I’ve learned enough humility from past mistakes to know that the market is often right. If you go contrarian and buy a falling knife, you need to have a strong understanding of what the market might be misunderstanding about the company. Buying on the premise that “the market is stupid” leads to poor results in my experience. Therefore, I’ve started avoiding purchases that feel intuitively good. On the other hand, I’ve focused on those that initially feel a bit unpleasant because the price might be a bit tight. “You pay peanuts, you get monkeys” has often been on my mind. Let’s see where this leads.
Reversal to the mean is indeed a known phenomenon in the market, and it seems to be happening now, Helsinki Stock Exchange vs. NASDAQ. However, I wonder what this means in the long run. Companies with strong competitive advantages are still rare on our domestic stock exchange, and many of them are unfortunately in the US. The fact that capital is flowing back to Europe doesn’t change this reality; rather, rotation changes valuations.
Last year, when I wanted to make changes to my portfolio, the underlying idea was to raise the quality of the portfolio companies, and unfortunately, I couldn’t find 25 companies in Finland that would meet my criteria. Therefore, I had to turn my attention to international markets. Researching foreign companies has been eye-opening because international stock exchanges offer companies with truly amazing business models. In my opinion, one shouldn’t buy these blindly either, but I think it says something that certain companies actively work to create an image of fierce competition in their own market so as not to fall under regulatory scrutiny for too strong a competitive advantage. At the same time, mediocre companies try their best to look as good as possible in the eyes of investors.
Portfolio
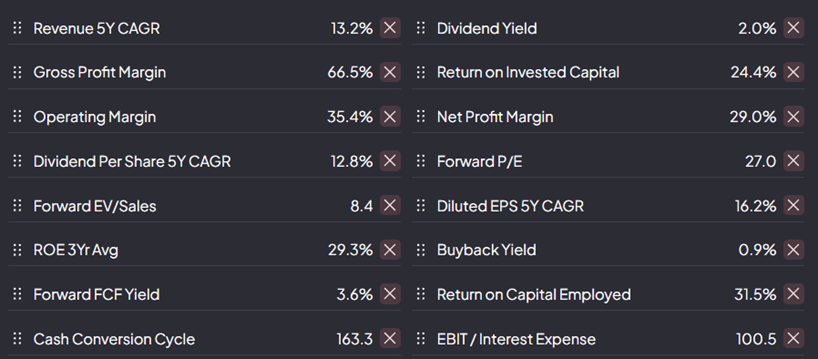
If my portfolio were a single company, its revenue would have grown by 13.2% CAGR over the last five years. For the past year: gross margin 66.5%, EBIT 35.4%, ROIC 24.4%. EPS has grown by 16.2% CAGR over the previous five years. I am satisfied with these figures. Looking back, my companies generally have a competitive advantage that has generated strong returns on capital. Of course, for me to benefit from this, future investments must perform equally well, and competitive advantages must remain strong. Otherwise, I will witness the quality → trash effect, which does significant damage to a portfolio.
Valuation is a bit tight, NTM P/E 27 and NTM FCF 3.6%, but for several companies, staring at the P/E is not particularly meaningful; for example, Dynavox’s EPS has tripled in four years.

The portfolio contains the following companies, from largest to smallest holding:
Investor B, Admicom, Marimekko, Nordea, Revenio, Puuilo, MSCI, Mastercard, Alphabet, Harvia, Chemometec, Visa, Medistim, Dynavox, Copart, Fortnox, Lifco, Vaisala, Berkshire Hathaway, Idexx, Medpace, Moody´s and Shopify.
A total of 23 companies; there would still be room for two more, and six companies are on the watchlist.
Significant Finnish positions still remain in the portfolio because we have a selected group of companies that interest me here in Finland. There are also a few exceptions in the portfolio that don’t quite fit the strategy I’ve outlined. Nordea is a great company, but it’s difficult to find a competitive advantage in the banking sector. However, I appreciate the dividend paid by Nordea, and the company has done excellent work in recent years. Investor Ab is another company whose competitive advantage may not be the strongest, but rather stems from its ability to allocate capital. However, I will highlight the following image from Investor’s 2024 annual report.

The company’s stock has generated 17.3% p.a. over 20 years. I can already state that if I were a rational investor, I would give up stock picking and just buy Investor. I will hardly ever beat that track record. This is why the company is still my largest position.
As for the other companies, I believe that in the long run, they will be able to grow into their higher valuations and create value for me. I don’t believe I am an exceptionally skilled stock picker, which is why there are so many companies in the portfolio. Some companies will not succeed as expected, I have probably paid too much for some, and in some cases, authorities might intervene or break up the company. Therefore, I think it’s good to keep a sufficiently large number of companies in the portfolio.

International diversification has improved from the old 100% Finland situation. I still believe that my best competitive advantage as an investor is in Nordic small-cap companies, which is why their weight in the portfolio is significant. On the other hand, I am fascinated by companies with strong competitive advantages, such as Copart. Thus, I have come to the conclusion that these styles and my interests should be combined.
Finally, I want to highlight a few bright spots in the portfolio. Namely, Marimekko, familiar to many, and the less familiar Norwegian Medistim.
Regarding Marimekko, I have been waiting for a turnaround in the Home category, as it has a significant impact on the company’s revenue. Now, in my own papers, it appears that this product line grew year-on-year for the first time in three years, after a small corona hangover.

The company also continues to invest in the right direction. Last year, 2 new stores were opened net in Asia. The goal for next year is to open 10-15 new stores, a large part of which will be in Asia, so it feels like a significant addition.
 Medistim is a Norwegian med-tech company. The company has a strong position in a niche market. The company manufactures blood flow measurement devices and vascular imaging devices for cardiac and vascular surgeries. The company has approximately 37% market share. Competitors have 8%. 55% of surgeries are still performed by manually measuring blood flow, i.e., by feel. The company primarily has two types of revenue: devices and recurring sales of sensors. Recurring sales accounted for approximately 73% in 2024. Depending on the type, the device sensors can be used approximately 50 or 100 times, after which they must be replaced. Recurring business certainly sounds great, but a high proportion can also indicate that not enough devices are being sold. Of course, each device sold increases potential sensor sales. The company has been very profitable and has grown steadily, but in recent years, profitability has declined from its peak years. The company has invested in new products and expanded its organization to support direct sales. This has resulted in increased costs, but not yet in profits. However, the market has shown small signs of recovery for higher-margin products, and the company’s newest device version is ready for sale. Certain efficiency measures have also been implemented. This was pleasing to note in the last quarter. Am I now sure about a turnaround? Absolutely not; this could just be one slightly better quarter after many declining ones. In any case, positive signals have been received as EBIT% improved in Q4-24 vs Q4-23. It is therefore interesting to continue owning the company, and we will see if profitability continues to improve next quarter.
As we can see, the company has continued to grow, and the gross margin consistently hovers near 80%. However, costs have grown faster than revenue, which has unfortunately led to a decline in operating profit margin in recent years. At the FY level, profitability is still on a strong downward trend.

I could have chatted on longer, but perhaps it’s good to end the portfolio review here  . The intention is to continue hunting for companies in 2025 as well. I strongly hope that the opening of the IPO window will bring more interesting companies to the domestic stock exchange. However, market turbulence provides an opportunity to buy exceptionally interesting companies internationally. Happy spring to all!
55 Likes
| Company | Share |
|---|---|
| Fairfax Financial | 28.6 % |
| Valeura Energy | 18.4 % |
| Secure Waste Infrastructure | 8.5 % |
| AerCap | 7.9 % |
| International General Insurance | 6.6 % |
| NewtekOne | 3.9 % |
| Philip Morris | 2.4 % |
| Investor B | 1.8 % |
| Exor | 1.7 % |
| - | - |
| Cash | 20.0 % |
| Total | 100.0 % |
YTD +1.59 %
Q1/2025 is pretty much in the books. The performance has been quite two-sided: the operational performance of the companies has been excellent across the board and stock performance at least satisfactory, but currencies have done significant damage as both dollar currencies weakened against the euro. Furthermore, the slightly volatile political climate in the US hasn’t exactly helped, but this probably comes as no surprise to anyone. I’m quite satisfied with the results so far, but additional returns should be achieved by the end of the year.
Sales, Q1:
- Linamar/Nelnet: are exiting the portfolio for now, because 1) there was profit to be realized after the previous report, and 2) the actions of the US administration hit too close to the bottom lines of these companies to hold them with peace of mind. Nelnet’s Q4 was already better than the utterly dismal Q3, so it might return to the portfolio at a more suitable time. Linamar is spitting out incredible free cash flow and trading around its tangible book value, so if a tariff panic drives the stock even lower from current levels, the risk-reward ratio will start to lean towards ridiculous.
- Converge: I posted about this elsewhere on the forum, so let’s also mention the pleasant surprise of the quarter. The rather mediocre IT services company I bought in January was acquired a month later at a 55% premium off the stock exchange, and although the purchase price remained modest, I accept my quick profit and continue my search.
Brief comments on portfolio companies:
Fairfax: Q4 was very strong, and the growth pieces are still in place. It trades at about 8x 2025e earnings and is my best-managed portfolio company, so I added during the Q1 dip.
Valeura: It has fluctuated with Brent oil movements, but buybacks and positive reserve reports have lifted the share price nicely. By the end of Q1, the balance sheet should show net cash equal to half of the company’s valuation. The company’s stated NAV per share is approaching 14 CAD, with the share price around 8.4. I increased the position early in the year; now, in terms of size, we are already at the upper limits.
Secure: A small addition has been made compared to the previous one, but otherwise, there’s not much new under the Albertan sun. Buybacks are being done aggressively, and new acquisition targets were found in the metal recycling business. It still seems like a quality company but doesn’t get the corresponding valuation.
AerCap: When discussing AerCap, one must prioritize capital allocation, so let’s state the most important thing: in Q4, the company sold its aircraft at 2.6x book value and used the proceeds to buy back its own shares at 1.1x book value. Gus Kelly, ladies and gentlemen. AerCap also warned during the quarter that tariffs will further disrupt already tangled aircraft production chains, so AerCap’s golden age seems set to continue. I added twice in Q1; the valuation level is a bit over 7x 2025e EPS.
IGIC: No actions. Q4 went like a dance, even though little growth was seen. In my opinion, an insurer operating conservatively with 20+% ROE shouldn’t be available at 8x EPS, but perhaps that’s just my opinion.
NewtekOne: Under review today: a diversified financial firm that operates a bank and aims to earn money in almost every way except interest income. Sounds strange, but it’s a hell of a profitable business (~25% ROE, 50% ROTCE).
Yeah. I don’t recommend following suit with this one, and frankly, these pennies should probably be put into IGIC or Fairfax. But I’m betting that the seemingly competent management team can grow the banking business to a scale where interest income becomes a real pillar alongside loan sales and payment processing. If that’s achieved, there’s potential for a pretty strong upside (now 2025e P/E 5.5x). If this doesn’t work, capital will likely be destroyed quite thoroughly.
Philip Morris: No actions. Nicotine is popular with the people, and a small position keeps growing.
Investor AB: No actions.
Exor: After a long wait, I managed to buy a small initial position in this for the portfolio when the company announced it would sell Ferrari to finance new investments and a decent-sized buyback program. While selling Ferrari sounds insane, from a capital allocation perspective, it’s an excellent move: getting rid of a large and overpriced company from the portfolio, and using the proceeds for something more profitable (e.g., buying back its own shares trading at a 50% discount to NAV).
The position is intentionally small, as I want to leave this to simmer next to Investor for a long time, but I don’t see it as impossible to take a proper “investment” position later.
Next review will be in the summer pastures. Hopefully, the market environment will be a bit more stable then.
44 Likes
An astonishingly unique portfolio. May I ask where you got the ideas for these and how long you’ve been investing?
I checked several of them on Seeking Alpha. Quite impressive return curves, respect!

No stocks in the portfolio. Cryptocurrencies make up about 3% of assets, but they are not in the chart. The portfolio has performed well, and if indices continue to decline, I will likely sell interest-bearing assets and move more money into indices. I personally expect the S&P500 to hit new lows in the coming months, unless Trump surprises and starts making decisions whose permanence can be trusted.
14 Likes
I have been investing in my current way for about two years. Ideas have been gathered mainly from Fintwitter and Substack writings, although, for example, the initial acquaintance with investment companies was made several years ago.
1 Like
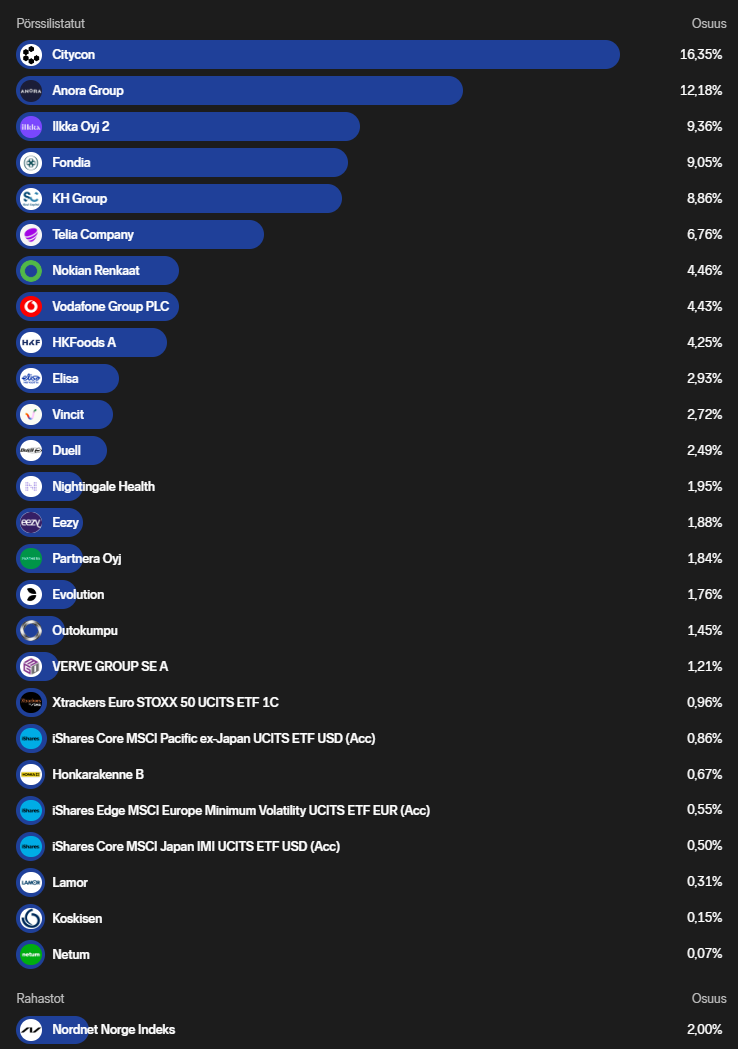
A quarterly review is traditionally easiest to start with the portfolio’s current holdings. Taking into account pending dividends of €3730 - taxes, the investment rate is 201%.
28 Likes
I do have these investments, probably too many. 54 in total. The intention is to trim them down at some point and consolidate positions, but currently, the market is so volatile, and I’m not keen on selling at a loss. However, for example, I’d like to sell Besi and invest that money directly into the VanEck Semiconductor ETF, but now is a bit of a bad time. A return of approximately 7% has been achieved this quarter, which I think is quite good; most of it came from active trading and selling.
- OP-Nordic Index A
- OP-World Index
- iShares Automation & Robotics ETF
- iShares Ageing Population ETF
- 2G Energy AG
- Akzo Nobel N.V.
- Alma Media Oyj
- Amazon.com, Inc.
- Future of Defence ETF
- Bird Construction Inc.
- BE Semiconductor Industries N.V.
- Biohit Oyj
- iShares V PLC - iShares S&P U.S. Banks ETF
- Invesco CoinShares Global Blockchain ETF
- Cargotec Corporation
- Cibus Nordic Real Estate AB (publ)
- Cargojet Inc.
- Concejo AB (publ)
- VanEck Crypto& Blockchain Innovators ETF
- Deutsche Beteiligungs AG
- VanEck Video Gaming and eSports ETF
- Fugro N.V.
- VanEck Gold Miners UCITS ETF
- Genfit S.A.
- Gofore Oyj
- Global X Video Games & Esports ETF
- Heidelberger Druckmaschinen Aktiengesellschaft
- iShares MSCI China UCITS ETF
- iShares Electric Vehicles and Driving Technology ETF
- iShares Core MSCI EM IMI ETF
- JDE Peet’s N.V.
- VanEck Space Innovators ETF
- Kemira Oyj
- iShares Digital Security ETF
- Amundi MSCI EMU Small Cap ESG Broad Transition ETF
- Magellan Aerospace Corporation
- Novo Nordisk A/S
- VanEck Uranium and Nuclear Technologies ETF
- OSE Immunotherapeutics SA
- Peugeot Invest SA
- Pembina Pipeline Corporation
- Semapa - Sociedade de Investimento e Gestão, SGPS, S.A.
- Softronic AB (publ)
- SPDR S&P US Dividend Aristocrats ETF
- Stellantis N.V.
- Suncor Energy Inc.
- Tubos Reunidos, S.A.
- Vanguard FTSE 250 ETF
- Veren Inc.
- VanEck Semiconductor ETF
- Wetteri Oyj
- WisdomTree Cloud Computing ETF
- Xtrackers Artificial Intelligence &Big Data ETF
- Xtrackers Nikkei 225
The TOP3 best investments are Magellan Aerospace Corporation, JDE Peet’s N.V, and Veren Inc.
The TOP3 worst investments are Stellantis N.V, VanEck Crypto& Blockchain Innovators ETF, and BE Semiconductor Industries N.V.
The goal for the next quarter could be to consolidate positions and reduce the number of investments; for example, 40 could be a good target.
9 Likes
Quick Q1 2025 portfolio update.
Evolution gaming 10.0 %
Qt 5.5 %
Svenska Handelsbanken 5.3 %
Puuilo 5.0 %
Revenio 5.0 %
Tractor Supply 4.2 %
Talenom 4.0 %
Gofore 3.7%
Sampo 3.6 %
Harvia 3.3 %
Nokian Renkaat 2.7 %
Tieto 2.4 %
Sandvik 2.1 %
Berkshire Hathaway 1.6 %
Fastenal 1.0 %
Vaisala 0.6%
ADP 0.4 %
Graco 0.4 %
Atlas Copco 0.3%
Nordea 0.3 %
Cash/fixed-income investments 16.2%.
Funds and ETFs (Seligson, Pyn Elite, Splitan, EUNL, EUNK, IUSN, Seligson & Co OMX Helsinki 25) 19.7%
New investments in the portfolio: Vaisala, Atlas Copco
Additions: Evo, Qt (addition before strong earnings report)
Sold off: eQ
Reductions: Tieto, Qt (after earnings report)
Short-term trades at a loss: Nokian Renkaat
The portfolio’s cash/fixed-income position has grown slightly. The proportion of cash is currently too large. I aim to buy more quality companies when the price is right.
During the last quarter, I finally bought a small position in Vaisala. It would have been available much cheaper before, but I just hadn’t pulled the trigger. However, the company is of such high quality that I finally dared to jump on board even at these prices. Similarly, Atlas Copco has been on my watchlists as a quality company for a longer time. As a result of a price drop, it also found its way into my portfolio.
I ended up selling eQ from my portfolio on a somewhat accelerated schedule. The schedule, however, could have been faster, in which case I would have incurred smaller capital losses. The company’s ownership structure is simply not to my liking, so it has no place in my portfolio.
Although the number of companies in my portfolio increased by one, my intention is to gradually reduce the number while increasing the average quality. I will increase diversification by simultaneously growing the proportion of ETFs and passive funds. Monthly savings into funds/ETFs will therefore continue.
Currently, Tieto, Talenom, and Nokian Renkaat are most under fire among my portfolio companies. I have been following Tieto’s stumbling for long enough, and it is not high-quality enough for my portfolio. Nokian Renkaat’s special situation got a bit of an extension. The company was not originally intended for a long-term portfolio, so it can go when the time is right. I will own Tieto and Nokian Renkaat in the future through a Finland ETF. I will follow Talenom’s operations with great interest this year. If there is no clear turnaround during 2025, the company will very likely fly out of my portfolio.
Let’s also note here that the median P/B 2025 for Finnish companies followed by Inderes, calculated from Inderes’ website, is 1.68 (P/B 2026 median 1.63), and Inderes has 19 buy recommendations and 12 sell recommendations. CNN’s Fear & Greed index was 19 (Extreme Fear) at the turn of the quarter. However, the number of Inderes’ buy recommendations has again decreased during the past quarter: 24 → 14 → 10 → 25 → 19. As a long-term investor, I interpret “add” and “reduce” recommendations to some extent as “hold” recommendations.
12 Likes
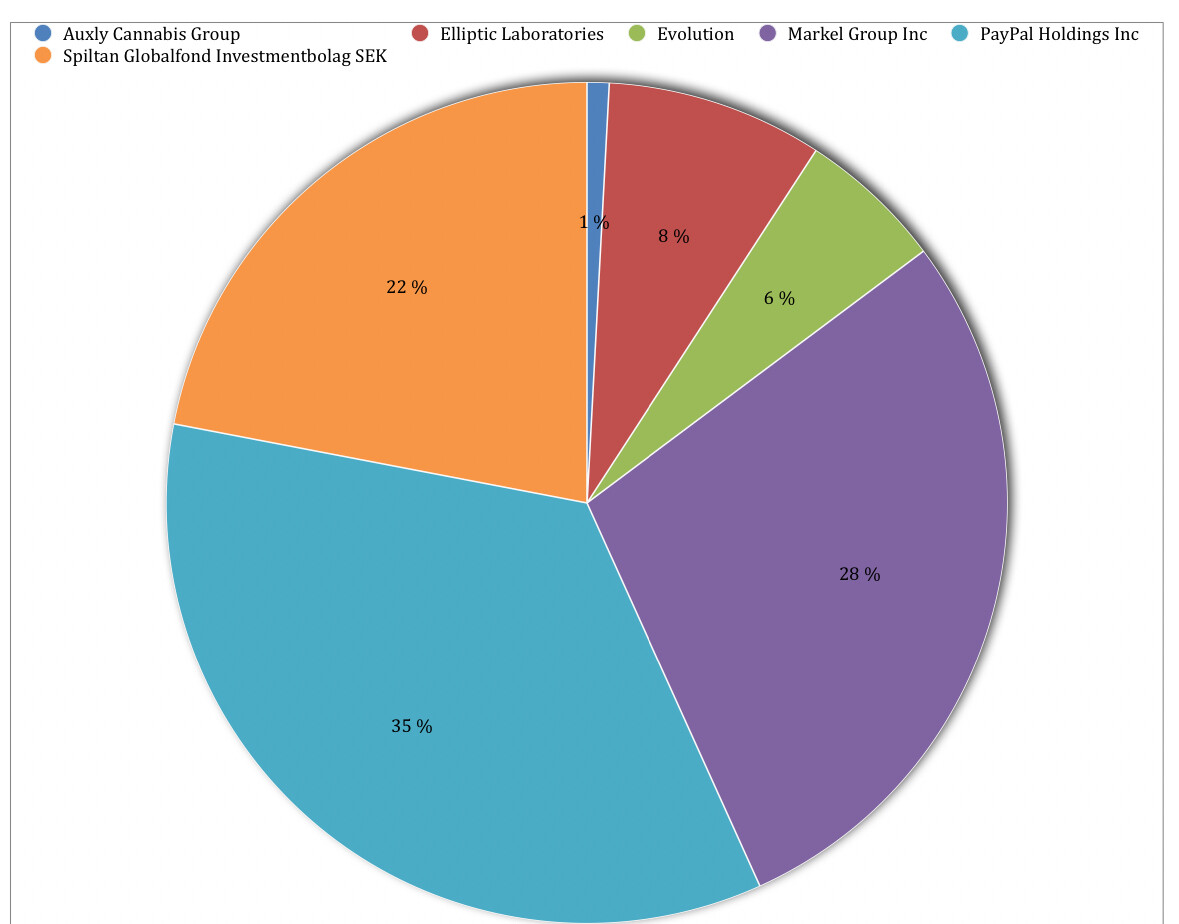
Exceptional situation in the portfolio. Paypal’s weighting has been raised to 35 percent due to the decline. Just last week it was 15. Sometimes I feel like taking a risk - usually I’ve had to pay the price for it.
Elabs has been added gradually. Evo just came back into the portfolio.
In addition to this Nordea portfolio, there is also a 15% slice of the portfolio in the Phoebus fund, which balances that out.
edit. yesterday 2.4. I got cold feet in the last trading minutes and sold a good 30% of Paypal. Now looking at where the markets are heading, I probably should have sold even more.
8 Likes
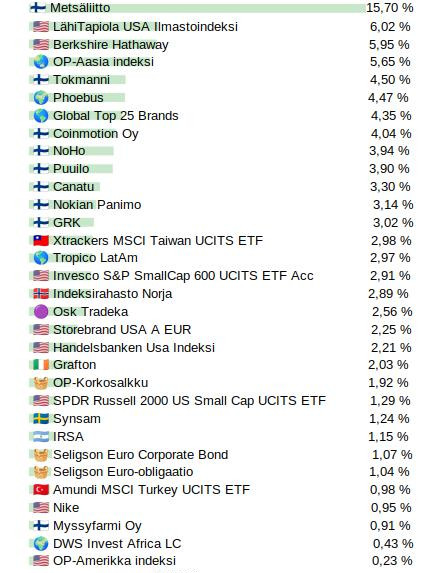
Tämä katsaus kattaa vuoden 2025 ensimmäisen vuosineljänneksen. En ole siirtymässä kvartaaliraportointiin, vaan seuraava tulee puolen vuoden päästä syksyllä. Salkun koko on reilut 24 tuhatta euroa. Tästä pääsee suoraa loppuun.
Ostot ja myynnit Q1 aikana
Ostot:
Osakkeet:
- Puuilo
- NoHo Partners
- Tokmanni
Osakeannit:
- Nokian Panimo
- GRK
Rahastot:
- Phoebus
- Tropico LatAm
- LähiTapiola USA ilmastoindeksi
ETF:
- Xtrackers MSCI Taiwan UCITS ETF
- Invesco S&P SmallCap 600 UCITS ETF
Osuuskunnat:
- Metsäliitto
Korot:
- Seligsonin Euro Corporate Bond
Myynnit:
Osakkeet:
- Tesla kokonaan pois
- Titanium kokonaan pois
Rahastot:
- Nordnet Norja-indeksi
Salkku:
Salkun kehitys:
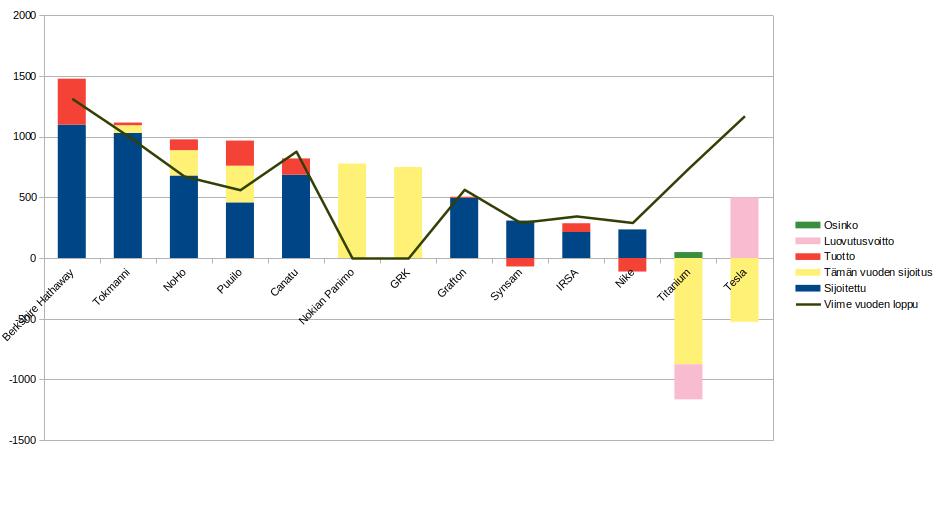
Kuvaan salkun kehitystä viikkopylväinä euroina.
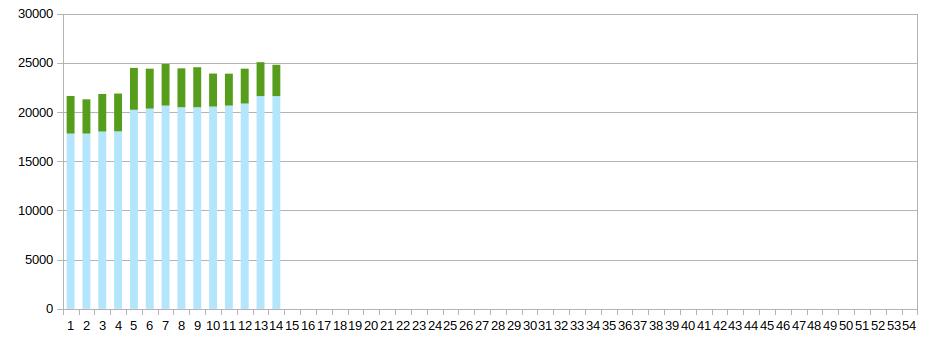
Vaaleansininen on sijoituksen määrä. Kumulatiivinen tuotto näkyy vihreänä. Kun pylväs lähtee punaisena, salkku oli kokonaisuudessa tappiolla.
Strateginen tarkastelu
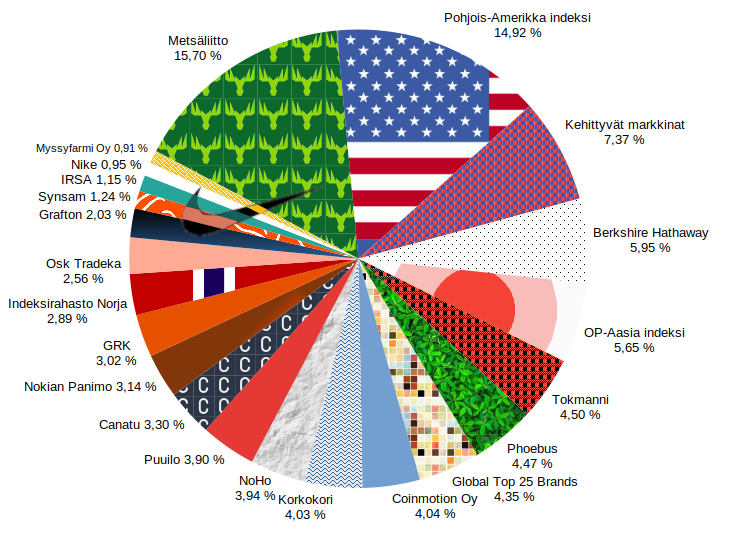
Osakkeiden maantieteellinen hajautus ja omaisuusluokat:
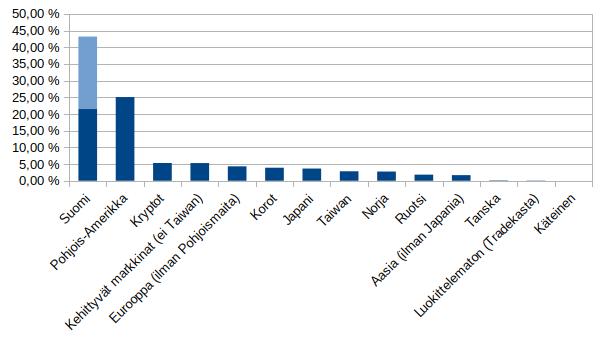
Suomen vaaleansininen on osuuskuntien ja listaamattomien yhtiöiden osuus.
Allokaatio:
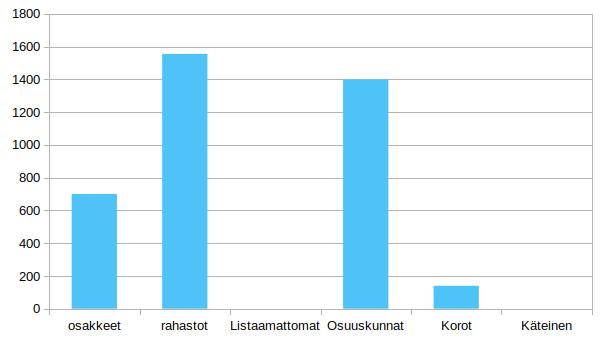
Osakkeet 33 %
Rahastot 40 %
Listaamattomat yritykset 5 %
Osuuskunnat 18 %
Korot 4 %
Salkussa ei ole käteistä.
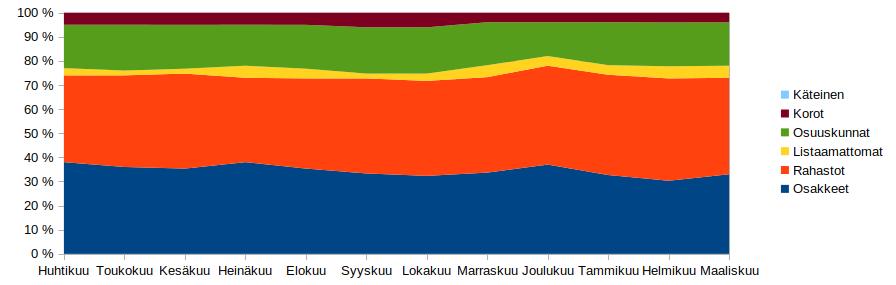
Allokaation kehitys
Salkkuni allokaation palautusarvot uusina sijoituksina 2025 lopun tavoite:
Suojan lisäys 2175 euroa
Osakkeiden vähennys 4428 euroa
Likvidoimisprosentti 77 %
Jätän likvidoimisprosentin ulkopuolelle vaikeasti tai hitaasti likvidoitavat kohteet:
-Osuuskuntien tuotto-osuudet
-Listaamattomat yhtiöt
Osinkoa maksavat yhtiöt 73 %
Tässä on mukana listatut ja listaamattomat osakkeet, jotka maksavat osinkoa.
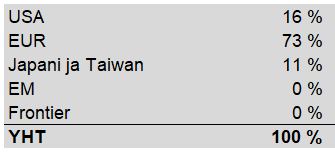
Suojaamattomuusarvo 8,57 %
Tämä arvo on toteutuneen salkun koon ja suojan laskentaan käytettävän tavoitearvon välinen erotus prosentteina.
Uudet sijoitukset ja lunastukset vuonna 2025
Osakkeet
Tesla ja sijoittaminen Yhdysvaltoihin
En ota foorumilla mitään näkemystä politiikkaan. Katsoin, että ennustin Suomen hallituspohjankin väärin. Totean vain, että minulla ei ole mitään taitoa käsitellä Yhdysvaltojen politiikkaa. Teslan osake kuitenkin politisoitui voimakkaasti Elon Muskin siirtyessä Trumpin hallintoon. Näin Trumpin politiikka epäsuorasti vaikuttaa Teslan brändiin. Euroopassa keskiöön on tullut Trumpin Ukraina-politiikka, joka näyttää pelaavan Venäjän pussiin. Itse kuitenkin tiedän, että toimintani jälkimarkkinassa ei vaikuta mihinkään, koska omistukseni ovat joka suhteessa minimaalisia. Kun myyn osakkeen uudelle omistajalle tai treidaajalle, niin kukaan ei voi tietää onko kyseessä protesti tai voittojen kotiutus. Lisäksi viime vuonna tein myyntejä ihan vain siksi, että rahat loppuivat eli en sinänsä nähnyt yhtiöitä huonoina. Tässä kontekstissa en siis voi pitää Tesla-myyntejäni kovinkaan suurena eleenä.
Tietyllä tavalla voisin nyt ohittaa syyt miksi, Tesla alun perin oli salkussa. Voisin olla puhdas Tesla-häpeästä. Palataan kuitenkin näihin. Ehkä helpoiten perusteltu syy on omistaa Teslaa indeksin mukaan. Kuten olen todennut, niin kaikki USA-indeksirahastot ei omista Teslaa, joten voin perustella suoraa omistamista oikeamman indeksisijoittamisen kautta. Oikeasti minun piti pitää Teslaa salkussani myös siinä tilassa, kun olisin ollut taloudellisessa vaikeuksissa. Pistin Teslan siis hyvin pitkään salkkuun melkeinpä ikuisuussalkkuun. Tämä tietenkin aiheutti sen, että en myynyt aivan heti, kun brändi sai kolhuja Elon Muskin toimista. Ehkä raskain peruste on Elon Musk -fanitukseni, jonka olisin nyt mielelläni ohittanut. Tämä varmaan olisi herkullinen aihe, mutta en pysty nyt kovinkaan syvällisesti tähän tarttumaan. Marraskuun lopulla kuitenkin tarkastelen, mikä olisi Tesla-position koko. Siltä osin täytyy tarkkailla Elon Muskin tekemisiä.
Jos nyt mennään järkisyihin liittyen Tesla-myyntiini, niin korkea arvostus samalla, kun brändi vedettiin vessasta alas. Yhtiön toimitusjohtajalla on liian monta rautaa tulessa ja Tesla on tuuliajolla. Myyntini ehkä suurin este oli Nordnetin korkea kulu, mutta pystyn ohittamaan sen suurella voitolla. Verotuksesta ei tarvinnut huolehtia, koska myin osakkeet tappiollisesta osakesäästötilistä. Sain rahat siis heti käyttöön verottomana. Jos Tesla olisi ollut arvo-osuustilissä, olisin miettinyt vielä toisen kerran myynnin järkevyyttä.
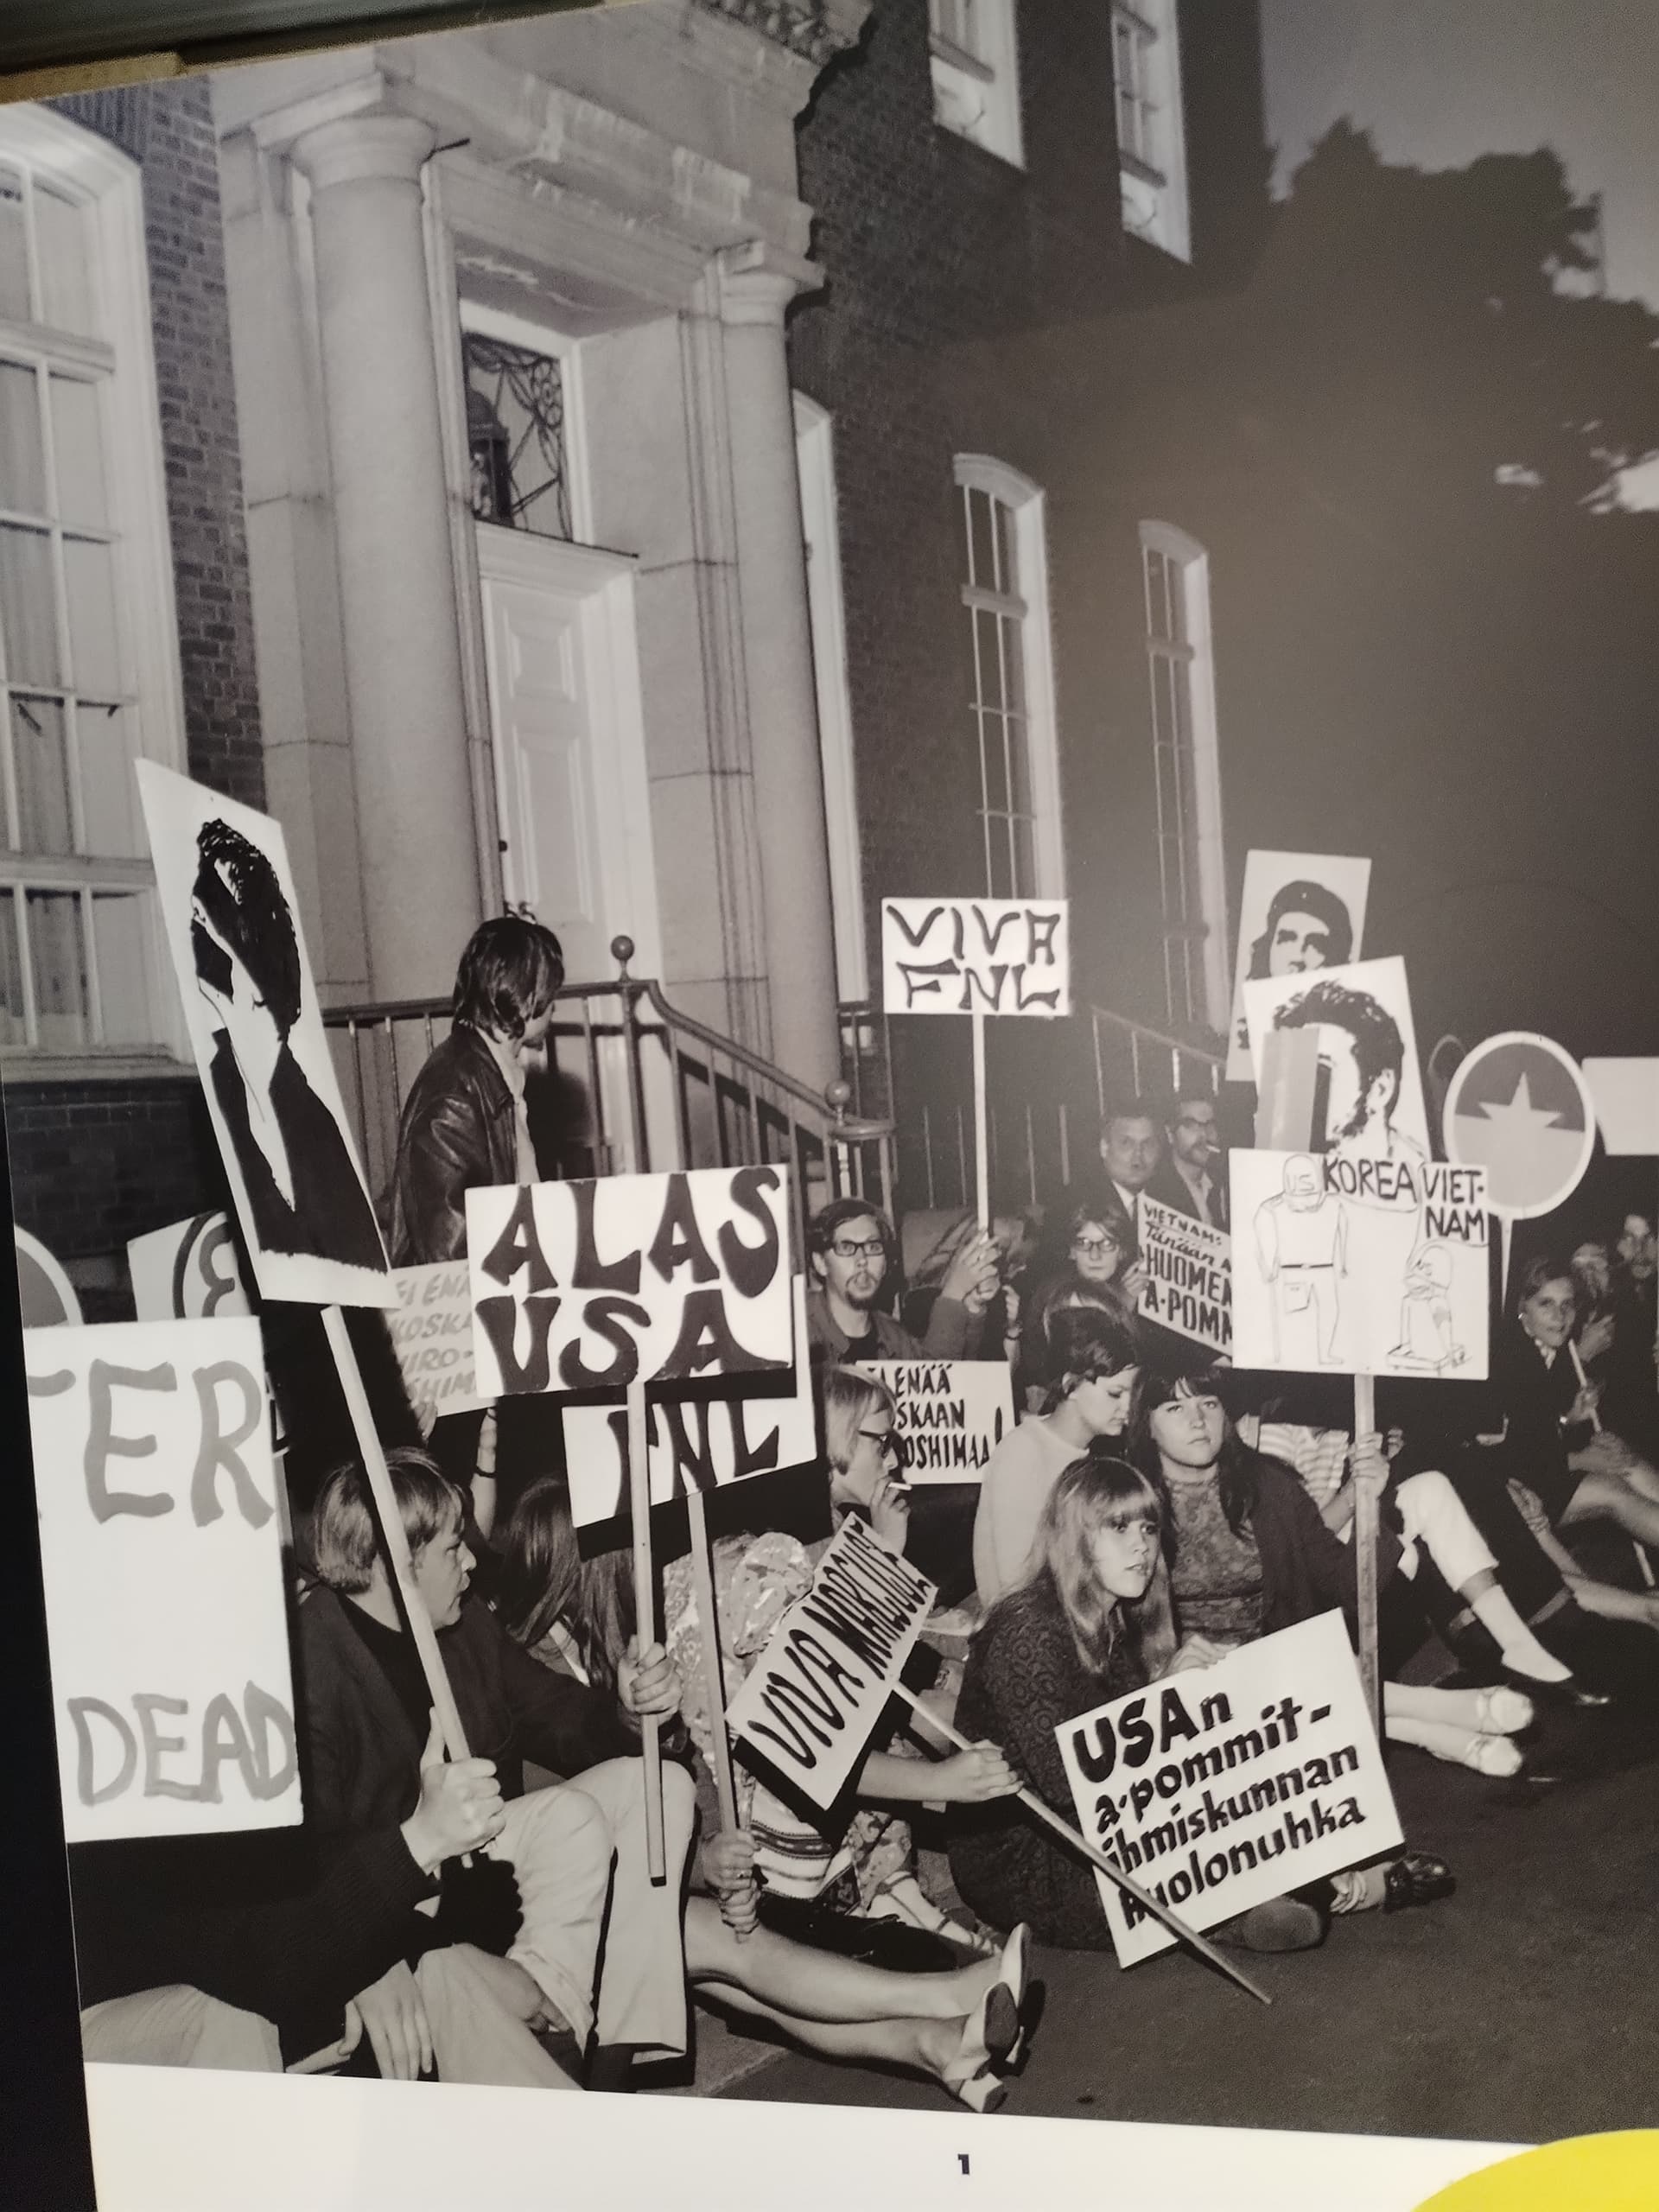
*Kuva on otettu Helsingin Arkkitehtuurimuseosta.*Should all US holdings have been sold in protest against the current administration? I have to start by bringing up the humorous point that I probably would have made the sales using a phone packed with US software and services. As a rule of thumb, I don’t sell anything from my portfolio that I can’t boycott. I would say that a small boycott is a significantly more effective method than selling on the secondary market. Companies are hardly going to react in any way to reductions by Finnish funds, for example. The link to the US administration is even more indirect. You notice at general meetings what the influence opportunities of retail investors are—none at all. But if you have no faith in the US and US companies, then there’s nothing wrong with selling or not owning them in the first place.
Titanium
The problems in the Finnish real estate market were also reflected in the funds managed by Titanium. For example, Titanium’s Care Fund (Hoivarahasto) faced such large redemptions that the fund was temporarily closed to redemptions. This also led to a collapse in the share price. I was seeking real estate risk with Titanium, and now I’ve reaped those risks. I have to say that I’ve been wary of the company’s new management and strategy. If the strategy succeeds, the company will become significantly less dependent on its real estate funds. They want to make it a diversified asset management company. However, I chose the company as a real estate fund house, not an asset manager, so the original investment thesis no longer holds. There are other asset management companies much further along on the Helsinki Stock Exchange, so why stay in Titanium.
I also looked at Inderes’ forecasts and mirrored them against my own investment horizon. According to these, the company would still be in a slump when my strategic investment period ends in 2028. Perhaps one should stay away from the biggest risk pockets and aim for as steady investments as possible.
However, I still went to the general meeting to sniff out the situation before making a selling decision. I consider the CEO’s review at the general meeting very important, but it was probably overall the same as the annual financial statement briefing, so this didn’t provide any major experience. The refreshments at the general meeting consisted only of coffee and tea. And I didn’t even get a ballpoint pen as a souvenir. That certainly didn’t change my mind.
[quote=“Vanerihands, post:4851, topic:52688, full:true”]
I sold all of my Titanium shares at a price of 7.72 euros. The reason is that the only refreshments served at the general meeting were coffee and tea.
[/quote]### Tokmanni
I already mentioned that a small shareholder has no influence whatsoever when attending the general meeting. However, I gave a powerful and impactful speech in favor of dividends at Tokmanni’s general meeting. This has resulted in Tokmanni announcing a more precise timeframe for the autumn dividend distribution in 2025 than before. Thus, the autumn dividend is still subject to a board decision, and the dividend will be distributed in the fourth quarter if the board so chooses. Previously, even the distribution quarter was not announced in advance. I really should get a medal for this from the Dividend Party.

Unfortunately, my other topic of complaint at the general meeting did not gain any traction. Finnish-language earnings webcasts were not brought back, nor were they subtitled. In this regard, I will continue with a passive approach toward the investment. The plan is to consolidate my holdings into a single account, but this will likely happen next year at the earliest. The idea is also that this year’s general meeting will be the last one for the time being. Tokmanni’s general meeting is definitely my favorite, but getting there is quite a big financial effort.
Funds
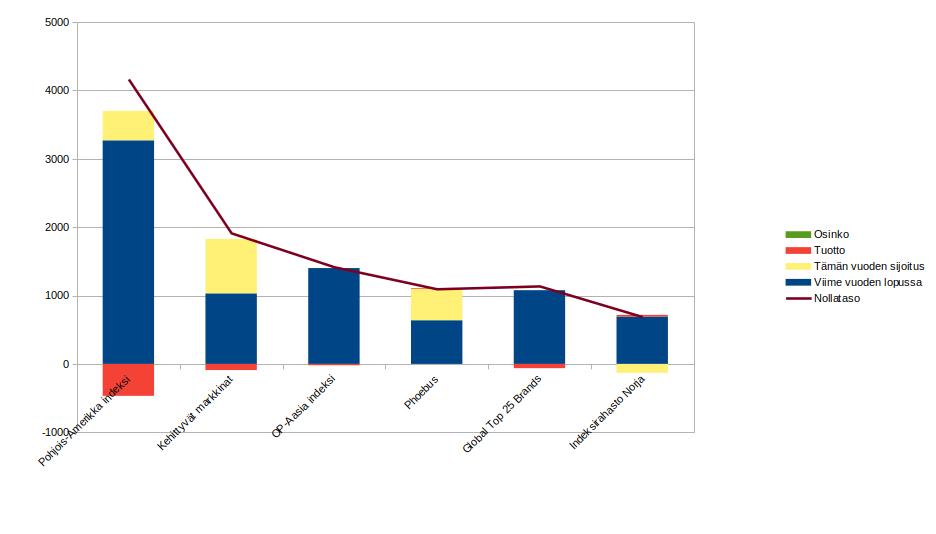
North America Index
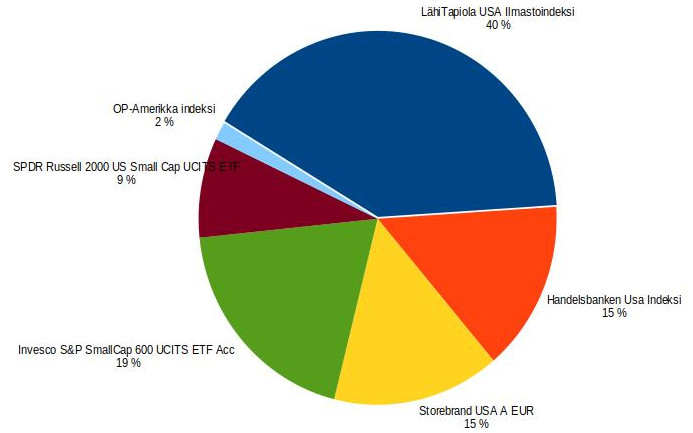
Investing in the USA started giving me the same vibes as flying. As soon as I finally managed to grow my US weighting to the target after a long time, it became frowned upon. For now, in North America, I will focus on portfolio-managed instruments instead of indices, namely Berkshire Hathaway and Phoebus.
Emerging Markets
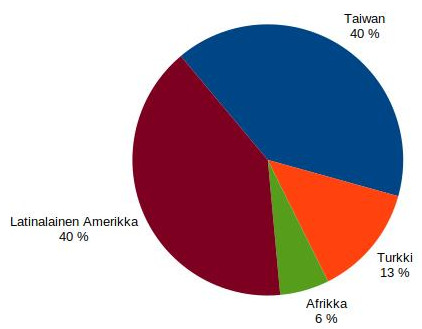
In the early part of the year, I increased my holdings in the Tropico LatAm fund and the Taiwan ETF. I currently don’t see any reason to change the weightings. The emerging markets position is also of the right size, in my opinion.
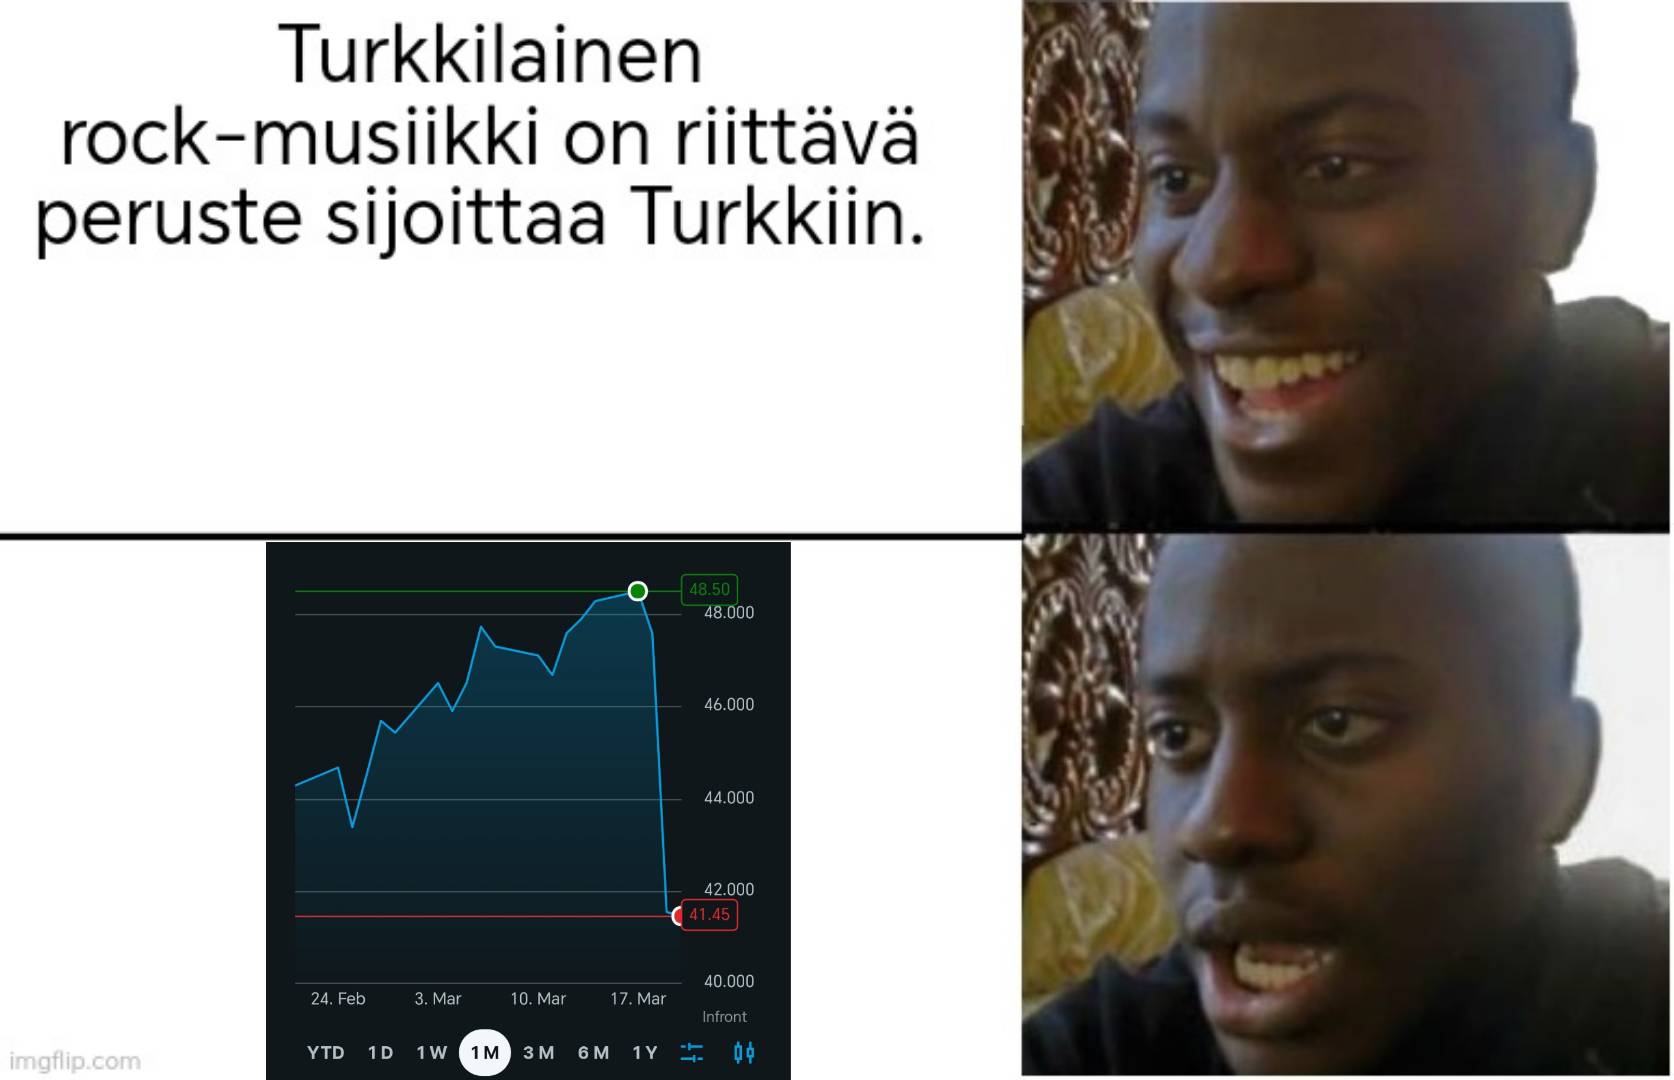
I probably should have sold the Turkey ETF completely when I trimmed it.
OP Asia Index
I am satisfied with the product, but I currently see no need to add to it. I am in a wait-and-see mode because the intention is to make a big move into Japan.
Phoebus
I still believe in stock picking as well, and you get that from Phoebus regardless of the thickness of your wallet. To me, this invests a bit similarly to how I do. Anders Oldenburg, however, invests successfully while I do so losing money. I am currently making monthly savings into Phoebus. In addition, I have made larger lump-sum additions.
Global Top 25 Brands
This has fallen behind other funds a bit. However, this is still the cheapest way for me to get brands into my portfolio. It would have been worth buying Nike exclusively through this as well. The problem with me not adding to this lies in Phoebus, which will potentially be merged into this fund. I believe that in the future I will make a decision between this fund and index investing.
Norway Index
I trimmed my Norway holdings because I thought that perhaps the size of a single-country fund shouldn’t be that large. I still find the brands in this fund interesting.
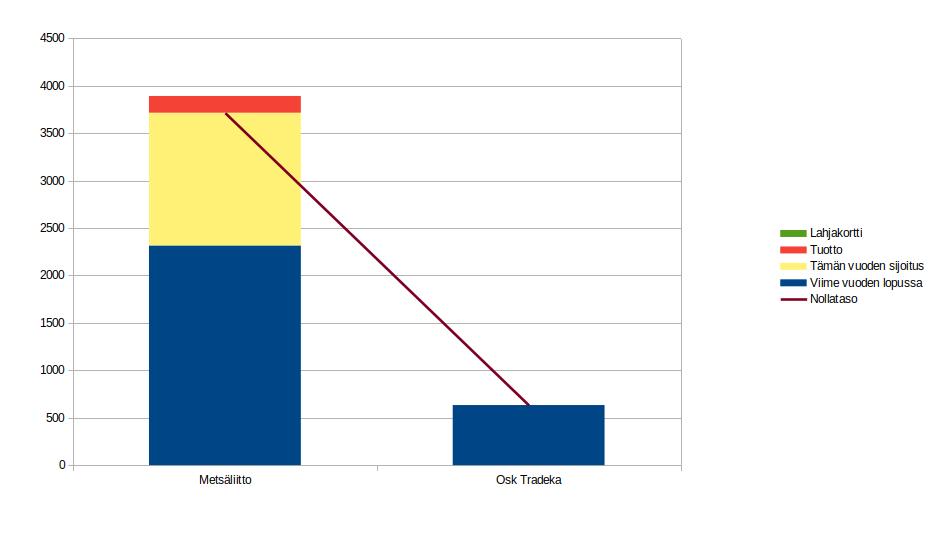
Cooperatives
Fixed Income
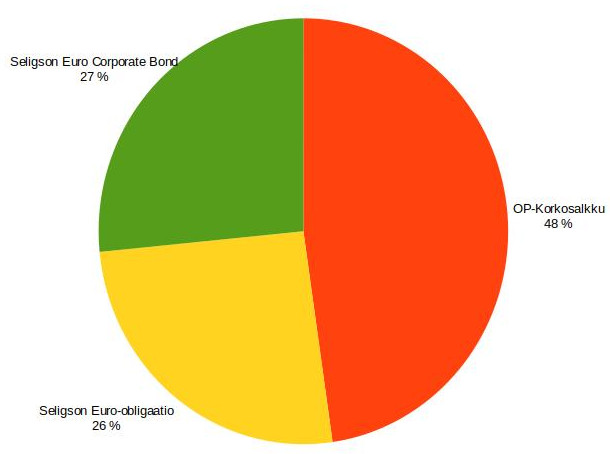
I have to say I am disappointed with these fixed-income funds. I’ll probably put them up for sale at the end of the year.
I'm Still Here
This might suggest that I am leaving the forum, but I’ll be here at least until the end of the year. I’m Still Here (Ainda Estou Aqui) is a Brazilian movie that I went to see with my sister. Based on true events, the film tells the story of former congressman Rubens Paiva and especially his family. The military junta takes Rubens, his wife, and one of their daughters to brutal interrogations. Rubens never returns from the interrogations. Unfortunately, this topic feels very current.
Hidden section continues
The Lord of the Rings
I booked tickets for the Tampere Theatre’s mega-production back in last August. My performance was in January, and the plan was to spend time at Tampere Hall before the show as well.
I arrived at Tampere Hall around twelve and hid the coat I bought from Lidl in the coat check. I figured that if someone wants to steal that monstrosity, go right ahead. I had lunch at Restaurant Tuhto. I paid for the food using a NoHo gift card I had bought on Black Friday. However, I had paid full price for the gift card. The lunch was fairly standard.
After lunch, I popped in for a quick bit of shopping at the Moomin Shop. I also bought a program for The Lord of the Rings, even though these are starting to get a bit pricey. Next, I explored the Moomin Museum. As I recall, in my childhood, I saw 3D tableaux on the ground floor of the Metso library. There were plenty of these in the museum. In addition, there were paintings and drawings. Generally speaking, the museum is great. Time passed pleasantly there. I didn’t manage to book intermission refreshments in time, so I got them before the show.
[quote=“Vanerihands, post:3867, topic:52688”]
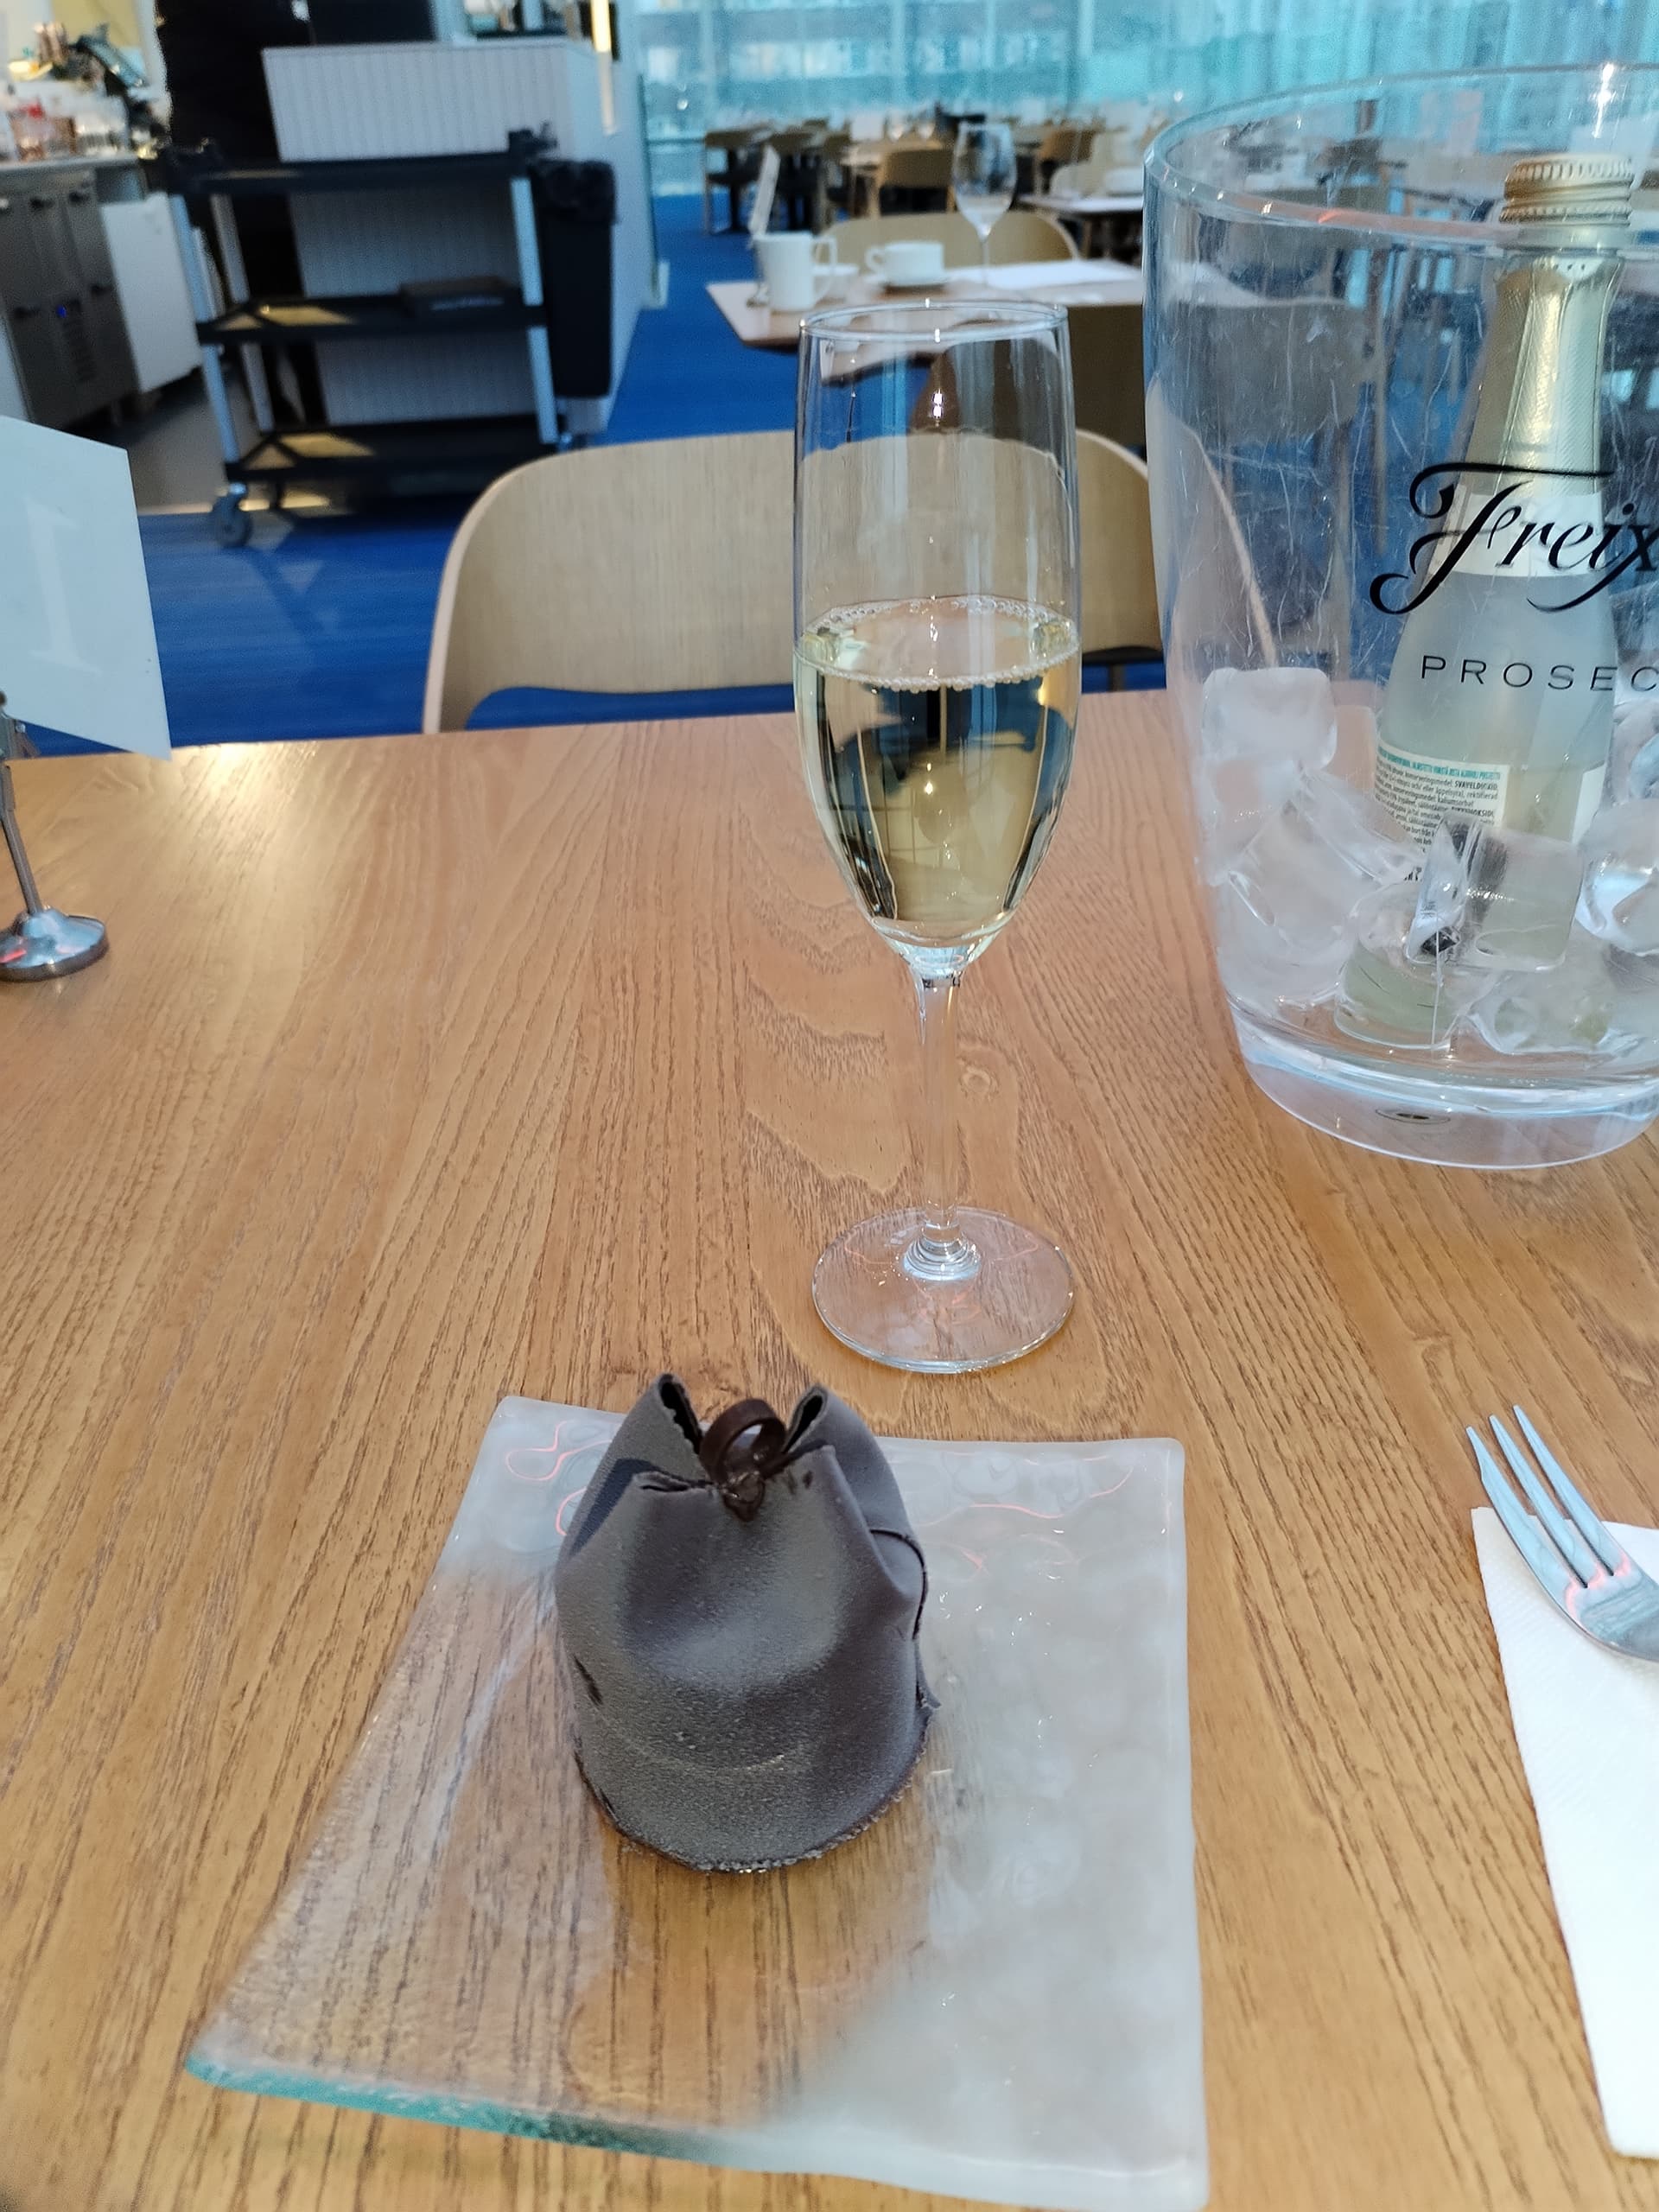
One might deduce from the picture that I had enjoyed a Mordor pastry with white wine during the intermission of The Lord of the Rings play. However, the drink was non-alcoholic and this was not the intermission.
[/quote]
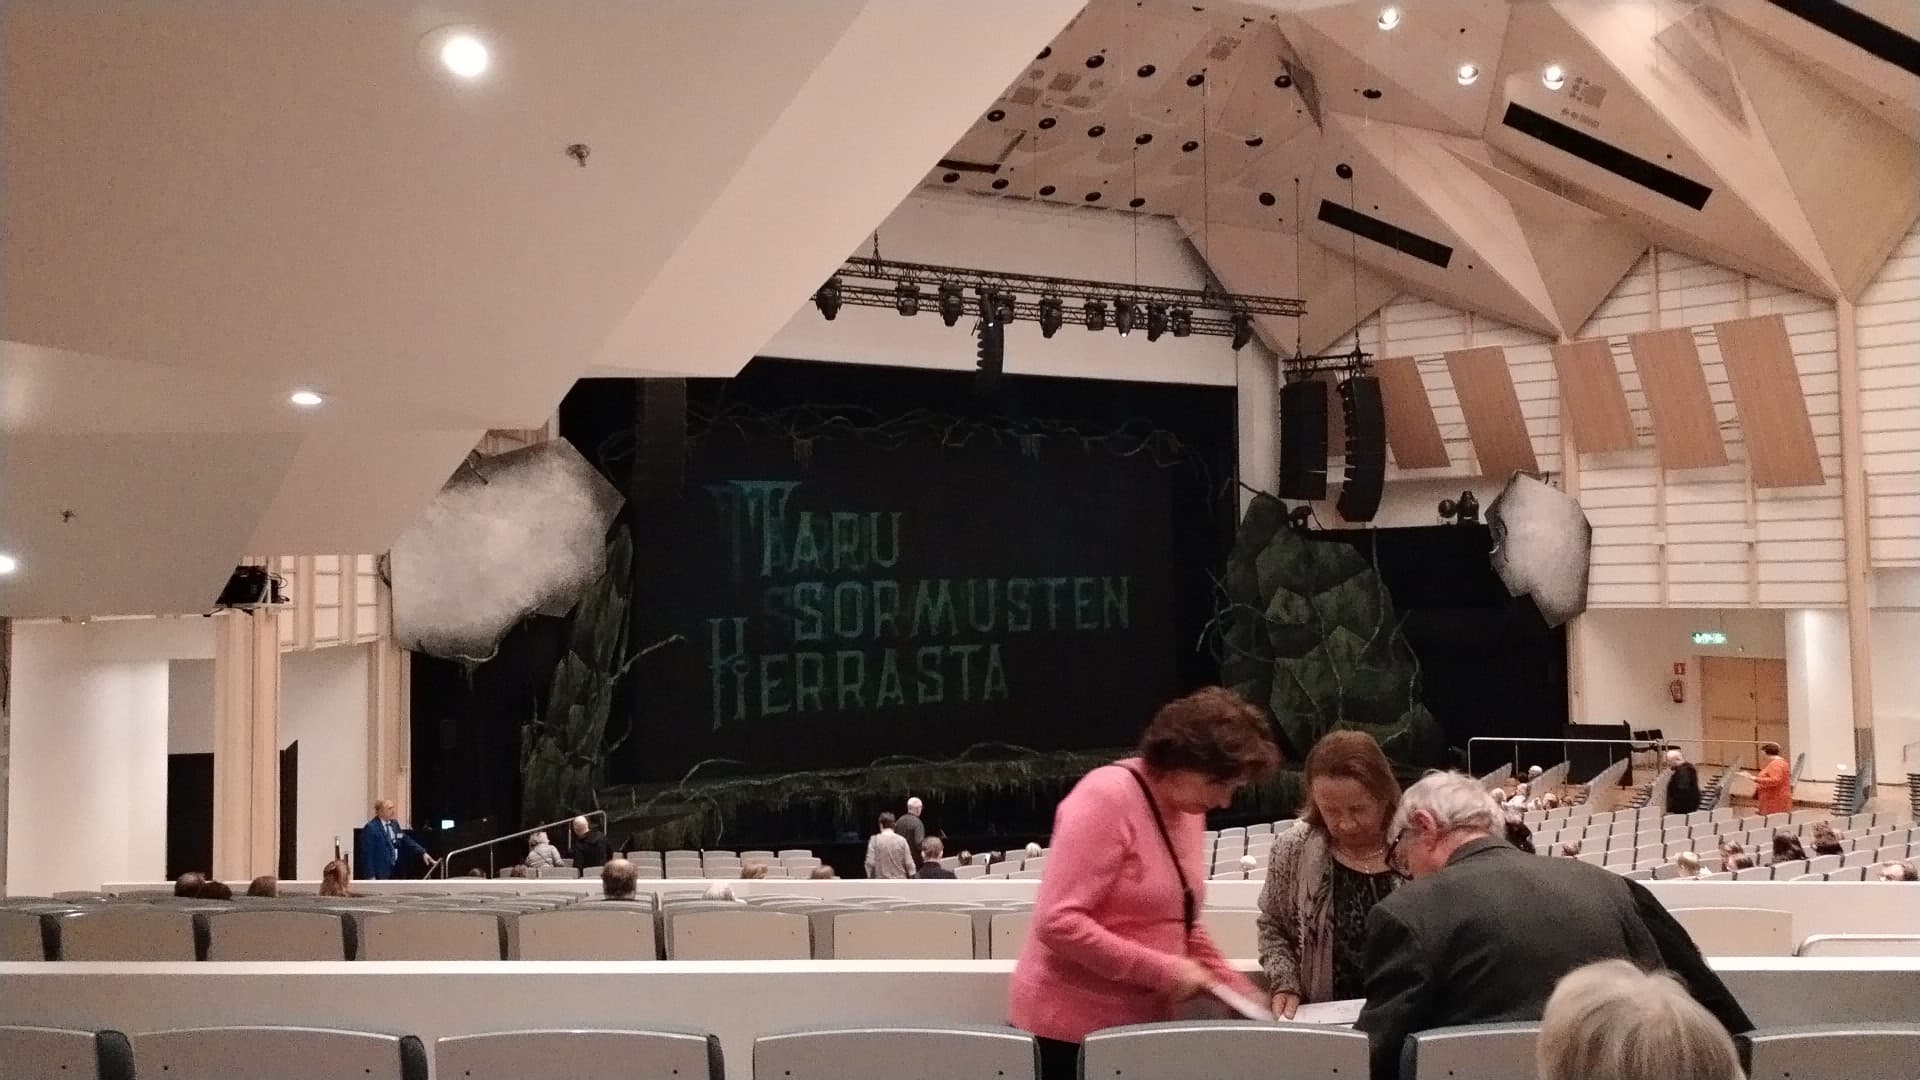
However, there was also a very good intermission snack at the venue, so I didn’t miss out. The Lord of the Rings is challenging to stage. The number of actors is quite small, which is especially noticeable in scenes that are supposed to feature mass forces. Therefore, the play tends to focus on a specific area, which in this case was Frodo and Sam’s journey to Mount Doom in Mordor. Surely, criticism has sometimes been directed at the character gallery in The Lord of the Rings book for being rather male-dominated, so mirroring this, it could be considered unusual that the role of Galadriel was given to a man. Although women did play hobbit roles.
Tuomas Kantelinen had composed a new soundtrack for the piece, which the orchestra played live. The music fit the performance well, but it felt very close to the music of the movies and thus didn’t bring anything new. The set design and costumes were excellent. The main hall of the Tampere Hall is quite large, so it was good that there were screens showing close-ups of the performance. I also tried to save a bit by choosing a remote seat in the auditorium.
The piece was a good four hours long including intermissions, so of course, the success of the play can be measured by the fact that it kept you hooked the entire time. I have to say that I’ve been annoyed by social media posts from people who think the only correct version of The Lord of the Rings is the Suomenlinna production from the late 80s. What about these younger generations? Surely they have the right to see the play. In my opinion, new versions are welcome. They don’t erase the old ones. I’ve also watched The Rings of Power series. I don’t have any sacred relationship with The Lord of the Rings, so I even pondered a bit whether to go see it at all, but it was definitely worth going.
I left Tampere Hall in the evening around half past eight. The whole day was spent nicely there.
Never Alone (Ei koskaan yksin)
I ran into phrases of this type during Finland’s NATO process. Now this has surfaced again with the new U.S. administration. The title of the movie directed by Klaus Härö likely refers to the brotherhood-in-arms between Finland and Germany, as well as Uncle Stiller’s aid work among Jewish refugees. I also listened to Rony Smolar’s book Setä Stiller: Valpon ja Gestapon välissä (Uncle Stiller: Between Valpo and the Gestapo). Härö had made the movie very compact in length, so the book provided a lot of additional information on the subject. Finland was a peculiarity during the Continuation War, as German and Jewish soldiers fought side by side against the Soviet Union. A few Finnish Jewish soldiers were even awarded the Iron Cross.
However, the situation on the home front was serious. Especially Jewish refugees were wanted by the Gestapo to be sent back to Germany. The Gestapo also had a list of all Finnish Jews, although the list did not directly fall into the Gestapo’s hands the way the movie depicts. However, eight Jewish refugees were sent to Germany, specifically under the leadership of Valpo (State Police) head Arno Anthony and Minister of the Interior Toivo Horelli. This is definitely a stain of shame that the movie deserves to highlight.
I also watched a documentary on the streaming service Max that touches on the topic. The documentary is called The Commandant’s Shadow. It was about the son of the Auschwitz commandant, who seemed just as naïve as Bruno, the main character in The Boy in the Striped Pyjamas. Was it some kind of blindness to his father’s actions or did he genuinely not notice anything?
To the Beat of Elvis’s Music in Luvia
In Luvia, they relied on humor this year. The musical All Shook Up – Liekeissä featured Elvis’s music, but it wasn’t based on Elvis’s life. The plot, in short, is that a young man arrives on a motorcycle in a small town, and from there a complicated love tangle unfolds. Good music and humor.
Trip to Helsinki
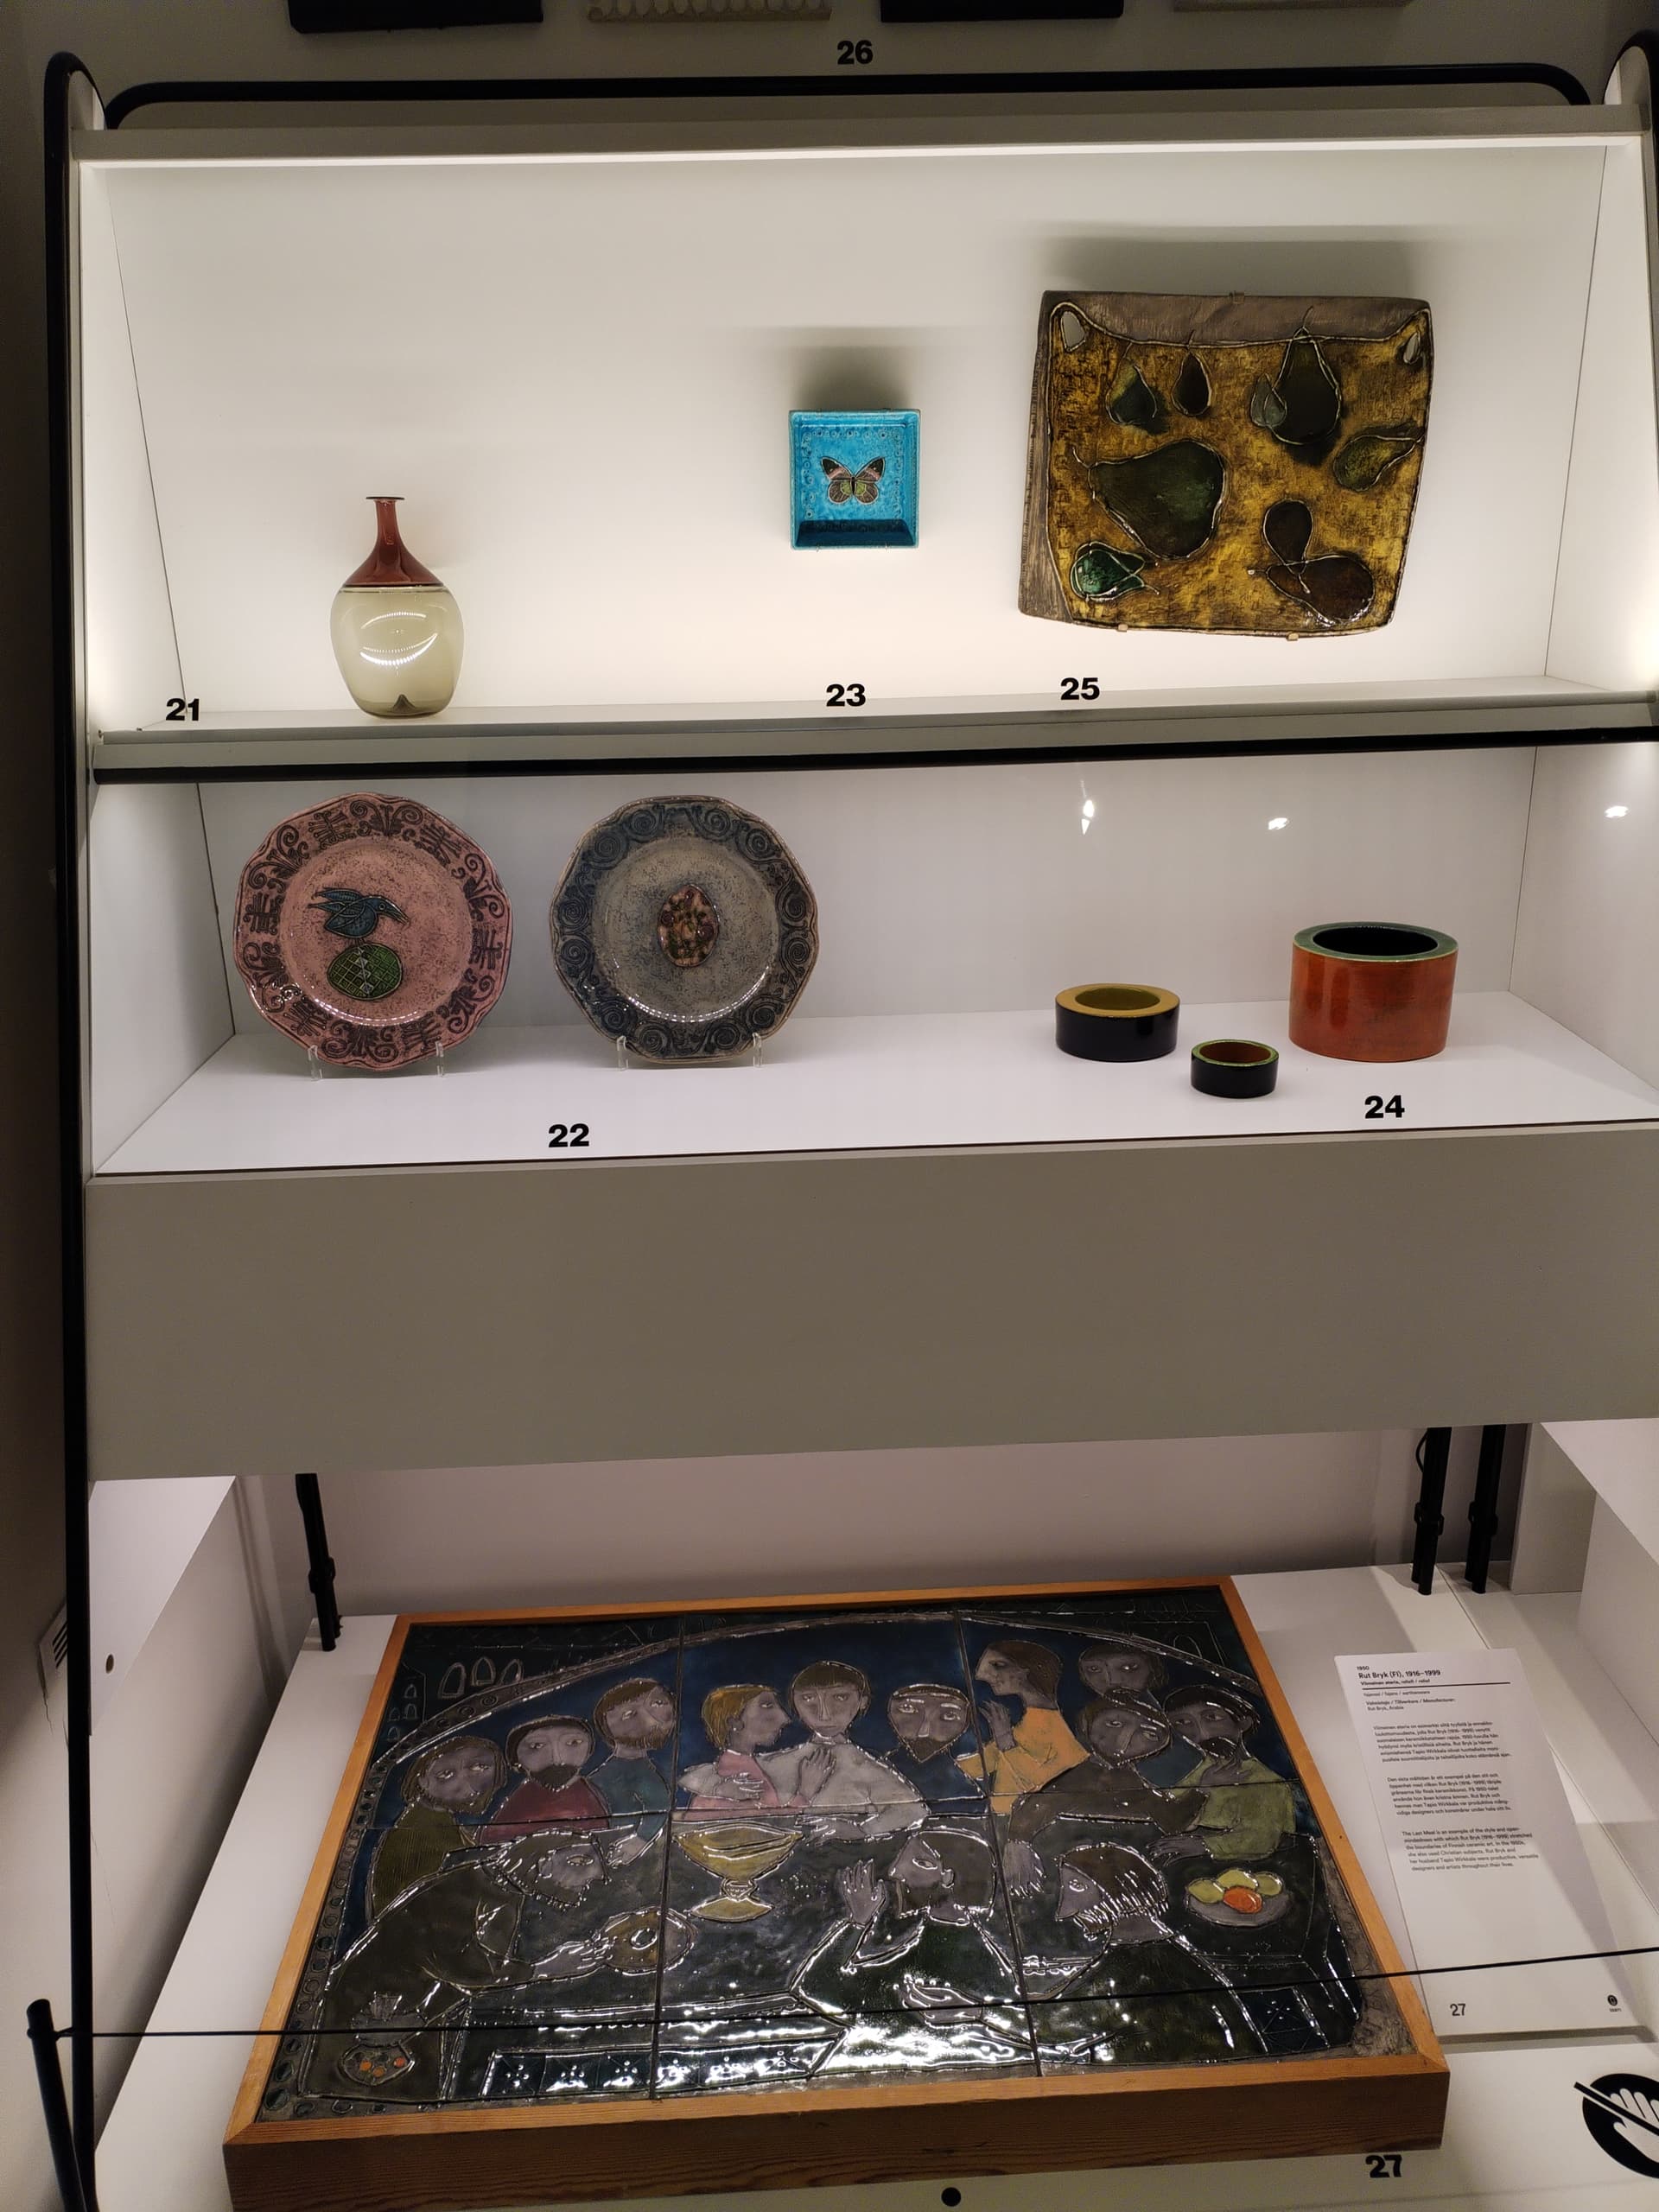
I have now broken this down into such small parts and talked about different segments, but the trip to Helsinki consisted of Titanium’s annual general meeting, the Museum of Finnish Architecture and Design, dining at Strindberg, the Keeping Up Appearances play at the Alexander Theatre, and the movie The Room Next Door (Olen yhä täällä). Better if I just post a few pictures:
Anastasia and Stalin
I also listened to audiobooks and will now highlight a couple of books. John Boyne’s book The House of Special Purpose (Tarkoin vartioitu talo) tells the story of a country boy, Georg, who rises to a high rank in the imperial court after saving the tsar’s brother from death. However, the story was too naïve and resembled 20th Century Fox’s animated film Anastasia. The story was nice and well-written, but I would have hoped for some twist at the end, like in All the Broken Places (Kaikki särkyneet paikat), which is a newer book by Boyne.
Pirkko Saisio’s book Suliko gets inside Stalin’s head. I really liked the stories and humor in this book. Pirkko Saisio read the book herself, which brought the author close to the listener. The book wasn’t even long and yet it was impactful. I must experience this again at some point.
Akira (Katsuhiro Ōtomo)My reactivation regarding Akira happened in a funny way when I got totally fed up with my wallpaper. While collecting Akira manga, it so happened that I ended up with a double of the 11th volume. Being too lazy to sell it, I decided to test how wallpapering with it would go. It went well, but it barely was enough. The old wallpaper shows underneath if you take down any pictures, but I’ve now acquired another Akira book, which I intend to use to continue the wallpapering.
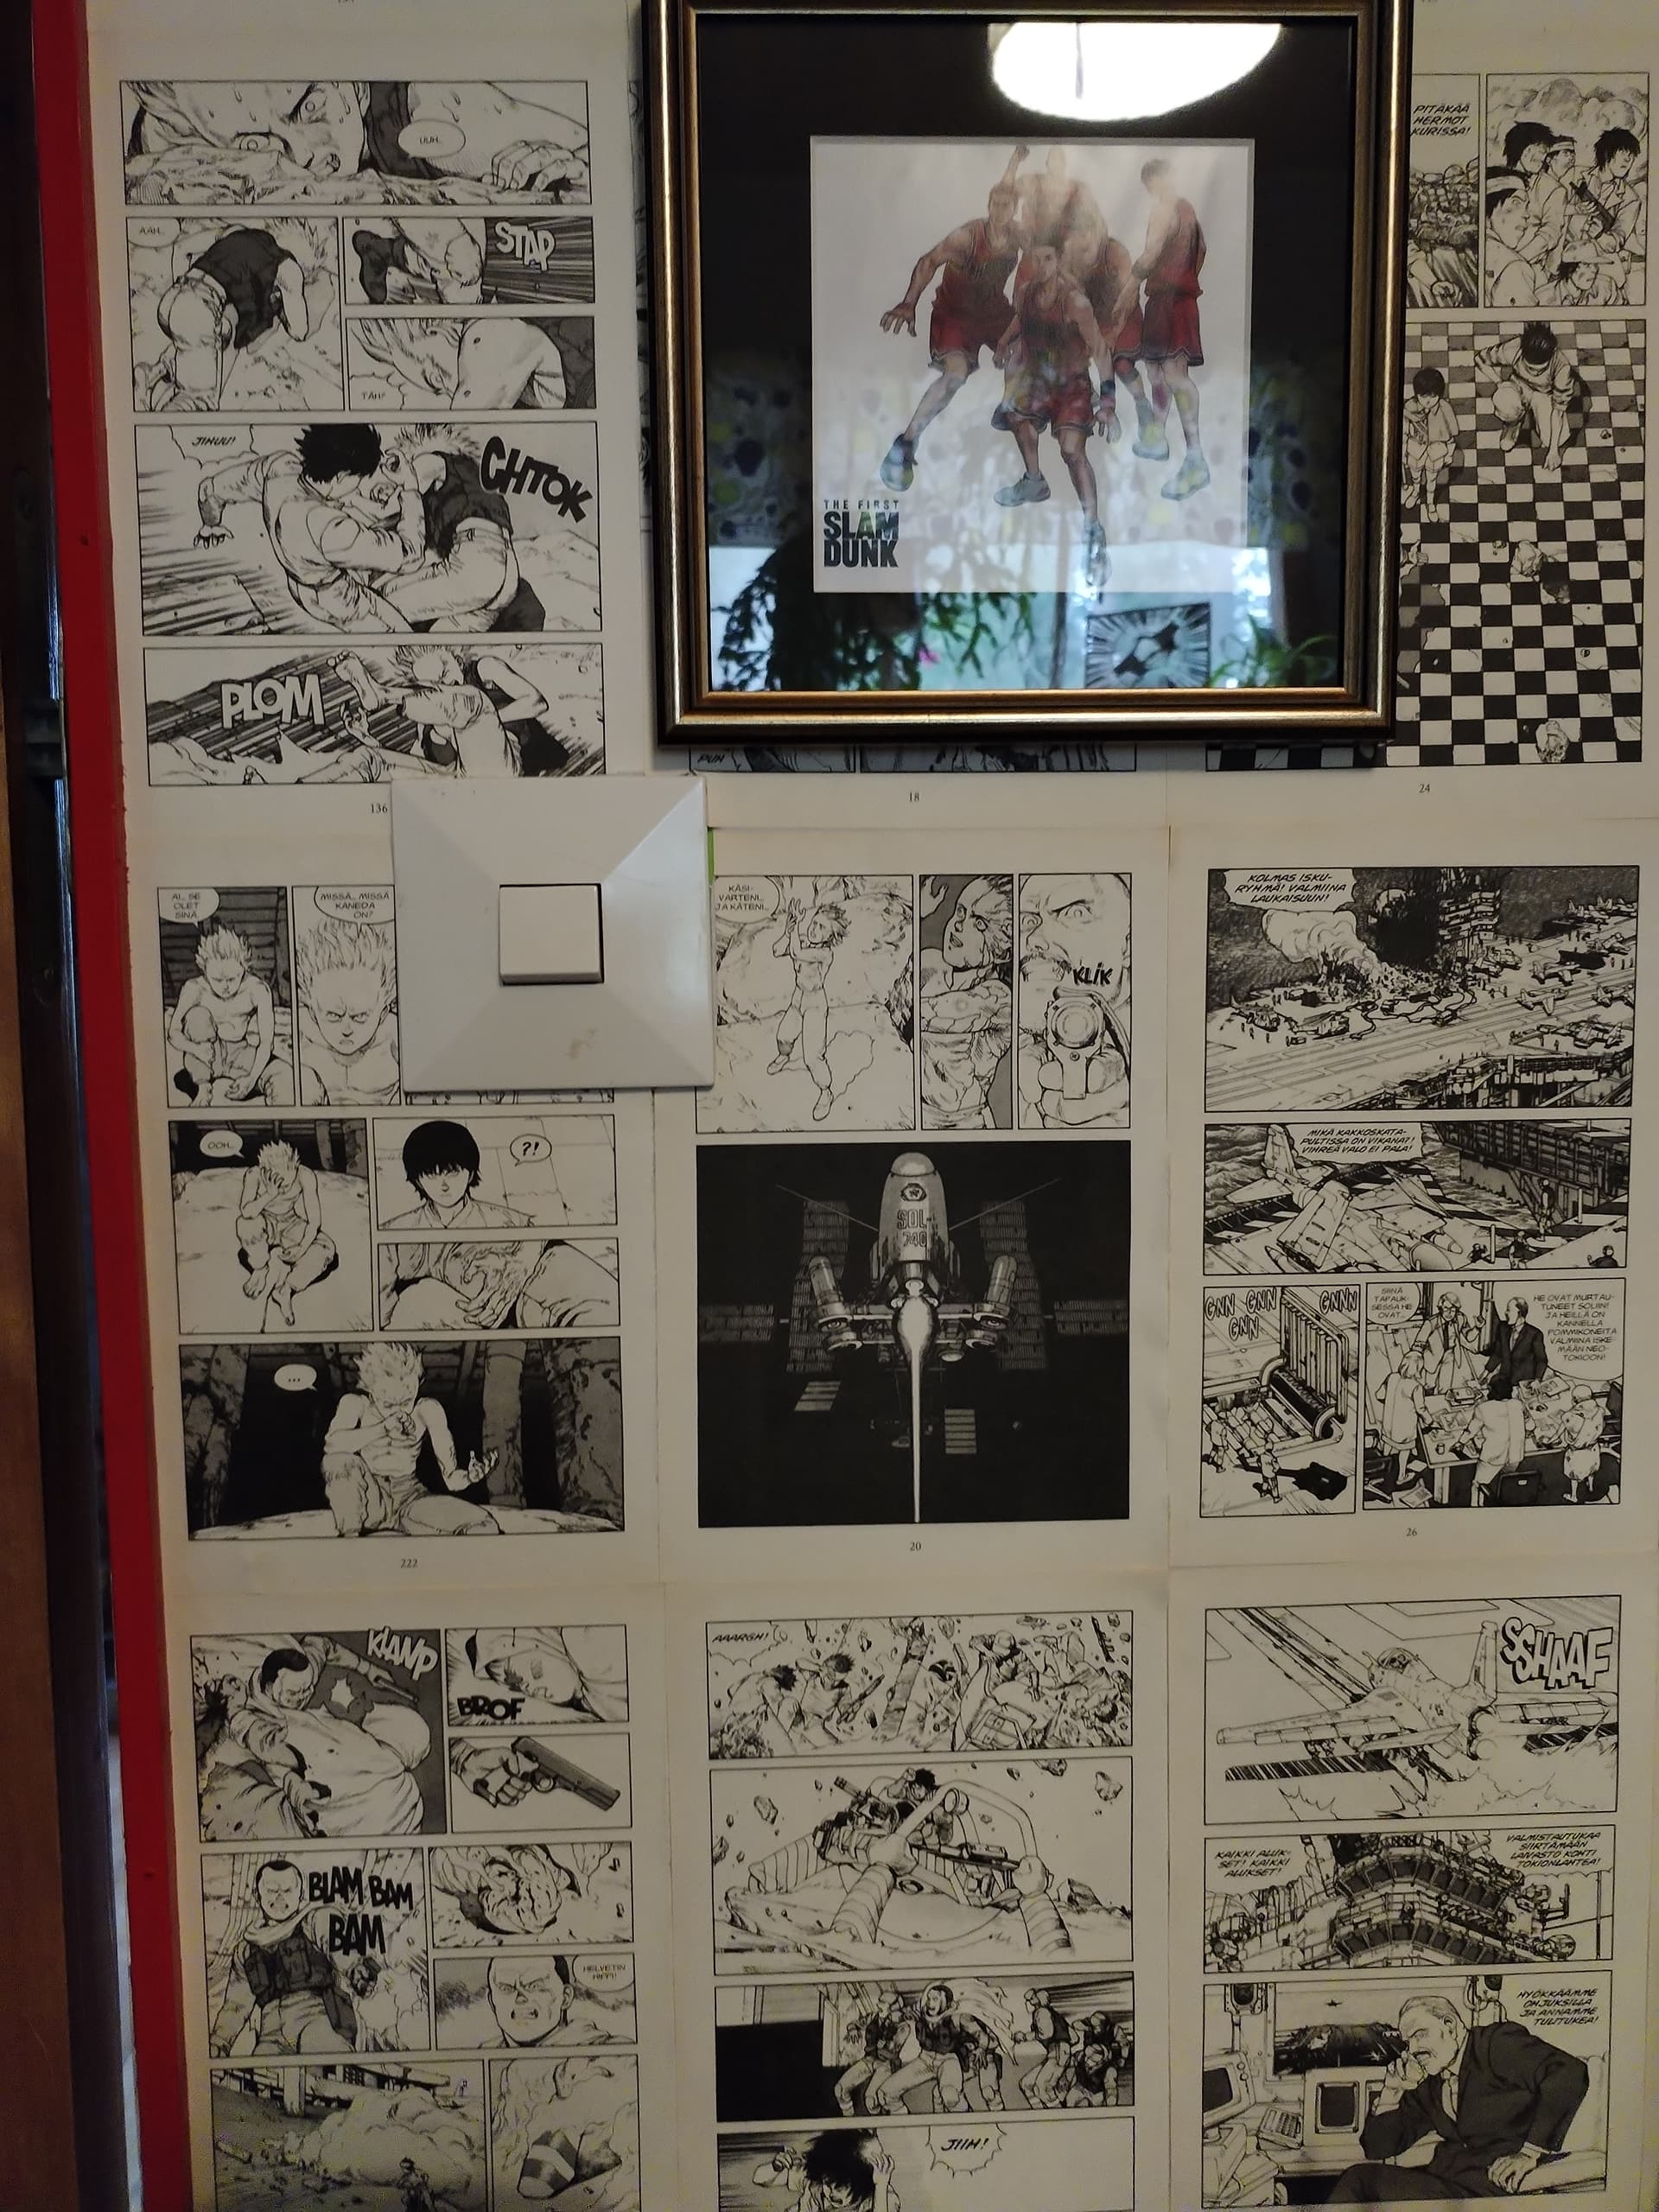
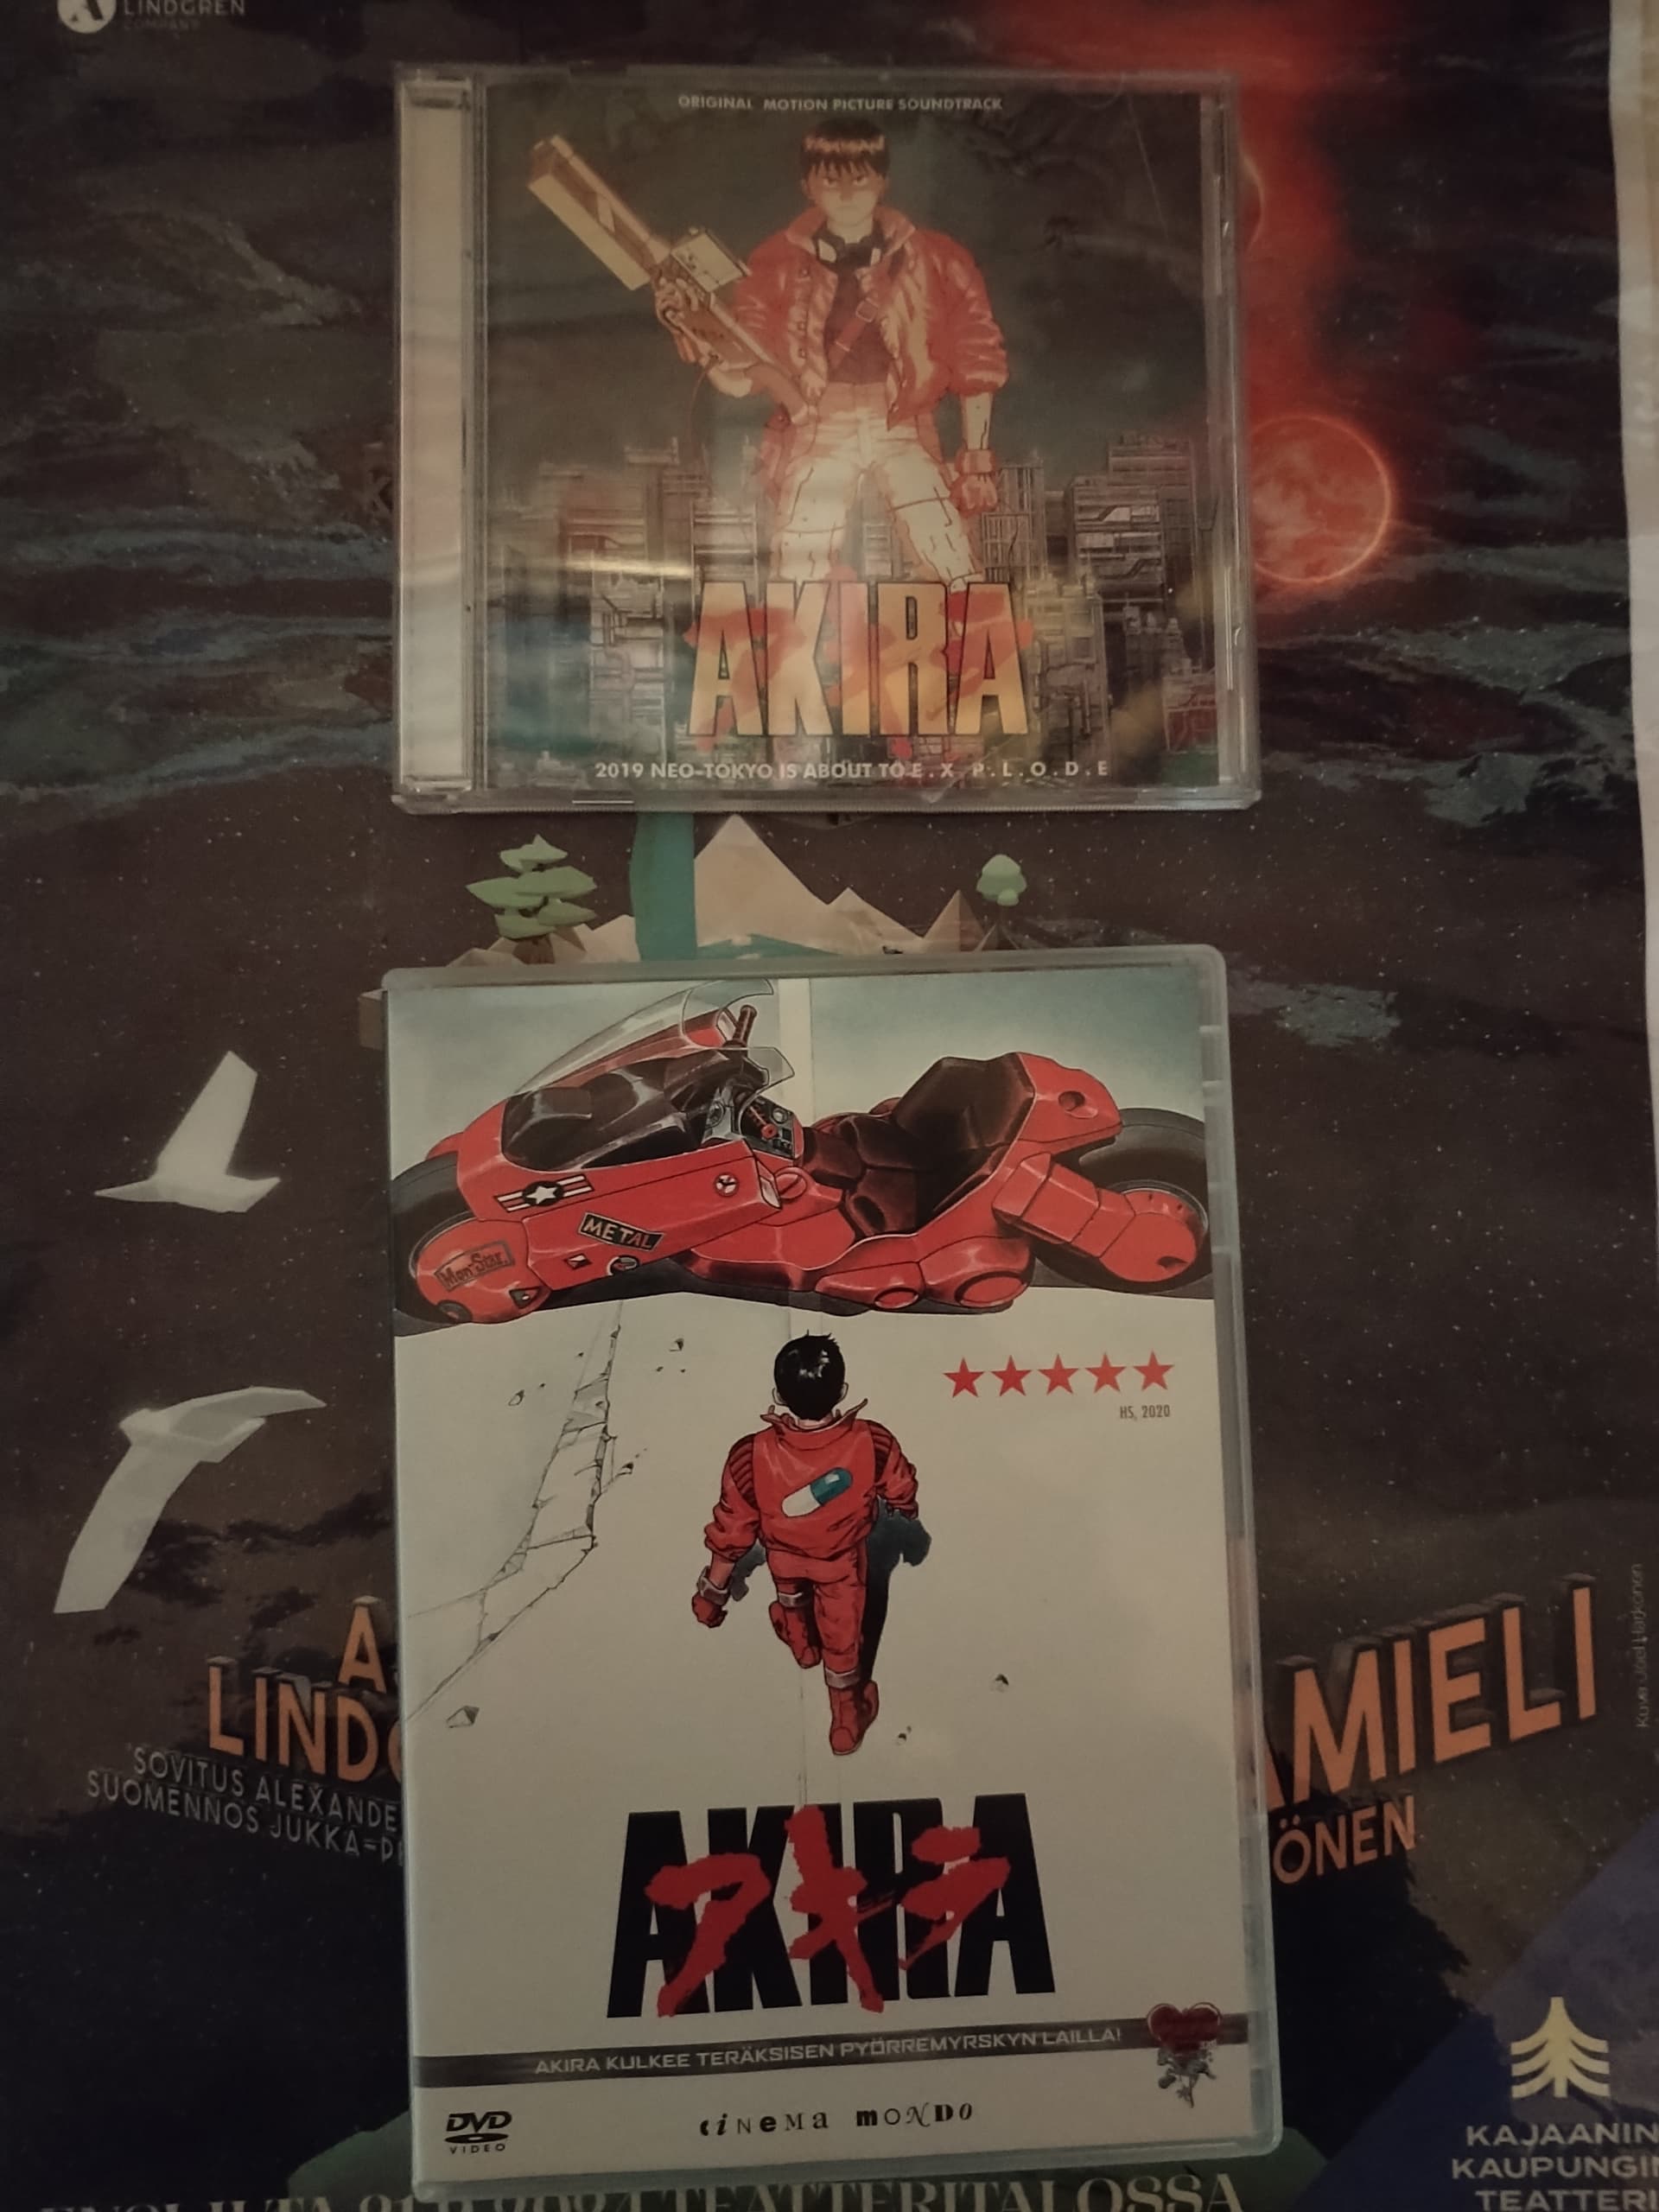
I also got the soundtrack to the Akira movie, which is a very mystical entity, but it also has a part that resembles music. The Akira DVD has been on my shelf for a very long time, but I only just now unwrapped it from its plastic. Somehow, this was such an impactful experience in the movie theater that I had been saving this DVD. It is still a startling viewing experience.
However, the manga is considerably more comprehensive. I read it after watching the movie. The dystopian world seems to have a lot of things relevant to today.
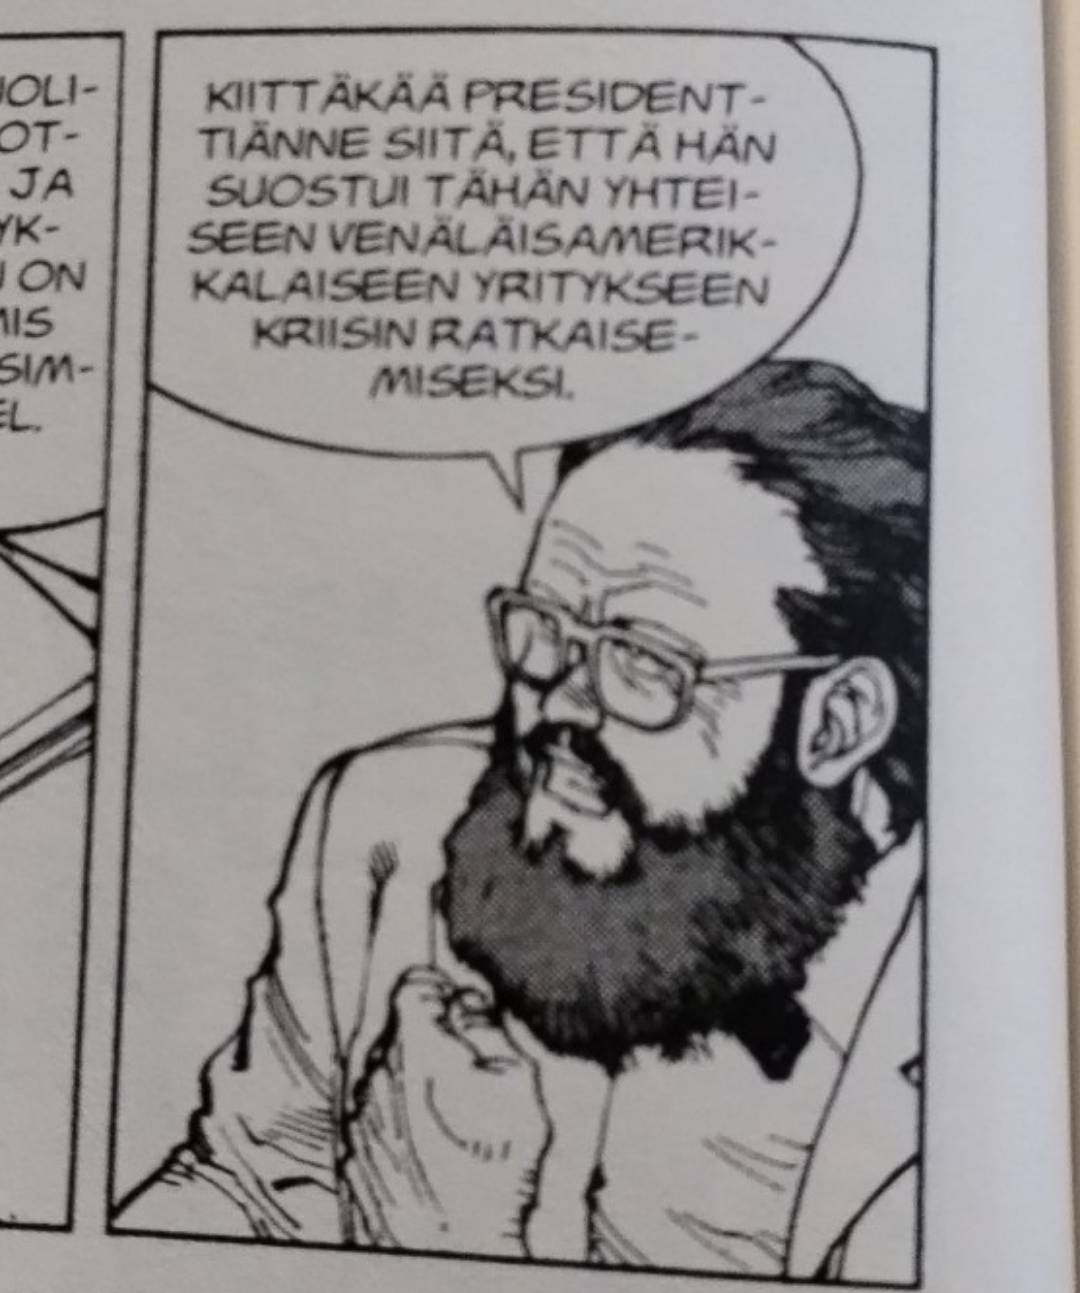
After a relatively long time, it’s nice to return to old things, and maybe find some new aspects in them.
Meme
35 Likes
Cash: ~33%
Puuilo: ~20%
Ålandsbanken: ~10%
Sampo: ~7%
World index: ~9%
Other funds: ~9%
In addition, half a dozen negligible amounts in different companies. It was good to calculate this. There’s too much cash, but I don’t want to buy unnecessary things just because it’s burning a hole in my pocket. The future is uncertain, and it’s nice to have chips for opportune moments. Puuilo and Ålandsbanken could also be added at suitable points. I like concentration.
15 Likes
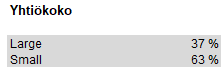
The portfolio has been diversified somewhat more, and free cash* accounts for one-fifth of the portfolio.
In direct stock investments and the Phoebus fund, I focus on quality investing, and with index funds, I address industry bias and geographical diversification.
I am currently considering what to do with the free cash. The next interesting day is a month away, when Berkshire’s annual meeting and Buffett’s over 4-hour Q&A session will take place. Perhaps I can get ideas from it on where things are heading and what to do.
I don’t intend to hold this much cash indefinitely; I have always had a large allocation to the market, and that has felt like a suitable strategy for me. But I can certainly wait a month (unless I make a small addition to Vaisala in the meantime).

Industry, Size, and Geographical Distributions:


*free cash = total cash - upcoming larger expenses - emergency fund
12 Likes
Funds in blue
Cash in yellow
Stocks in green
The weight of US stocks in the total is about 18-19%

19 Likes