In honor of today’s big news, I am opening the “Metso Outotec” thread. There didn’t seem to be a separate thread for either of them otherwise, and this combination is indeed a very significant and interesting player, e.g., in the mining industry, where the next investment boom is awaited after a long drier period.
I will recap the main points of the proposed deal here:
Metso Minerals and Outotec merge
The new company will be named “Metso Outotec”
Metso’s remaining business, Metso Flow Control, will become an independent listed company focusing on flow control. Its name will be Neles.
The merger is arranged so that Metso’s shareholders receive 4.3 new Outotec shares for each Metso share.
Metso’s owners would own the majority of the new company, 78 percent. In addition, Metso’s shareholders will retain their current Metso shares, which will become Neles shares.
I own both myself. I have been an owner in Metso for a long time, and Outotec is a more recent acquisition. Judging by Outotec’s share price reaction, the market considers this deal more attractive for Outotec’s owners compared to yesterday’s closing levels.
Metso has been a rather boring ownership for the past few years. The same cannot be said for Outotec, at least based on share price changes. Hopefully, the combination gains good momentum and positive drama is in store…
This is very good news for the owners. The companies were competitors in the Mining sector. This merger has been discussed behind the scenes for years, but the biggest obstacle has probably been Outotec’s poor financial performance. I don’t know the current situation, but apparently the merger is no longer restricting competition in a way that would be a problem for the authorities.
Metso Flow Control was already almost its own independent company within Metso, so separating it is very easy. Neles is also a very well-known brand globally, so choosing it as the company name was not a surprise either.
The merger makes Metso Outotec quite cyclical. Hopefully, the Mining sector will keep chugging along, otherwise there will be problems. The new company is unlikely to record the benefits of the merger before 2021, but costs, on the other hand, are on the horizon.
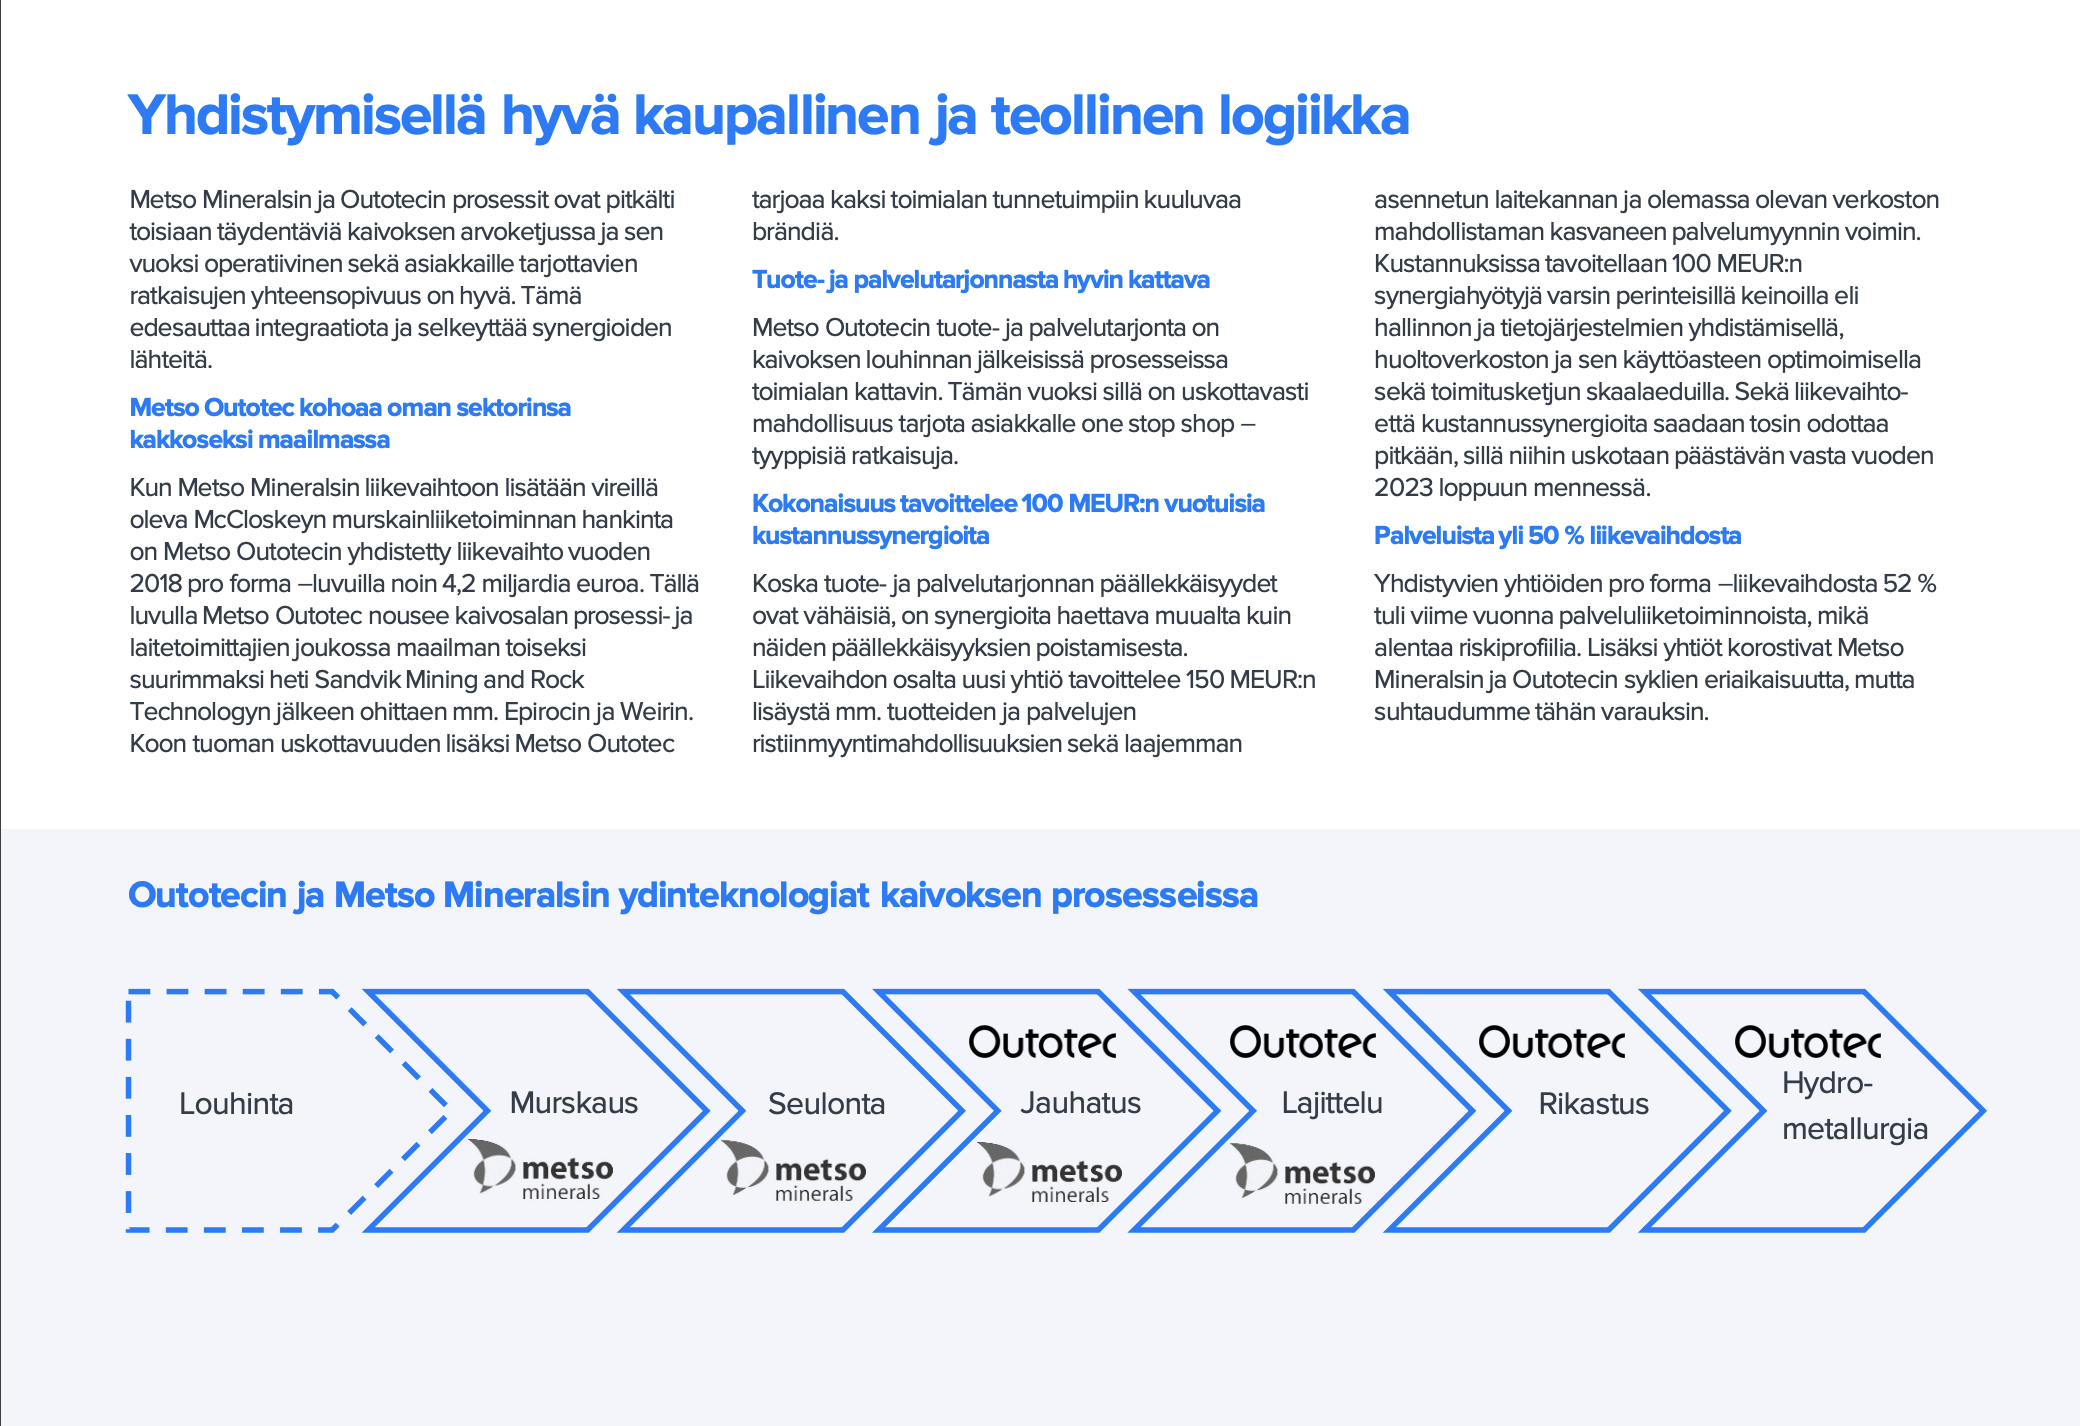
Of the 4 billion combined revenue, half would be service business (2018, Outotec 500m + Metso Minerals 1500m). One would think it wouldn’t be so cyclical?
Of Outotec’s Minerals Processing’s 700M revenue, half is service business. Operating profit for MP in 2018 was 10.4%, while Metso Minerals in 2018 was 10.3%. So Outotec’s MP is in OK profit condition.
Outotec’s remaining Metals, Energy, Water business, however, is dismal. 500m revenue and loss-making. Service business share approx. 150m.
This merger is good news in my opinion. If they could just make that Metals, Energy, Water profitable somehow. Or could they get rid of it?
Machine utilization affects maintenance needs, and maintenance needs decrease during a downturn. At the same time, competition intensifies and margins shrink.
For machine shops, machine maintenance services are largely independent of economic cycles. Elevator/escalator maintenance must be carried out at certain intervals, as far as I know, by law in many countries.
Exactly. So, there are many types of service businesses. Metso’s consumables and spare parts sales decline rapidly during a mining industry downturn, as the need for crusher wear parts and spare parts drops.
Have you calculated the premium for Outotec shares from this merger, and by what method?
I calculated with a simplified formula that the proposed share distribution would give Outotec shares a premium of approximately 30%. The market also confirmed this at opening, but since then Outotec’s 30% rise has fallen to 20%.
So, in others’ opinion, is this now a buying opportunity for Outotec shares, or do you disagree about the premium?
I look at the deal from the perspective that it won’t materialize until 2020, and there’s still considerable uncertainty regarding its realization (competitive landscape/EU). The share distribution naturally sets certain frameworks for the transaction and for price formation for both shares, but there’s still a long way to go until completion. So, many things can still happen in the business operations of both companies.
If one makes an investment decision based on this announcement, one must be prepared for a potential cooling of both share prices.
In addition, there’s always a big risk in these corporate mergers regarding how they practically succeed and how different corporate cultures “melt” into each other, both at the management and employee levels. The board’s perspective is quite far from this reality.
But this is an interesting scenario in the Finnish context.
Hesari wrote yesterday that (natural) sand is running out in the world. For example, China used more sand for construction in 2010-2014 than the USA did in the entire last century. Saharan sand is not suitable for concrete production because it is too smooth from wind erosion and does not make strong concrete. New ‘sand sources’ may be found in Greenland…
Metso’s crushing business was once called Mining and Construction, but in practice, the mining side has dictated how the business performs. The running out of sand is perhaps a bit dramatized, but crushing certainly produces excellent concrete raw material and exactly the size desired. I don’t know, but I assume that for demanding concrete qualities, crushed aggregate is already custom-made.
Crushing is certainly not very competitive in normal circumstances if ready-made sand is available from nearby areas. The depletion of sand would be another matter. For road and rail bases, the right kind of aggregate is, as I understand it, essential for the base to be sturdy.
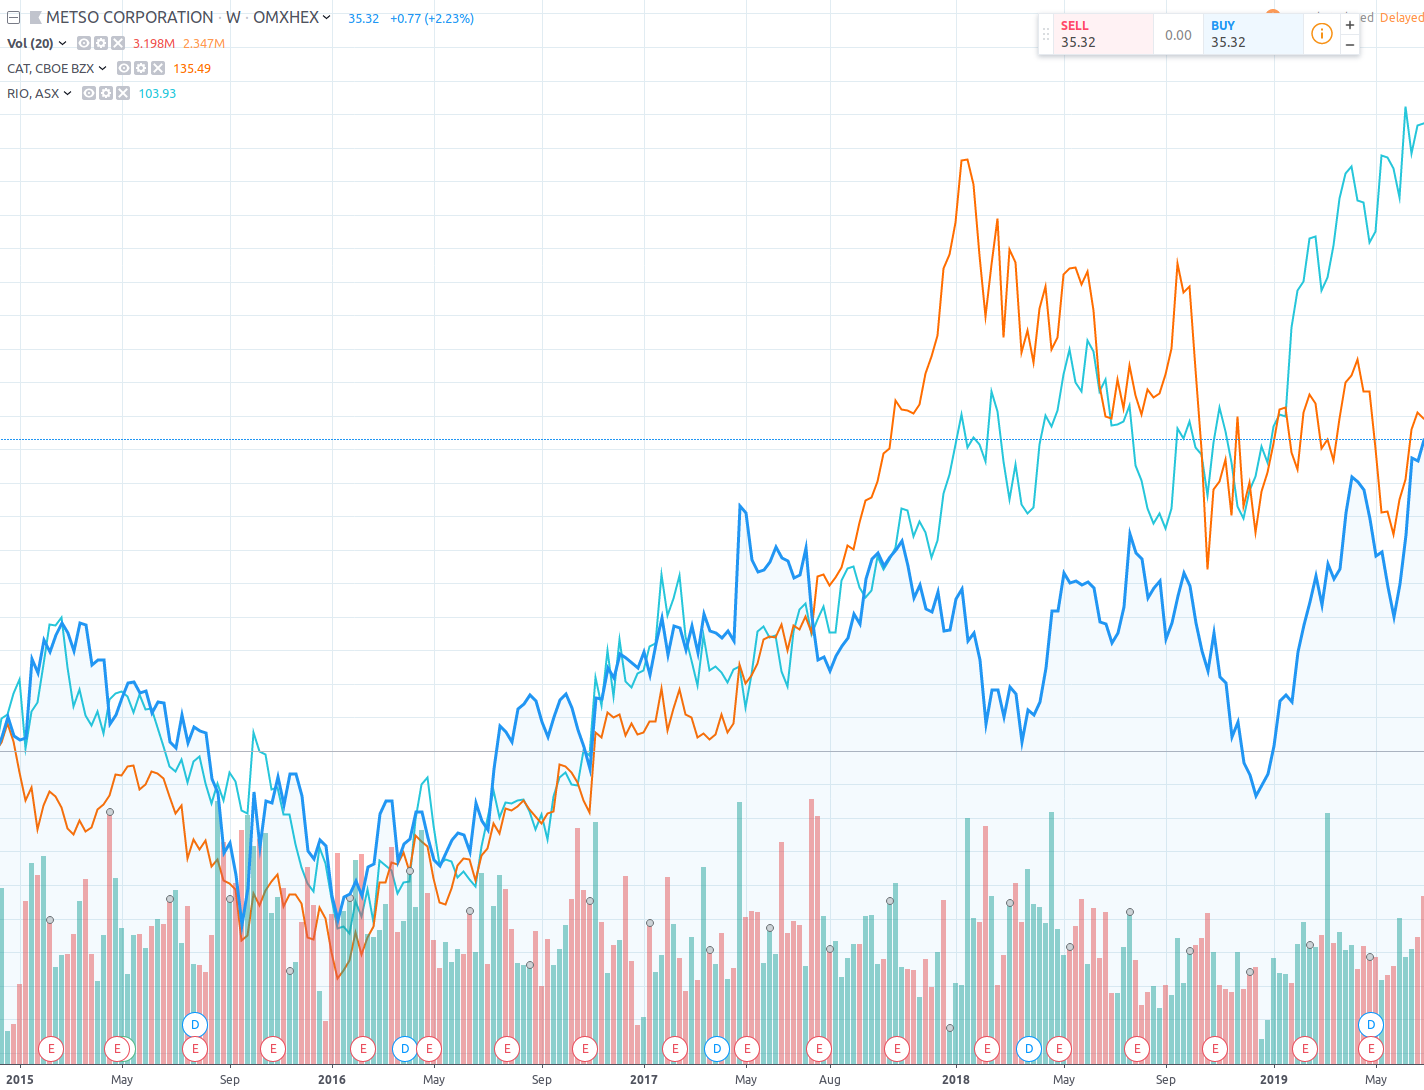
In my opinion, Metso is a very good long-term investment and is on my buy list when the price is right. Metso has been a blue chip for a long time, meaning it hasn’t made a loss in living memory. The accompanying image shows Metso, Rio Tinto (mining), and Caterpillar over a 5-year period. Both of these have always mirrored Metso’s development well. Metso is the lowest and Rio Tinto is the highest.
Caterpillar’s customers in the mining industry are largely the same as those of the upcoming Metso Outotec, although the products differ. Rio Tinto’s stock curve accurately depicts the situation in the mining industry, which I expect to weaken. Raw material prices critically affect all three of these. Global trade disruptions can still fluctuate strongly in either direction. A year from now, Metso Outotec will no longer have the less cyclical Neles valve business balancing it – that worries me a bit. But if you buy now, you get it as a bonus.
“The facility’s hundreds of control valves (officially known as ESDs; or emergency shutdown devices), which regulated the flow of chemicals to the labyrinth of distillation columns, fractionation towers, cracking units, and blending and storage tanks, were virtually invulnerable, having been recently refitted with something called a Neles ValvGuard system, which was, in turn, regulated from the refinery’s control center, which from their earlier reconnaissance trips they knew was below ground and heavily fortified.”
Arrowstreet Capital has reduced its short positions in Outotec as follows:
29.8.2019 0.91 net short position, %
16.9.2019 0.77
27.9.2019 0.69
There was nothing concerning in Outotec’s conference call for analysts. They reported that demand in the mining sector has improved, especially in concentrators and hydrometallurgy (Outotec’s strong areas). Large orders in Saudi Arabia, Ma’aden, and Russia, Baikal Mining, will soon be reflected in revenue and profit (Q4/19, Q1-Q2/20?). The problems with ilmenite furnaces have played too large a role in recent news, and appropriate provisions have been made.
The merger of Metso and Outotec is also not that far off anymore (spring 2020), and a new strong company will begin. Yo_Gong’s PowerPoint earlier in the thread describes well what the new company will be.
Yeah, a match made in heaven.
Handelsbanken gave a buy recommendation for both.
Most recommend buying Outotec, but HB also praised Neles in addition to Metso. Reportedly, the products are in good condition and they estimate that it will attract foreign investors. Inde seems to be more of the opinion that Neles’ price will remain too high: “Metso’s stock is expensive by traditional metrics, and the calculated valuation of Neles, to be listed separately in the Metso Outotec merger, is on the high side.” Inde is known to be very strict in its recommendations.
Based on these announcement dates (trades made the previous day), the shorting of Arrow Street has clearly failed badly, so these can mostly be interpreted as them being forced to close due to failure. Since they haven’t been able (or weren’t able?) to close all of them quickly enough, it’s possible that they are banking on a recession and keeping them open. These could also be due to derivatives.
Now, old good Metso is starting to be seen in the stock movements. The merger significantly complicates the timing of a potential purchase, even though Outotec still seems to be holding on. €28 is the limit for the first purchase batch of Metso. If the oscillator has now started, I might lower the limit further. However, I guess I will become a Metso owner again within a few months.