I also considered the option that if Metso were to lower its prices, I would buy the next batch of Outotec shares through them, because Neles interests me. Neles seems to be a highly valued company that produces quality products. The risk here is probably that the merger would not happen or would be delayed.
1 Like
Somehow I’ve understood that the risk of the competition authority intervening in the deal is very small. And on the other hand, the companies will do well on their own, and neither company’s share price is unreasonable even after the announcement of the merger intentions.
2 Likes
I also see a risk that Neles will be valued too high in euros if the merger happens. I took the easy way out and didn’t bother to mess around. I just bought Outotec.
2 Likes
That’s what other smart people are saying too. I can’t really estimate the value of any company, so I just try to deduce something from the current share price and the given distribution ratios. With Outotec being closer to 5€, a lot of value is left for Neles. Whether that’s too much or too little, I can’t say. Maybe I should look at how comparable companies are priced around the world and compare it to that?
What if you buy Neles when it’s its own share on the stock exchange, so you don’t have to speculate with Metso?
3 Likes
Neles has been a very consistently profitable part of Metso, and there’s no reason to doubt why Neles wouldn’t continue to be so in the future. Metso’s Minerals and Outotec, however, largely move according to the cycles of the mining industry. Now there are big risks in China, and mining companies have already significantly declined as the China risk increases. Recovery might have to wait a while.
Addition:
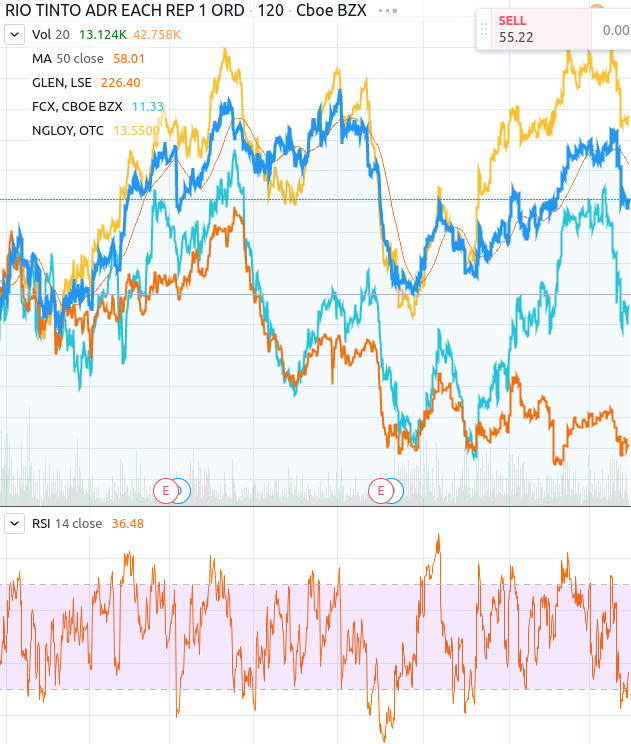
Out of curiosity, I looked at the stock movements of a few large mining companies (Glencore, Anglo American, Freeport MCM, Rio Tinto). One can pretty clearly see the significance of China. However, many of these seem to be oversold right now.
3 Likes
Well, the market price of the raw material being mined certainly affects the situation for mining companies, and those prices have been quite low for many for a long time.
3 Likes
Fear of weakening demand and thus falling prices, as DaytraderXL noted.
The same phenomenon is seen in oil prices. However, it is easier to regulate with OPEC decisions (production restrictions) than metals.
1 Like
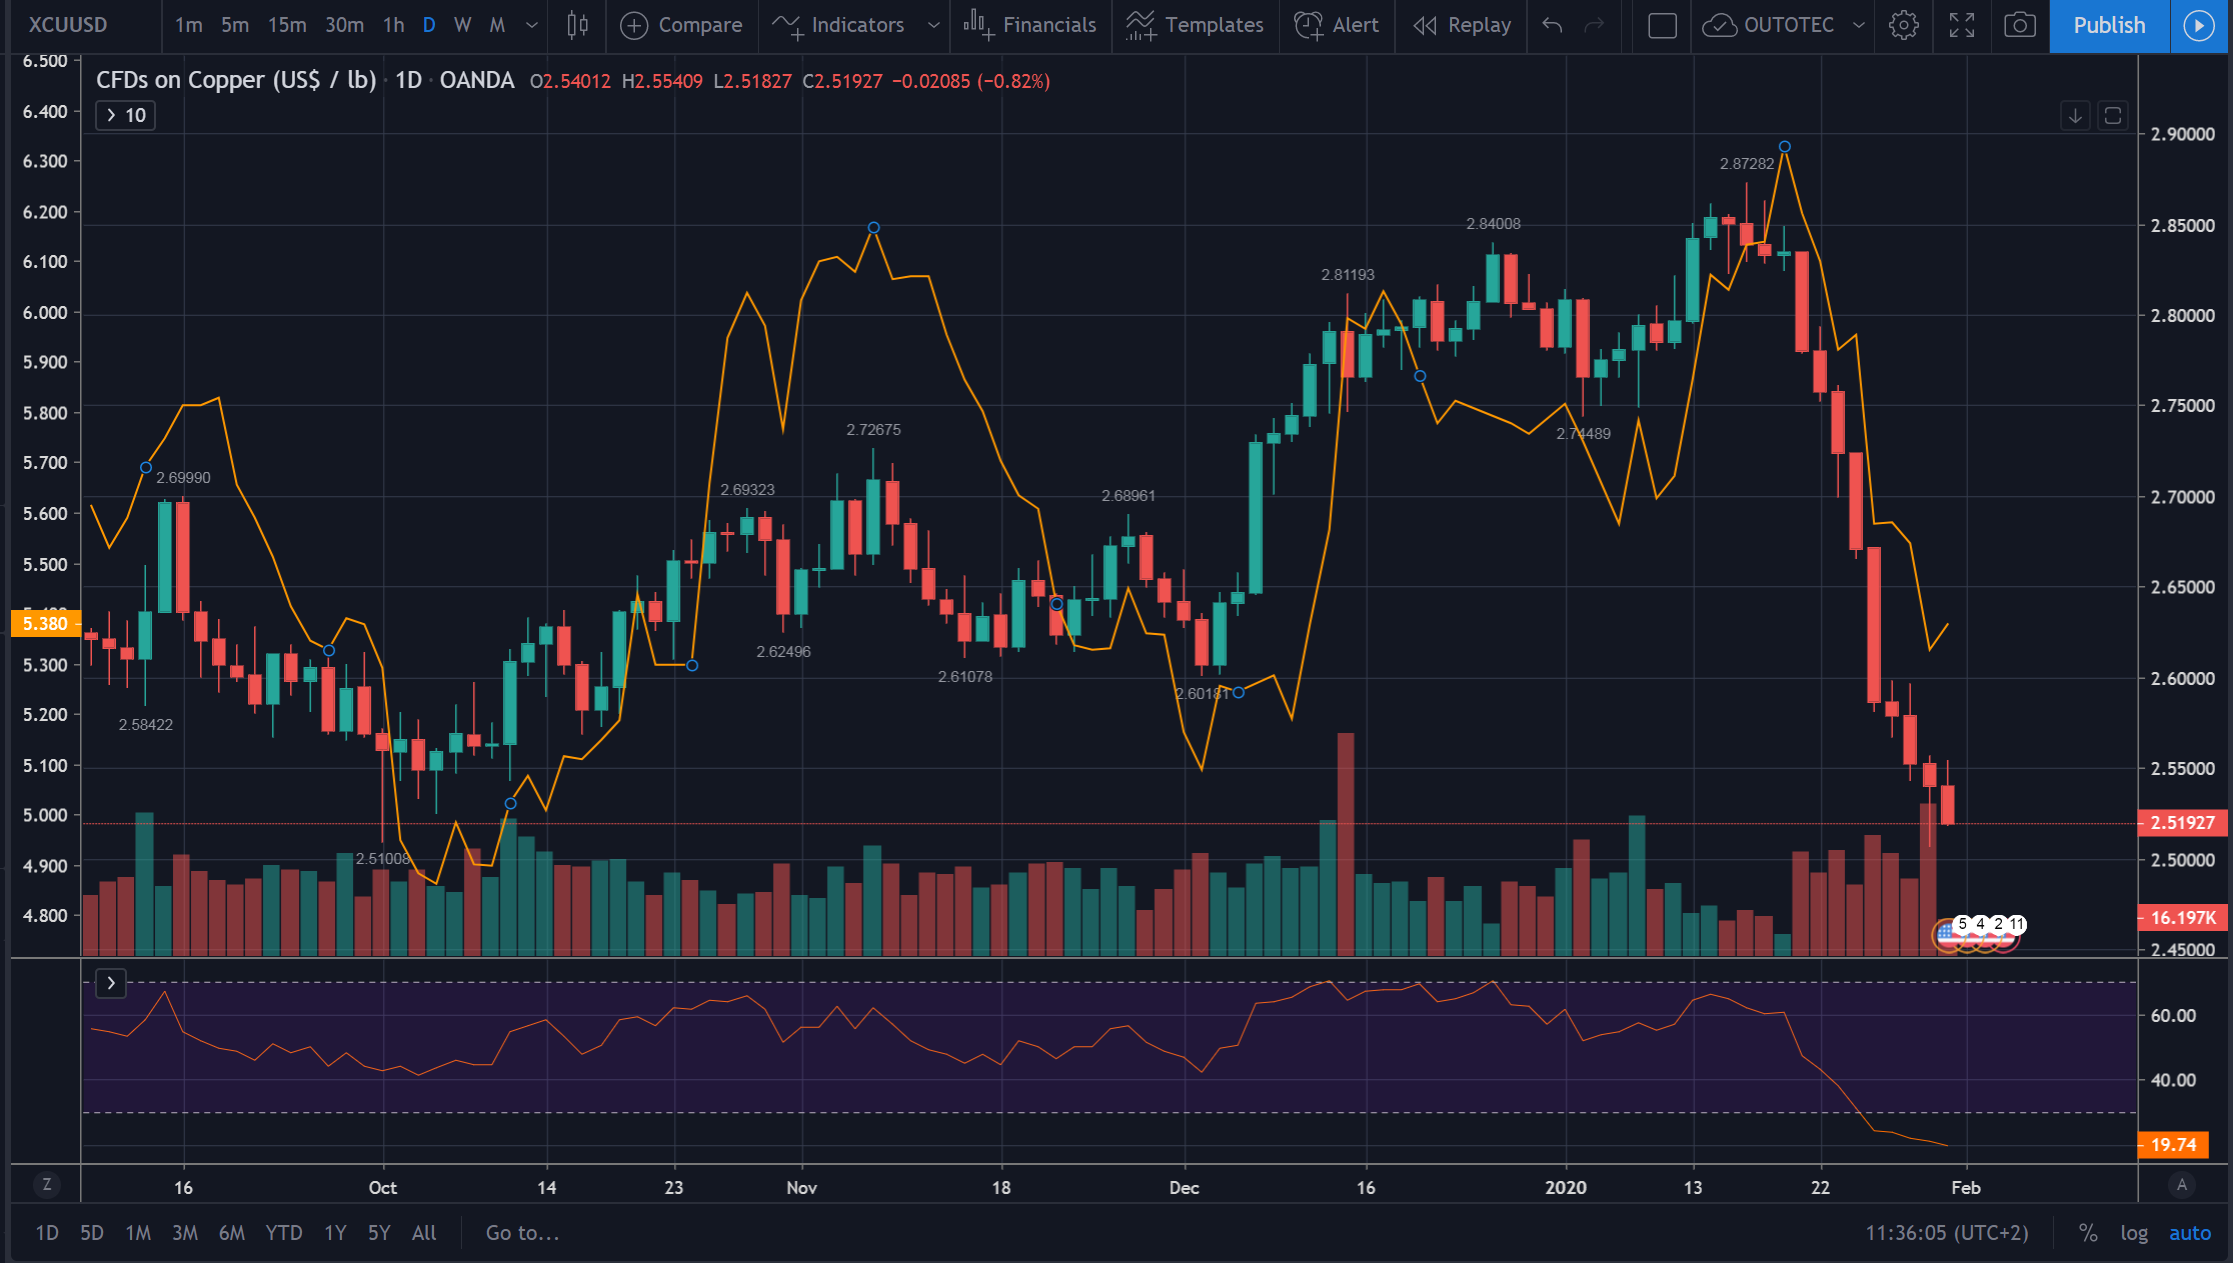
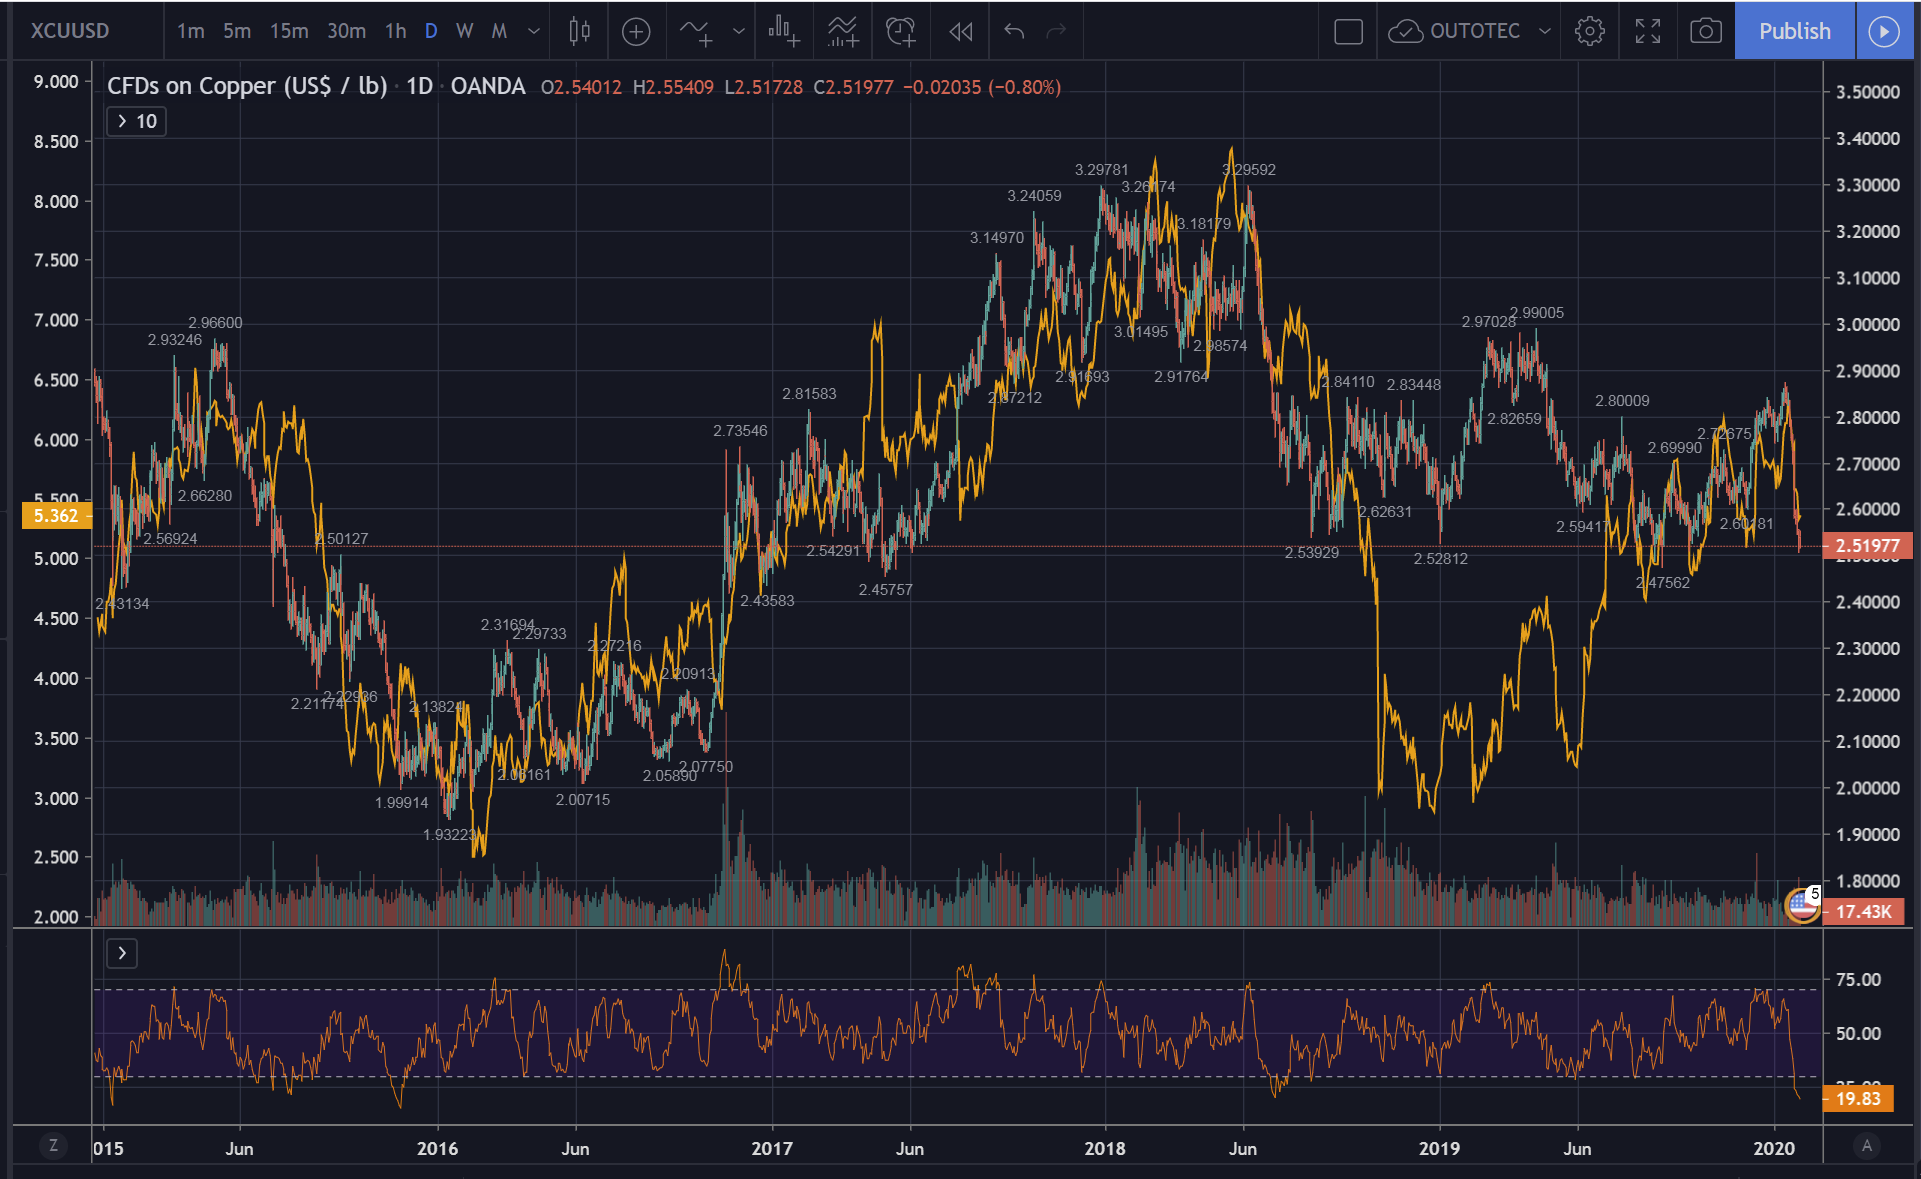
Here’s copper as an example, which I also follow in Outotec trades. There’s correlation, but is it always rational… Psychology has a big impact.
4 Likes
Outotec’s customers probably mine significant amounts of copper, which accounts for most of their revenue. China, in turn, is a large consumer of mining industry products, such as copper (Is it even the world’s largest?). The demand for new enrichment capacity and the maintenance and renewal of existing capacity may weaken in a prolonged nationwide shutdown. But, psychology seems to be driving the market at the moment. China also has a lot of mining and chemical industry, where Outotec’s equipment should also be strongly involved. When machines don’t run, spare parts don’t wear out either.
2 Likes
I’ll add to that. If, for example, you believe the situation is getting darker day by day, the virus will rage for the next months/years, the current situation is permanent, headlines and social media and YouTube news negatively affect your life, you believe the mining industry will collapse, the current trend will reverse, China will enter a recession, China’s industry will remain closed for a long time, and, for example, copper demand will fall to 2-3 year lows, and you don’t believe prices will recover quickly, then you should consider selling Outotec. If, on the other hand, you believe in containing the virus in a reasonable time, stock market mass psychology, speculation, trend persistence, technical analysis and, for example, support levels, the benefits of the Metso/Outotec merger, changing analyst target prices, you invest/trade for a slightly longer term, you believe in corrective moves, and you don’t panic easily, then I might stay with Outotec for a while longer. The stock market world is full of stimuli, scattered correlated information, their combination and guesswork.
Copper price development. The yellow curve is Outotec, larger deviations are usually related to news or a failed project.
13 Likes
Good summary 
1 Like
Excellent summary of more than just Outotec.
On another note. I previously claimed that the only thing that makes Outotec attractive is Metso, referring of course to the merger in the spring. Here are a few reasons for my claim:
Outotec:
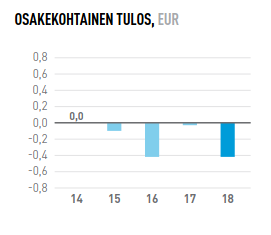
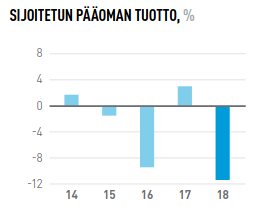
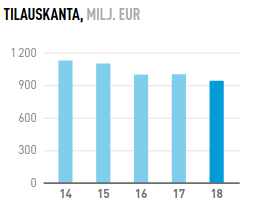
Metso’s numbers are better and Metso is expensive. 
5 Likes
Yeah, Tecci is starting to be at a buying price again. My previous trade was 5.2€ - 6.2€.
4 Likes
It’s worth remembering about last year’s EPS that there was a 100 million euro provision for the smelter project. The 2019 result is clearly positive (the forecast was apparently 0.45 euros).
1 Like
Now I can finally say that luckily I didn’t read the financial statement; I probably wouldn’t have dared to buy a single share 
The purchase decision was based entirely on having heard positive comments about this upcoming “Metsotec” merger. And not just from the grapevine. Nel has been highly praised. Someone even said it will become another Kone-like company. We’ll see.
4 Likes
True. Outotec hasn’t received any large orders in a while. I guess that might also affect the stock price.
It’s interesting that Neles, and actually Metso as a stock and company, have been trashed in various miserable media (there aren’t many good ones), even though its results from last year are staggering. Margins are top-notch, turnover is growing like clockwork, and there’s a huge amount of grumbling from various parties about Neles.
I, on the other hand, firmly believe that this is the diamond of this topic and that it will be a great long-term case, not to mention that with the spin-off, the probability of it being delisted means we could only guess the date and who would buy it out.
4 Likes
Outotec’s order book at the end of Q3 was at its highest in five years, €1.23 billion. This should promise a good year for 2020.
6 Likes
I think I’ll move to the buying side tomorrow 