According to a rumor from Hevosmiehen Uutistoimisto, Andritz might be interested in acquiring Neles?
As someone who worked at Metso for several years a while back, my memory from that time is that Neles was doing extremely well. Business was booming regardless of economic cycles, and that’s how it is – if you want to keep a process plant running, the valves have to work. Of course, there are plenty of competitors in the valve market, with all sorts of suppliers and valves available for different processes.
I’ve been wrong with Metso before, but I don’t believe these horsemen. Based on what I’ve heard, Neles is fully ready to be an independent listed company, and as you mentioned, it has been a consistently profitable part of Metso year after year. I was recently told that international competition in valves is different from many other industries. Especially in the oil refining industry, people are reportedly not willing to trust a Chinese copy, because trust in a valve must be 100%. This partly explains why valve manufacturing still exists close to the Helsinki metropolitan area.
Andritz, on the other hand, is a competitor of Valmet, and Metso (Neles) is Valmet’s preferred supplier of valves. Valmet was still part of Metso about five years ago. Perhaps Valmet would be more interested in buying. Who knows.
I would also add that the owners surely believe they will get a better return if Neles at least starts as an independent listed company. I believe the same, although I am not and will not become an owner at these prices.
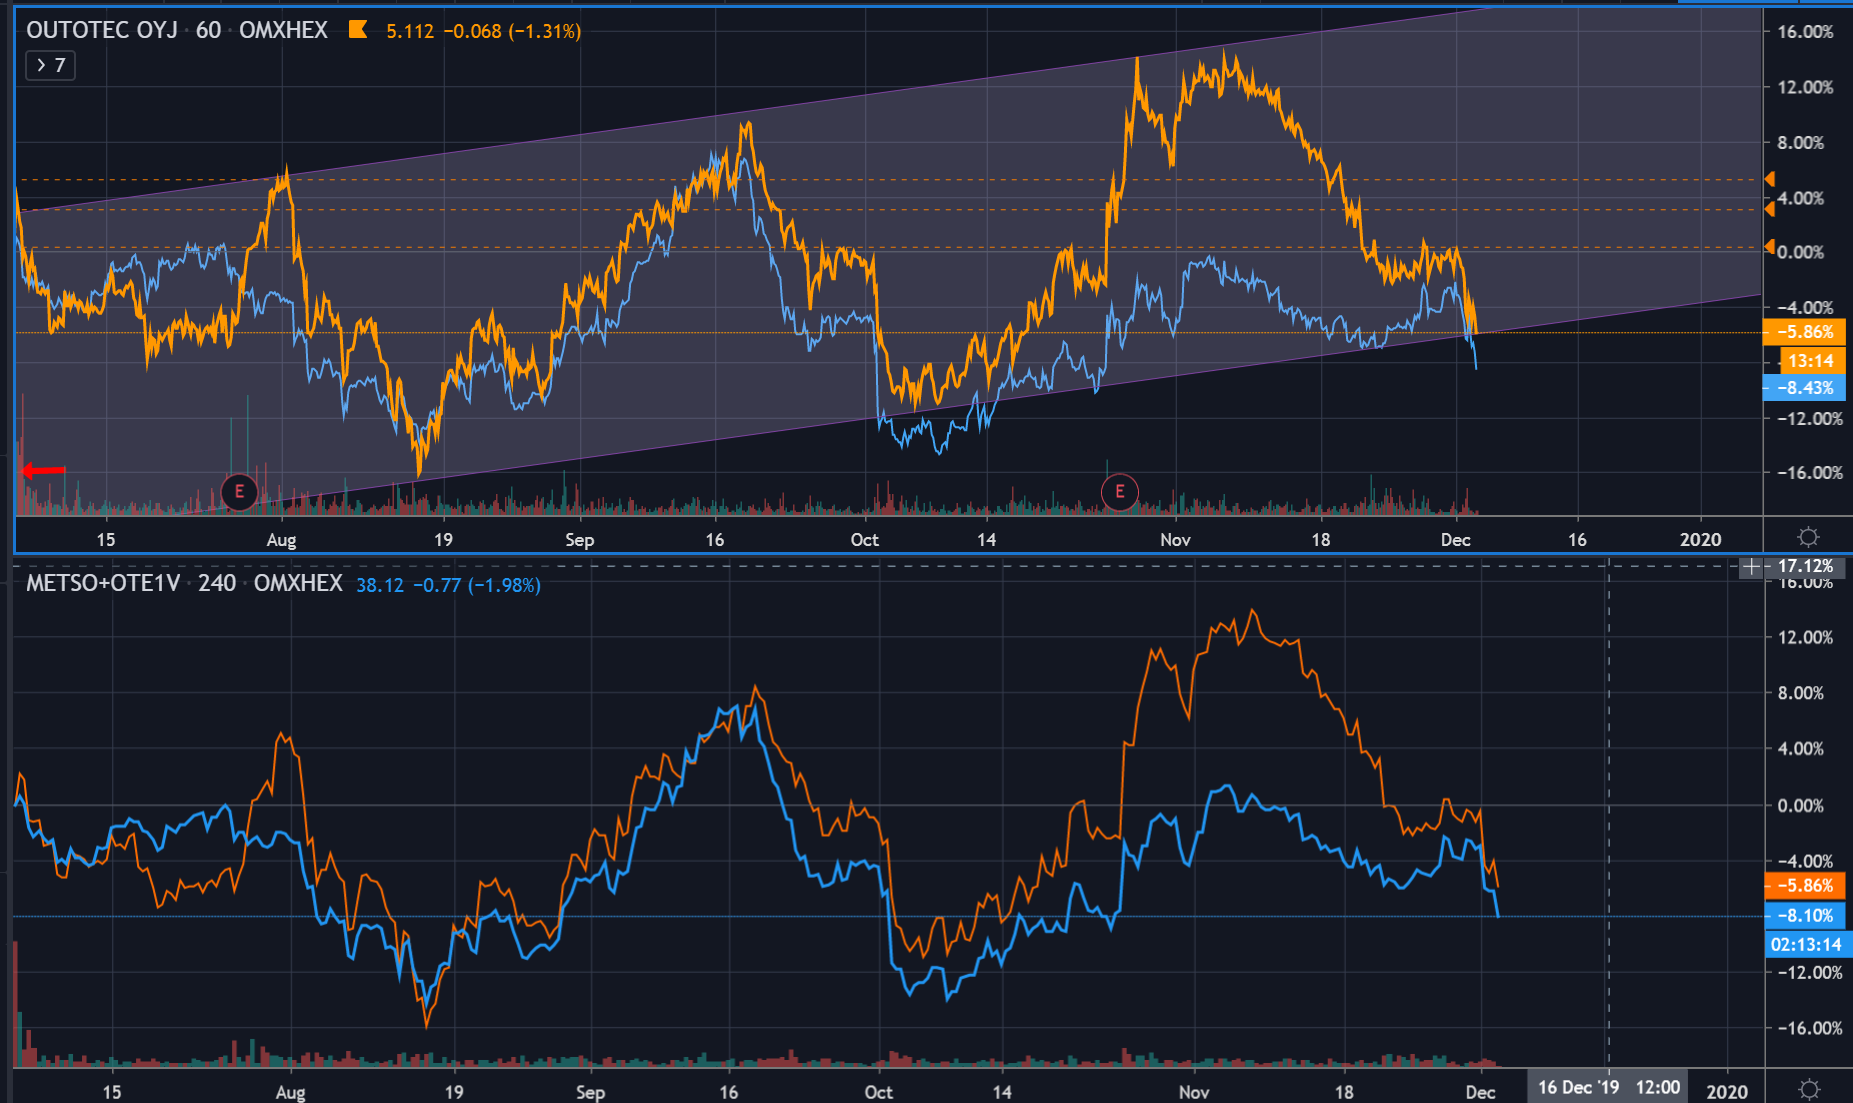
The interesting situation in Outotec and Metso shares continues. Outotec shares, which enjoy cyclical trends, have been declining for several weeks, and correction moves in the US markets began yesterday. Markets are volatile, and the low-volume Outotec is at the bottom of an emerging sine wave.
The independent Neles is now valued at 33.20% of Metso and €10.96/share. Distribution ratios and my own calculations would suggest a lower value for Neles, and thus Outotec presents itself as a better partner if one even wants to own Metsotec. Metso’s share price should therefore still fall and Outotec’s rise, or both should fall at different rates, or both rise, but not by the same amount. The disproportionate couple and their quality valve-producing offspring will continue to bring numerous opportunities and will certainly guarantee excitement in the short and medium term at least until spring. I bought Outotec again.
We’re used to surprises, e.g., 100m reservations 5min before a release
Well, it’s a good thing that bad businesses are being shut down if they simply can’t be fixed and the owners are paying. I already hinted at this a bit in the summer. Are we approaching 10% adjusted EBIT at the group level already this year?
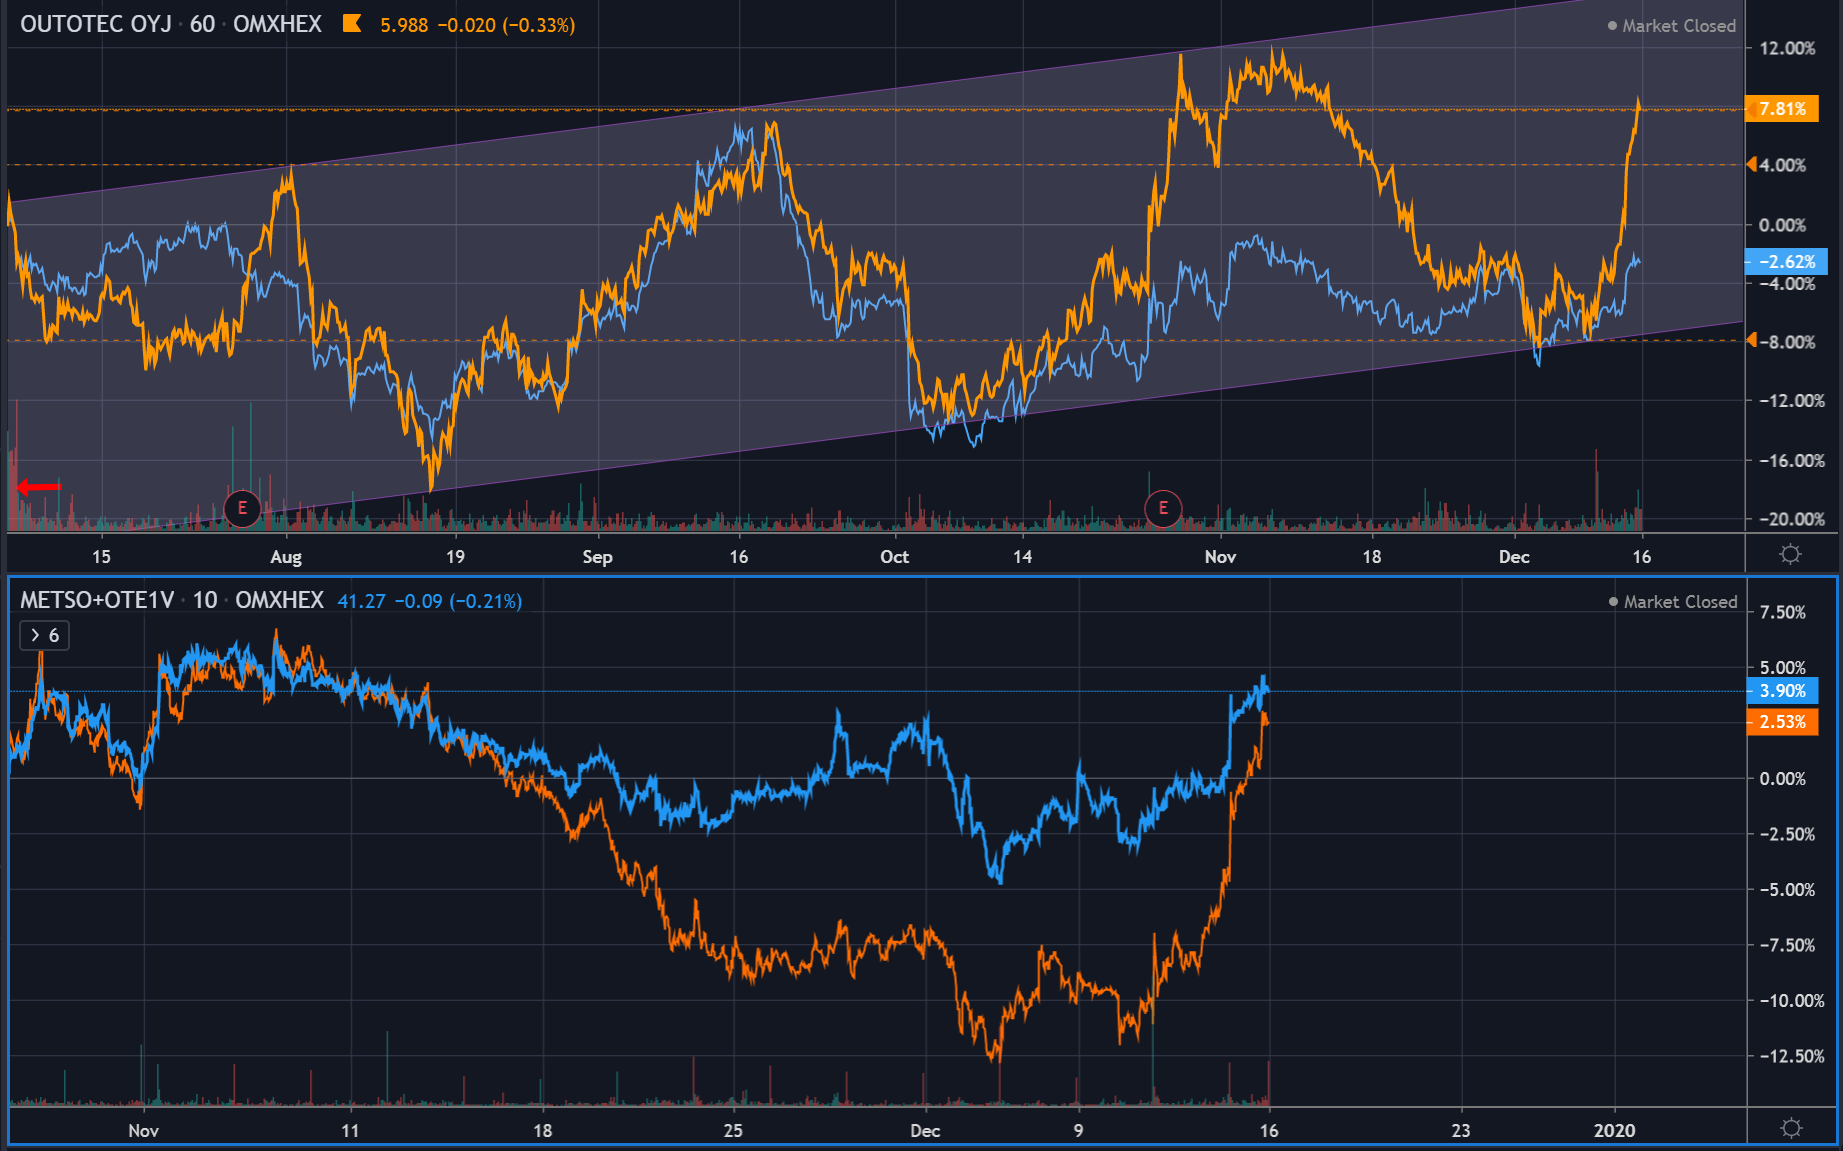
The excitement was short-lived as Outotec’s valuation error evaporated in an instant. Last week’s sudden big price increase was, in my opinion, justified, or probably as justified as the steady dive that preceded it for weeks. I sold the last remnants of the trade batch acquired on 3.12. and this week @5,100-5,272 prices on Friday 13.12. @5,980 and lightened up on the way up. The rise came too quickly, and I haven’t particularly enjoyed or benefited from potential surprise tweets on weekends this year. For a change, I stuck to the plan, and about a +17% price increase was enough, especially since the machines harnessed by traders seem to churn out half of the trades. Cyclical stocks acquired partly with a trading mindset and a certain profit target can also be tough to own in the long run, especially if the self-fulfilling recession prediction painted by news headlines and charts materializes in autumn 2020 or even earlier. I’m not paying nearly as much in taxes this year as I would have liked.
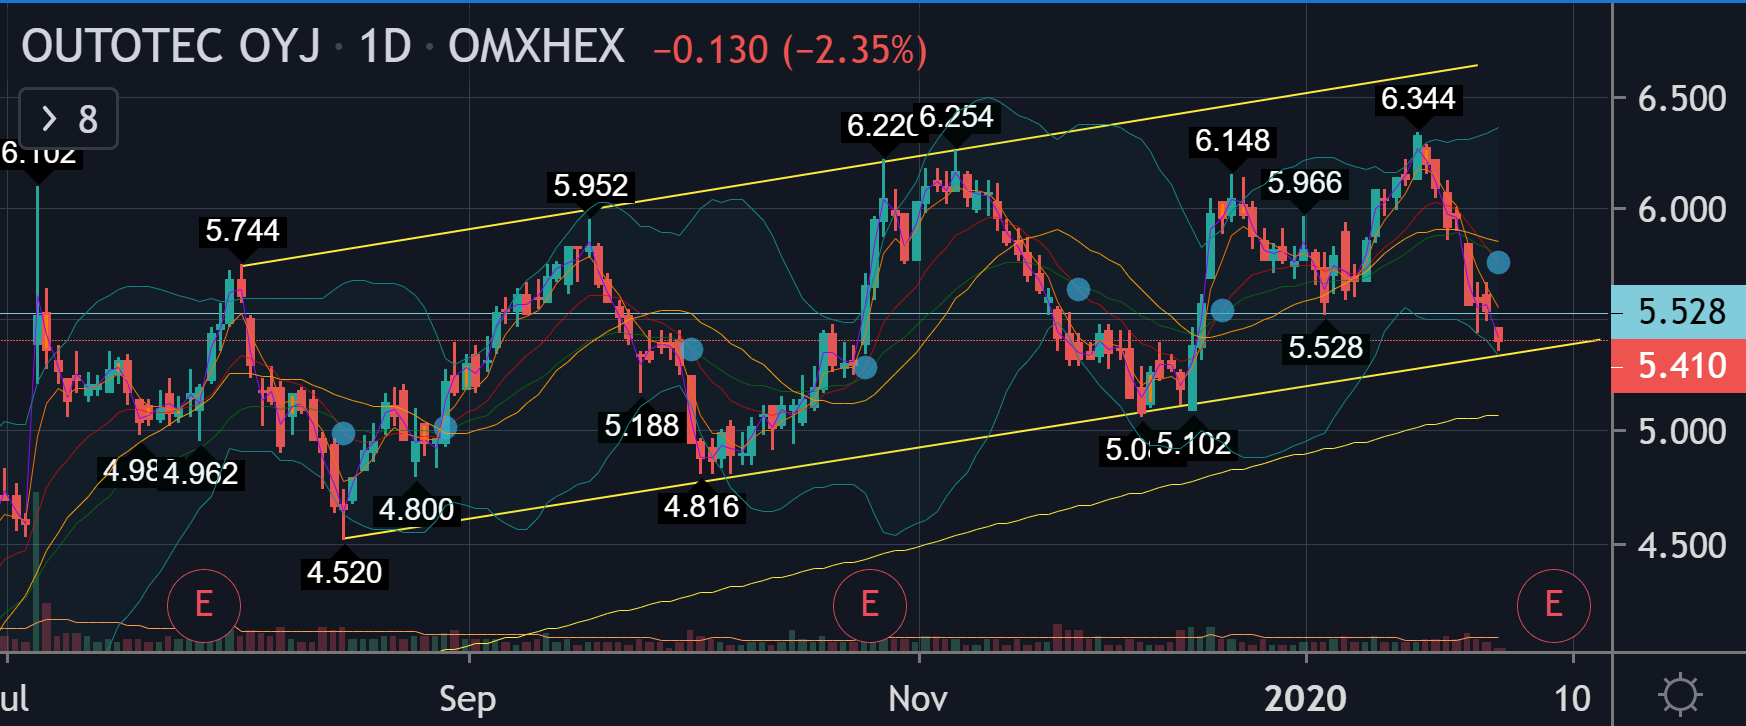
Neles’ value is currently 27.02% of Metso’s price, or €9.53/share. The shares are almost reasonably priced relative to each other. I still see Outotec as a better option because I rarely want to buy two shares with one click. If Outotec’s valuation hits mysterious bottoms, I’ll return to the buy side. It’s also nice to buy temporarily oversold stocks in a longer-term rising trend. Technical analysis for Outotec is a bit difficult to utilize on a daily basis, but the short-term Parallel Channel that started with the merger news is even suspiciously clear.
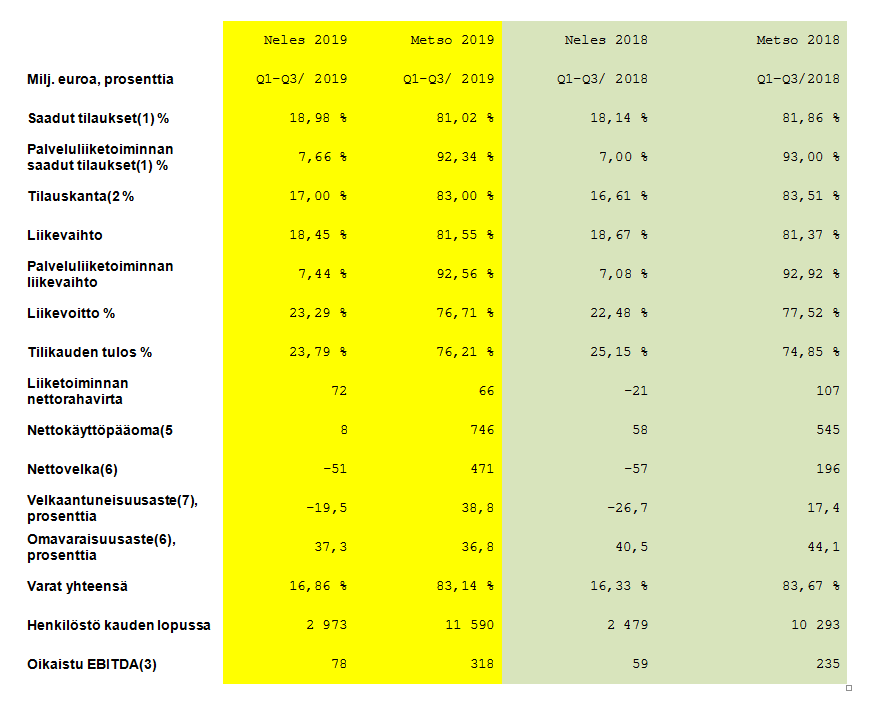
The service business’s share of Metsotec’s future revenue is at a respectable level of approximately 55-58% and appears to be still growing (Neles about 21.5-22%). The magnitude of future synergies and the time it will take to achieve them are still challenging to estimate, but surely the benefit will ultimately be quite significant. The divestment news was presumably good in the long run but too challenging for me as a nine-minute mental math problem.
From a “stock exchange technicality” standpoint, doesn’t Metso’s partial demerger mean that Outotec becomes Metso Outotec and the “remaining” Metso becomes Neles…?
Hi Teisho, here’s how it goes: Metso shareholders will receive 4.3 Outotec shares for every Metso share as distribution consideration. Metso Flow Control / Neles will simply continue its life without Metso Minerals. Cheers, Eki
As someone else already mentioned, all China-related problems hit Outotec first and foremost. So it’s possible that it will dip even further, but in the long run, I think it’s a safe and quality stock. Once the bottom is found and the price starts to turn green again (and the worst is over in China), I will buy more. This is a stock meant for a long hold.
I just picked up my first batch of Outotec stock, and from tomorrow’s potential dip, I’ll pick up a second, provided we’re definitely at the bottom of the Parallel Channel. I’ll allow a small margin for tomorrow’s purchase, as there seem to be an astonishing number of virus-phobic people, unafraid of stop-loss sales, on the move. Not on this forum, though.
I think Outotec is only attractive because it gets you Metso Minerals and Neles. I’ll have to consider opening a position myself soon. Right now, the current year for the upcoming MetsoOutotec doesn’t look very promising, but one year isn’t everything…
Oh, so that’s how it went. Neles has value, so it’s worth taking Metso along if you want Outotec. Neles’ manufacturing is mainly in the USA and Finland, so Asian problems don’t really bite either.
Outotec currently has a short position of 1.61% with York Capital, and I’ve been following it daily. It seems they increase their position whenever the price rises even slightly. It looks like they’re getting help from the general market downturn, and some other entity is also selling heavily as the price is falling quite steadily.
I was planning to take a position in the coming days if the market otherwise stabilizes, but it doesn’t really look like that now. Germany’s DAX lost its upward trend, and the US market is also declining, so I’m not really keen on buying right now. We’ll know for sure tomorrow, but it’s good to be cautious right now.
Today I bought Outotec for the first time; it might also make sense to buy a roughly equivalent amount of Metso to get access to Neles in connection with the merger without extra fuss. As a small investor, I’m a realist, and the probability of somehow benefiting by choosing only one or the other is extremely small
Addition: A couple of weeks before the official merger (during Q2!?) and the consolidation of share series, big money will define the “correct” price levels for both Metso and Outotec, and until then, this is just educated guessing. However, I recall reading somewhere that Neles might have more hidden value than believed.
I haven’t seen or done any analyses or calculations, but in Western process industry, Neles is, according to what I’ve heard, the number one choice for a valve. At Neste, I recall the previous 5-year maintenance shutdown ran long due to Chinese valves. They didn’t work according to specifications, and it took a while before they could be replaced with Neles quality.



 I’ll have to consider opening a position myself soon. Right now, the current year for the upcoming MetsoOutotec doesn’t look very promising, but one year isn’t everything…