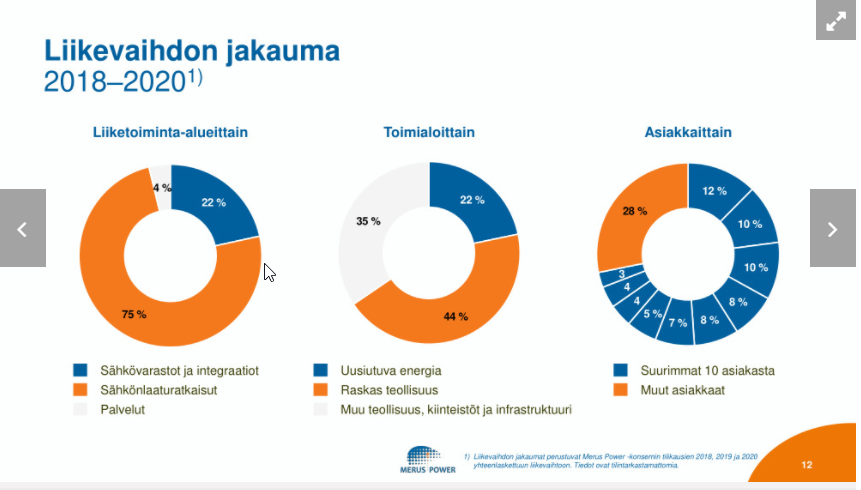
On a quick look, I’m not very interested. It smells a bit like a “crowdfunding-level” case, where a technology that has been developed for over ten years (!) and, according to their own words, is completely superior, still hasn’t really taken off (ok, it has become profitable and 10M€ is at least some kind of revenue), and then suddenly we are at a point where organic growth is expected to explode by ~40% p.a. for the next five years.
Apparently, you have calculated those P/E ratios incorrectly from the operating profit (EBITDA)(?), didn’t the company make a loss of almost half a million in 2020, meaning the P/E for last year was negative? With the 2019 result, the P/E would be 287. Let’s be very generous and assume the company’s record-high 3.4% profit in 2018 and the upper end of this year’s revenue forecast of 15M€, the P/E would still be a whopping 82. (I understood from the posts on this forum that the post-money valuation would be 42M€, I have not checked the numbers myself).
Although P/E is supposedly a boomer metric, I don’t understand why I would pay such multiples for a company that has no evidence yet that it can actually achieve such ~40% growth figures. If I want to invest in an outrageously expensive growth company, I can invest in one that at least has a proven track record of growth and a very predictable continuation (e.g. Qt). One can certainly argue that when that growth takes off as the company predicts, the growth leverage will eat up the multiples, but even if the CEO predicts that 15% could be the EBITDA level, you can’t make this into an earnings machine, if 5-10% even remains below the line as profit.
TLDR: The company and the case might be interesting, but the valuation is absolutely outrageous given the current performance.
 I will correct my calculations.