Lindex should ABSOLUTELY be listed on the Stockholm Stock Exchange and clearly identify itself as a Swedish company. Swedish institutions and citizens would eagerly buy up the stock, and the share price would head northeast.\`
14 Likes
In the strategy report, I would be surprised if a move to the Swedish main list had not been considered or even prepared after the completion of the restructuring. Lindex is in better company there, in a larger (home) market, and in the capital market, so the matter is clear. Linking the end of the analysis to Stockmann seems irrelevant.
4 Likes
Is the plan to make Stockmann profitable and thereby regain credibility for the business, which could open the way for a stock market listing?
In my view, this is the only option, considering the weak state Finland is in, the condition of the global department store business (hardly any acquisition candidates), and the differences between the businesses within Lindex.
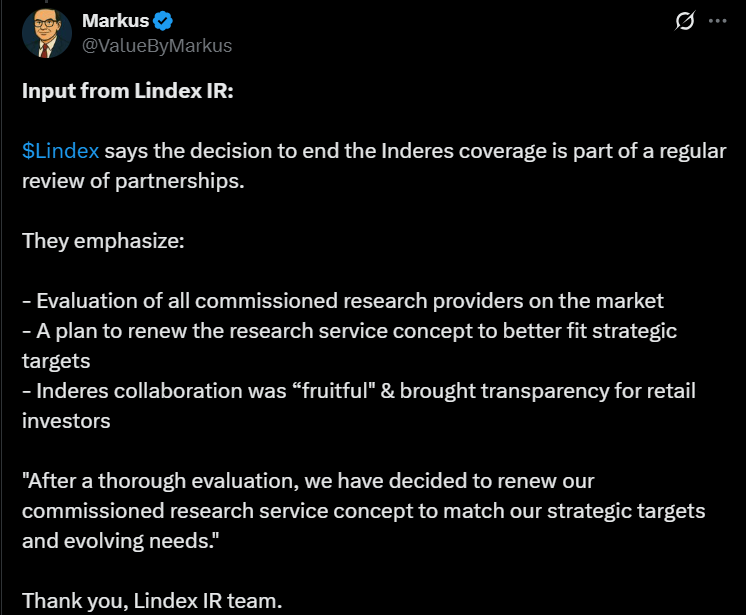
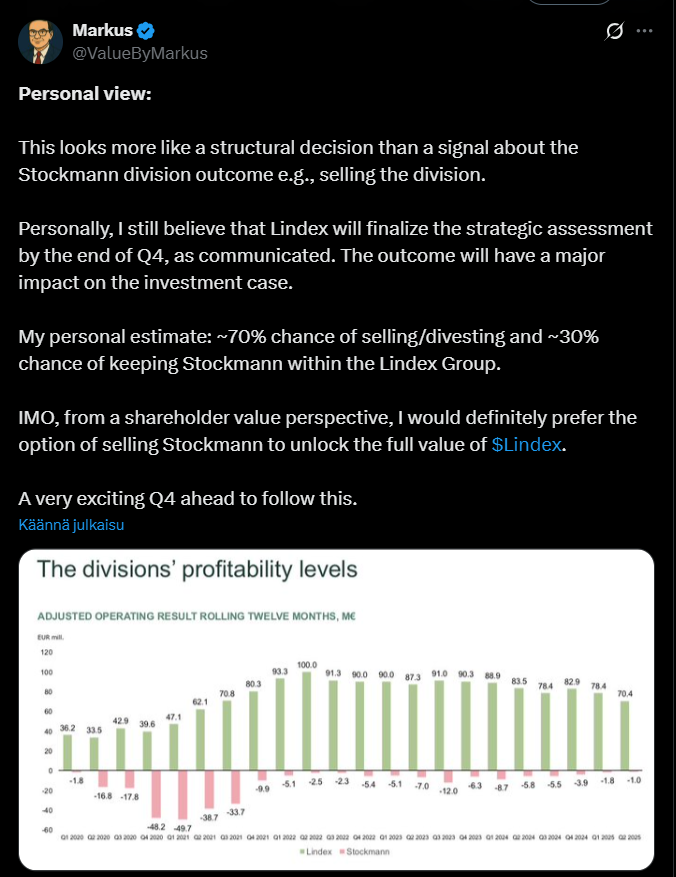
People were asking about IR on Twitter.
https://x.com/ValueByMarkus/status/1973727297183355204
https://x.com/ValueByMarkus/status/1973727736209297555
12 Likes
It would be interesting to read what the idea of a 70% probability for Stockmann’s sale is based on.
5 Likes
It is based on a similar hat constant as the average CRM closing percentages. It is, after all, more likely, when assessed by an outsider, that Stockmann will be divested than that it would not be.
3 Likes
Pieni uutinen (ei löytynyt suomeksi) Grand opening of Lindex store in Denmark
11 Likes
That’s great! By the way, Crazy Days was packed today, and it looks like the products are pretty much sold out online too. A good start for Q4.
14 Likes
Day by day, I myself am starting to believe less and less that the Stocka division will be sold immediately after the clarification. Of course, it’s possible (as probably anything is). I myself would bet more on the idea that, at least initially, some kind of cooperation/procurement agreement (or similar) would be reached with a larger international department store operator and/or retail company.
Why wouldn’t a larger operator just buy Stocka or all of Lindex directly now? The reason might be, for example, Lindex’s current market value, which in my opinion already has a lot of expectations loaded into it that the Stocka division will be sold in the near future. But does the most obvious option often happen in the investment world?
Indeed, there are many possible outcomes, and they are impossible to predict. I myself would just not be surprised if, at the end of the clarification, it were announced that the Stocka division would not be sold. As a result of this decision, the share price might plummet significantly, even if cooperation with a larger operator, for example, were announced at the same time.
The Stocka division could then be calmly put in order, while Lindex’s share price would have fallen, and many disappointed private investors who had been waiting for a corporate acquisition would have sold their shares. A few years could easily pass during this time without Stocka/Lindex making any headlines. In the eyes of the general public, things would have returned to “normal,” even though in the background, the processes of the Stocka division would be constantly streamlined and developed with a new cooperation partner.
Then, when enough signs began to emerge that the Stocka division was genuinely turning permanently profitable, some large operator might suddenly step in and buy out all of Lindex from the stock exchange. Possibly even this same larger operator with whom cooperation regarding Stocka had already been ongoing for a few years. This would be a true win-win situation for a potential buyer. The price would be (thanks to the fallen share price) possibly significantly cheaper than the current one, and the Stocka division would, in addition, be turning permanently profitable.
My text is, of course, pure speculation and full of “isi” forms (a Finnish grammatical form often used for past tense or conditional, here implying a speculative or hypothetical nature). In my opinion, Lindex simply holds all the winning cards; it’s just a matter of who plays those cards and how. Hopefully, we original “frogs” (i.e., private investors), many of whom have been involved since summer 2021, will also get access to decent returns at that point.
Small frogs may not often be among the winners in the big world, but one can always dream. It is then up to each individual’s own discretion what to believe and what to consider the right choice regarding their investments. So, choose your own games; my writing is, of course, not any kind of recommendation in one direction or another. I myself only intend to see these cards through to the end for now, even if someone else might have even stronger cards in their hand.
13 Likes
OP wonders in the earnings preview where the department stores’ solution is…
Also a risk for a negative surprise;
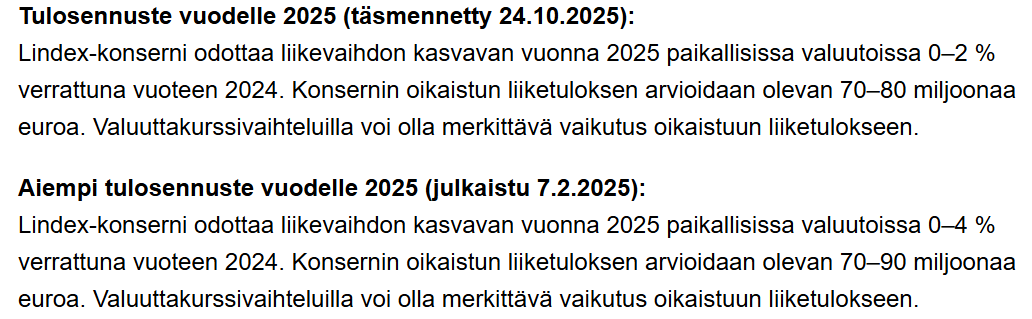
-revenue guidance +0-4%, when H1 2025 was -1.2%
-EBIT guidance 70-90 MEUR when the company’s calculator shows only 65 MEUR
The results will be released on Fri 24.10 in the morning, so more clarification soon.
https://x.com/zijoittaja/status/1980236607405092918?t=WnUJ5RrPXXrXtjgWasJuuw&s=19
17 Likes
“Make Stockmann great again” (best regards, Konstsamfundet), this is REBL’s press release, but it smells a bit like what I wrote earlier. I wonder how it will go in the strategic assessment  : STOCKMANNIN HELSINGIN TAVARATALON ULKOSEINÄT SAAVAT EUROOPAN MODERNEIMMAT ULKONÄYTÖT YHTEISTYÖSSÄ PROFILIGHTIN JA REX MEDIAN KANSSA | Kauppalehti
18 Likes
Tomorrow we’re off again, what are followers’ expectations? Around here, expectations and excitement have run out - which often means good things. 
1 Like
The Swedish Rescuer Didn’t Materialize
HS Analysis|The Swedish businessman who dreamed of buying Stockmann abandoned his plans. There may not be any other interested buyers right now, writes Merja Saarinen, HS’s economics reporter.
Quote from Hesari headline level. Was that what scared him? There was nothing new in the story.
9 Likes
As I recall, the Q2 results were weakened by the cool early summer. So, one could assume that some of the summer clothing sales shifted more towards Q3.
3 Likes
Adding to my previous message. There is also positivity in Rauli’s comments from the summer. In Sweden, a good July and a strong August were reported in the clothing market. Additionally, excellent figures were obtained from the Finnish clothing market for July, with growth of as much as 10%.
The big question mark here is Stockmann’s situation, and we’ll see if anything related to it is heard tomorrow.
7 Likes
The upper limits of the earnings guidance range were lowered, but the lower limit was maintained.
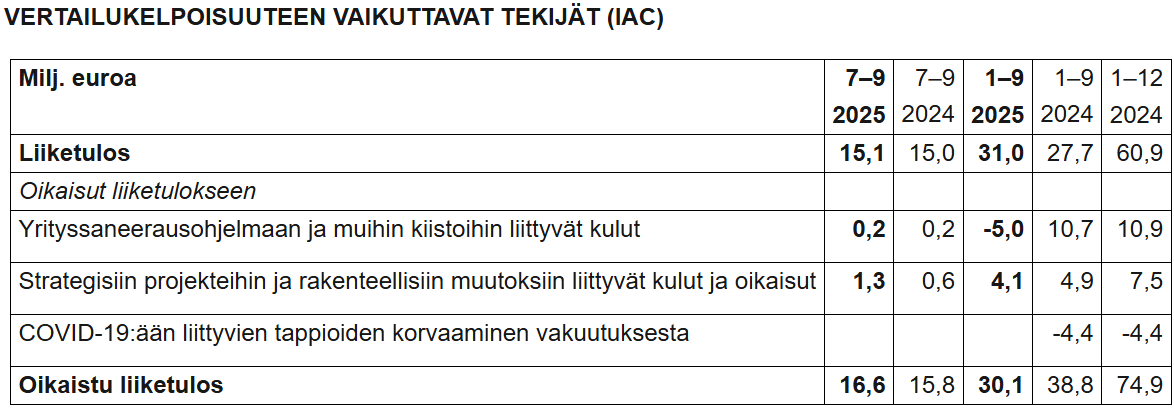
Assessments of the department store business continue, with results to be reported in the last quarter. Investments in “strategic projects and structural changes” amounted to EUR 1.3 million in 3Q2025, and a cumulative EUR 4.1 million in 2024. At least the estimated amount has been invested.
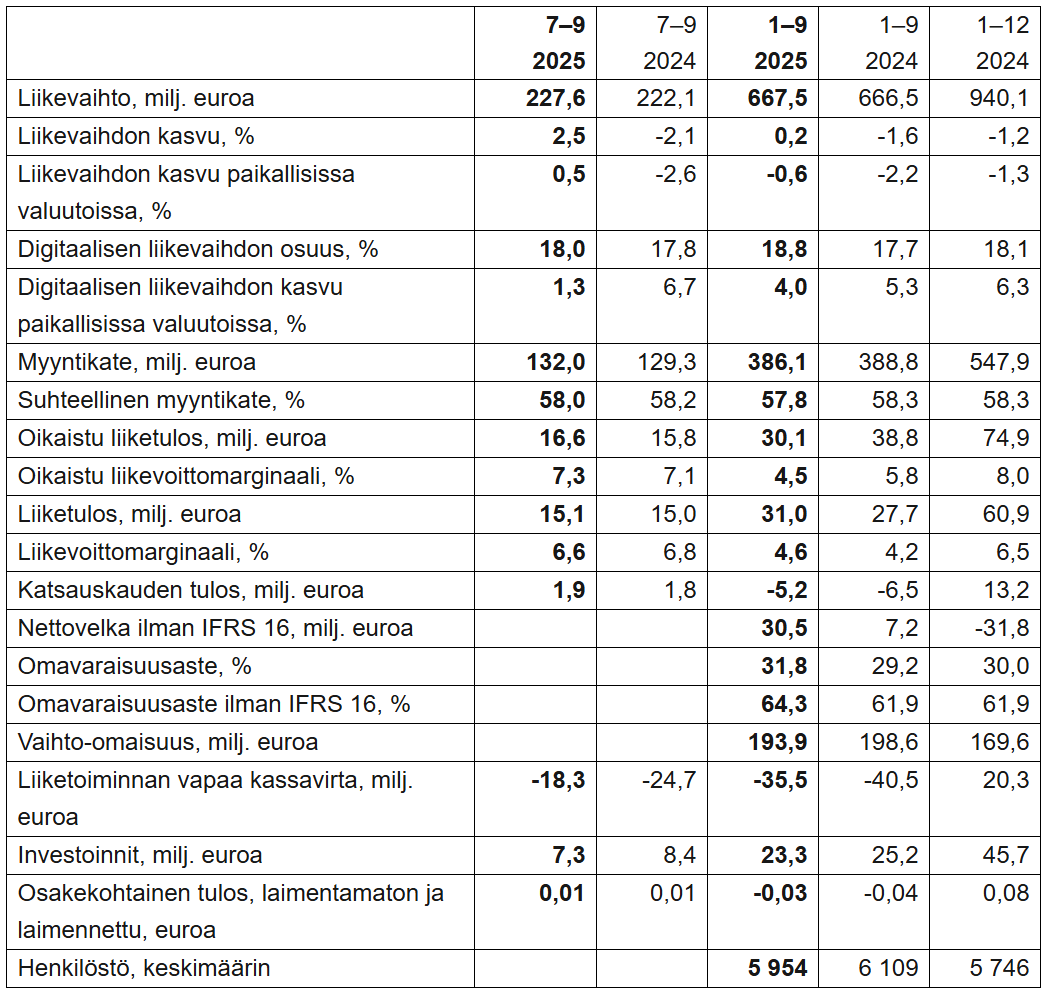
July–September 2025:
Lindex Group’s corporate restructuring program was completed on August 15, 2025.
Lindex Group’s net sales grew by 2.5% and amounted to EUR 227.6 (222.1) million. In local currencies, net sales were at the previous year’s level.
- Lindex division’s net sales were EUR 165.4 (159.3) million. Net sales grew by 3.8% and by 1.0% in local currencies.
- Stockmann division’s net sales were at the previous year’s level, EUR 62.4 (62.9) million.
The Group’s relative gross margin was 58.0% (58.2).
The Group’s adjusted operating result improved to EUR 16.6 (15.8) million.
- Lindex division’s adjusted operating result was EUR 20.2 (21.1) million. The decrease in relative gross margin, as well as increased operating expenses and depreciation, affected the adjusted operating result. Temporary supply restrictions impacted the Lindex division’s result.
- Stockmann division’s adjusted operating result improved to EUR -2.6 (-4.5) million, mainly due to systematic operational efficiency and cost-effectiveness improvements.
Operating result was at the comparison period’s level, EUR 15.1 (15.0) million.
The result for the review period was at the comparison period’s level, EUR 1.9 (1.8) million.
Undiluted and diluted earnings per share were EUR 0.01 (0.01).
The completion of Lindex Group’s five-year corporate restructuring program was the most significant highlight of the company’s third quarter. We reached this significant milestone on August 15, 2025, and are now well-positioned for long-term business development and profitable growth. The company’s Board of Directors continues the strategic assessment related to Stockmann’s department store business, within which various strategic options for the business are being evaluated. We will report on the results of the assessment work in the last quarter.
16 Likes
I am very pleased with the Stockmann division’s third-quarter result improvement, which was already the sixth consecutive result improvement. The Stockmann division’s rolling 12-month adjusted operating profit, 0.9 million euros, was also the division’s first positive rolling 12-month result in many years.
In addition to other signs, it’s starting to look like the turnaround is believed in, and perhaps Stockmann will be kept after all. On the other hand, it could perhaps be sold at a positive price once it’s turned profitable. I don’t know.
9 Likes
A bit of mixed feelings; the upper end of the guidance range was lowered, but the lower end was kept unchanged, and if even that is reached in Q4, it will be a really strong quarter. 
6 Likes
My own guess is that Stockmann’s marketability has been very poor or non-existent. As a result, it has been decided or they have drifted into a situation where Stockmann must be made profitable for a later sale. Thus, as a result of the strategic assessment, Stockmann is being kept because a turnaround is believed in. However, it will be sold later (+one year). Finland’s budding economic growth could also facilitate the turnaround.
10 Likes
Department stores might even squeeze out a profitable EBIT this year. For department stores, Q1-Q3 EBIT was -9.7 million euros, and last year, EBIT in the last quarter was +10.6 million euros. Of course, financing costs for lease liabilities still need to be deducted from that, but not bad in a very weak consumer market.
In my opinion, this adds the option to the toolbox of listing Lindex in Stockholm, with department stores supporting themselves.
10 Likes