Rauli’s comments on Lindex’s July. 
10 Likes
Well then, things are perhaps even progressing a little ahead of schedule: Lindex Group Oyj:n yrityssaneerausohjelma on saatu päätökseen - saneerausohjelman valvoja on antanut loppuselonteon ohjelman toteutumisesta | Kauppalehti
The supervisor of Lindex Group Plc’s restructuring program has submitted a final report on the implementation of the program to the creditors’ committee and the creditors. The company announced earlier in June that it had settled the last disputed claim related to the restructuring process. After the Helsinki District Court confirmed the amendment to the restructuring program, the company has paid the last remaining restructuring debts according to the restructuring program and fulfilled its other obligations under the restructuring program. The company’s corporate restructuring has concluded, and the supervisor has submitted the final report.
“We are very pleased that the Lindex Group’s restructuring program has now concluded. The Group now has even better prerequisites to focus on the future and long-term business development,” says Sari Pohjonen, Chairman of the Board of Lindex Group.
The company filed an application to commence restructuring proceedings on April 6, 2020. The Helsinki District Court issued a decision to commence restructuring proceedings on April 8, 2020, and appointed attorney Jyrki Tähtinen as the administrator. The company’s restructuring program was confirmed on February 9, 2021, and at the same time, the Helsinki District Court appointed attorney Jyrki Tähtinen as the supervisor for the implementation of the restructuring program. The company paid secured debts and a significant portion of unsecured restructuring debts with proceeds from the sale of department store properties in spring 2022. Since then, restructuring debts have been paid as the final amount of the restructuring debts has been confirmed. The supervisor of the restructuring program has deemed that the company has met the conditions for concluding the implementation of the restructuring program. The company’s restructuring program has concluded, and the supervisor submitted the final report on August 15, 2025.
44 Likes
This is quite welcome now we’ll see if the deals for the department stores are already ready, in which case we might hear something soon, or if the fate of the department stores has to wait until the turn of the year. Below is a comment on the decision regarding the restructuring.
36 Likes
At least after the stock exchange opened, Lindex’s share price responded to the announcement with a rise of just over 4%. In my opinion, the matter has been known, but it lacked the final “seal”. It reflects “uncertainty” in investors’ minds. Only now, with an official decision, can we breathe a sigh of relief as this “hindrance” is removed. That speculation about “ready deals” concerning department stores is premature. I await a strategic report. It could state: “We have decided to sell Stokkan’s department store operations. We will start looking for a suitable buyer. Other options we previously presented are not feasible.”
4 Likes
The strategic review has lasted so long that it’s hard to believe management has rested on its laurels in terms of mapping out potential business partners. There could be multiple bidders or negotiations are in their initial stages, but if consultants are only now being put to work, we are, in my opinion, really late.
It would certainly fit the company’s operating model in this regard, but it would still be very difficult to believe.
5 Likes
We know for a fact that board members have been absent from board meetings last year due to conflict of interest aspects, meaning discussions have been ongoing for a longer time.
Something might be heard in September. Or not.
26 Likes
This is quite a big deal, as Lindex (Stockmann) is apparently paying a dividend next spring, the last time this happened was in 2014 : Osinkohistoria - Lindex Group B (LINDEX) | Pörssi | Kauppalehti
And then, when the logistics center in Sweden is sold and leased back, there could even be an additional dividend. This has mainly been brought up by @Seinakadun_Keisari, right!?
I brought this up separately now, even though that dividend is indeed already in @Rauli_Juva’s forecasts. For many investors, however, dividend payment can be a decisive signal to become an owner, although the end of the restructuring is at least as important a milestone. Even a somewhat surprisingly subdued share price reaction to the news today.
What has long bothered me about the potential sale of this Stockmann division is that it might be psychologically overwhelming for the Konstsamfundet group to give up Stockmann “for free” or even pay the buyer for it. That would require explanations to stakeholders for the rest of their lives at all evening gatherings and social events, “Yee-es, so you gave our Stockmann away to foreigners for free” For the aforementioned reason, I believe that if the sale indeed happens, it will be made to look good to the general public as well. Of course, the error in thinking here was that Konstsamfundet would possibly remain an owner if Nordic Retail Partners were the buyer.
14 Likes
If, in theory, retail can be sold for, say, one euro, and the logistics center sold for a value of 110 million euros, then I don’t consider a generous additional dividend for long-suffering owners to be a complete pipe dream. A one-euro dividend would roughly mean 160 million, which would be affordable as no major investments are expected for a while. It’s unlikely to happen, but I wouldn’t be surprised by a 50c dividend in this case.
16 Likes
I don’t know how many have been involved in corporate acquisitions.
Thorough investigations are conducted by the buyer for this.
This means many people participate in the preparation of the matter.
No matter how many “confidentiality” promises are made, the matter leaks.
Regarding the sale of Stokkan, no “rumors” have emerged. Only observations have been made about the composition of board meetings.
Therefore, as a Lindex investor, I firmly believe that progress will be made step by step.
I also don’t believe in the sale and leaseback of Lindex’s “sheet metal hall”. The company has just been put on its feet, and there are high expectations regarding the hall’s operations.
Leasing also costs money, and some party takes their profits in between.
1 Like
And to ensure I understand the situation and arguments correctly, I want to confirm this: What would be the benefit for Lindex’s business and competitiveness if the logistics center were sold and leased back?
Freeing up the LC’s capital from operations for owners (share buybacks or as dividends), as a result of which a new owner would demand a 5-7% return, which Lindex would then have to pay? → Lindex’s competitiveness would decrease.
Freeing up the LC’s capital for investments - but for what investments? Expanding the store network, staff? In my view, that LC capital is already invested in the most potential and best target in the short to medium term, i.e., improving e-commerce growth and profitability? A package packed in own facilities provides cost competitiveness in e-commerce compared to competitors, enables more affordable prices in e-commerce, and thus increases sales potential? Or does someone think it’s likely that Lindex’s e-commerce would decline in the next 15-20 years? (Vs. Operating a store network under lease is much more justifiable)
Of course, I understand the improvement in return on equity in the short term, but selling the LC would only weaken the Lindex chain’s competitiveness in consumer markets.
Could you imagine that industry successes (those successful in building competitiveness) Walmart, Costco, Lidl, Aldi, Walmart, and S Group would announce a shift to a leased facility model in core logistics?
10 Likes
I’m not taking a stand on this otherwise, but in the background discussion of the AGM, it emerged that modern logistics halls are allegedly quite attractive to real estate investors, and the return requirements for them are reportedly low. Go figure.
So it probably doesn’t make sense to become a tenant with a 7% yield, but if the figure is 4%, then the situation is different.
And from a shareholder value perspective, that 100M is certainly acceptable as a starter after years of struggle.
12 Likes
Lindex probably still owns those traditional logistics centers in Alingsås + Partille?
One of them was sold, and the other was probably owned.
I haven’t followed if the other one has been sold too, but some cash will come from there as well, and there might still be some logistics productivity hidden away. Even if they are empty.
4 Likes
The answer to both is none, as it has nothing to do with operational activities who owns the walls of the property, whether it’s a department store, a shop in a shopping center, or a logistics center. Its competitiveness as an investment, however, improves.
The cost of equity is higher than the range you presented, and competitiveness as an investment improves when the return on equity presumably improves as money is distributed through some measure. If the money is wasted on some unproductive investment or acquisition, then competitiveness decreases.
In financing solutions, everything always depends on the price of the acquisition target. If a sheet metal hall can be sold and leased back at a 4-5% return, the contracts should already be ready for signing. If a similar sum starts approaching ten percent, it might not be worth making these solutions with the hall.
If that solution were to be decided upon, the company can fortunately optimize its capital structure by seeking loan financing on the market, and even in that scenario, it would be possible to distribute dividends, even if it wouldn’t be as optimal as selling to a direct real estate investor.
19 Likes
“This too is bound to leak, because information always leaks anyway”
Well, you’re absolutely right about that, usually something comes out, but if NDAs are brought into the discussion, their purpose is to keep the matter away from the general public. As I said, if consultants only start running around with brochures in September (or whenever the information is released..), in my opinion, we are already very late. I personally believe that Stocka’s deck was delivered to potential buyers a long time ago, because the time required for corporate acquisitions is known.
In my opinion, however, a very important part of the Strategic assessment is what would be available from Stocka, isn’t it? In other words, a strategic assessment cannot be concluded until the selling price is known. If no one genuinely wanted to buy Stocka at a price that serves the shareholders, it would be more advantageous to keep Stocka as part of Lindex. If it’s announced in September that the goal is to sell Stocka, but no buyers are found, what then? It’s announced that Stocka will remain part of Lindex. I don’t believe for a second that such a risk would be taken, no matter how unlikely it is.
This is actually a good point; one might imagine that initially, caution would be exercised with asset sales. BUT it must be taken into account that logistics centers of that size are usually sold with a 4-5% Entry Yield, and without knowing more precisely about Swedish rent levels, that would still be at least a good €100M. If there are no investment needs in the coming years, it’s possible that the “tin hall”'s operations will be run at full potential before sale (which would certainly be quite smart).
From the perspective of capital structure optimization, it’s crystal clear that the “tin hall” must be sold, but I personally believe it will happen within a 2-5 year timeframe from today. The “tin hall” will then fetch the same price as today, and by then, the new Lindex will have had time to stabilize its other operations after the Stocka mess. Of course, the owner takes profits when renting, but it must also be considered that a lease agreement with such yield requirements and square footage is likely to be a 10+10 year or 15+5 year model, or similar, e.g., a direct 20-year maturity, and Lindex gets to decide the rent level itself - which, of course, directly affects the millions obtained from the sale. However, these are long contracts where Lindex has the option to continue with the same contract for a total of 20 years. This keeps the rent level moderate even with indexations, and Lindex does not have to spend time and energy on property maintenance itself, as it will be handled by real estate ownership professionals. The irony in exiting the “tin hall” is that the lower the rent level, the better the profitability in the coming years, but the worse the price when sold. In any case, a shareholder should hope for a long contract 10% (pulled out of a hat) below market rent, in which case Lindex wins in profitability and still gets a fat check. (Usually, for example, a 10% discount on market rent does not directly mean a 10% decrease in the purchase price, but the yield requirement can be tightened as the rent increase potential rises down the line).
7 Likes
A 40,000 M2 logistics center’s yield should be 5% or less, regardless of the market situation. I would say that if it’s sold today, it would be a 4.0% entry yield for the buyer. Of course, this also always depends on the rent level at which it is sold. If the rent were set to the absolute maximum, the yield usually rises slightly, and vice versa (rent increase potential and the final price per square meter naturally always affect the overall picture).
A center of that size, as a single entity, already interests Mileway (Blackstone), Logicor (China Investment Corp.), Brookfield, and other largest global players. For example, Sagax might come in second in this race.
9 Likes
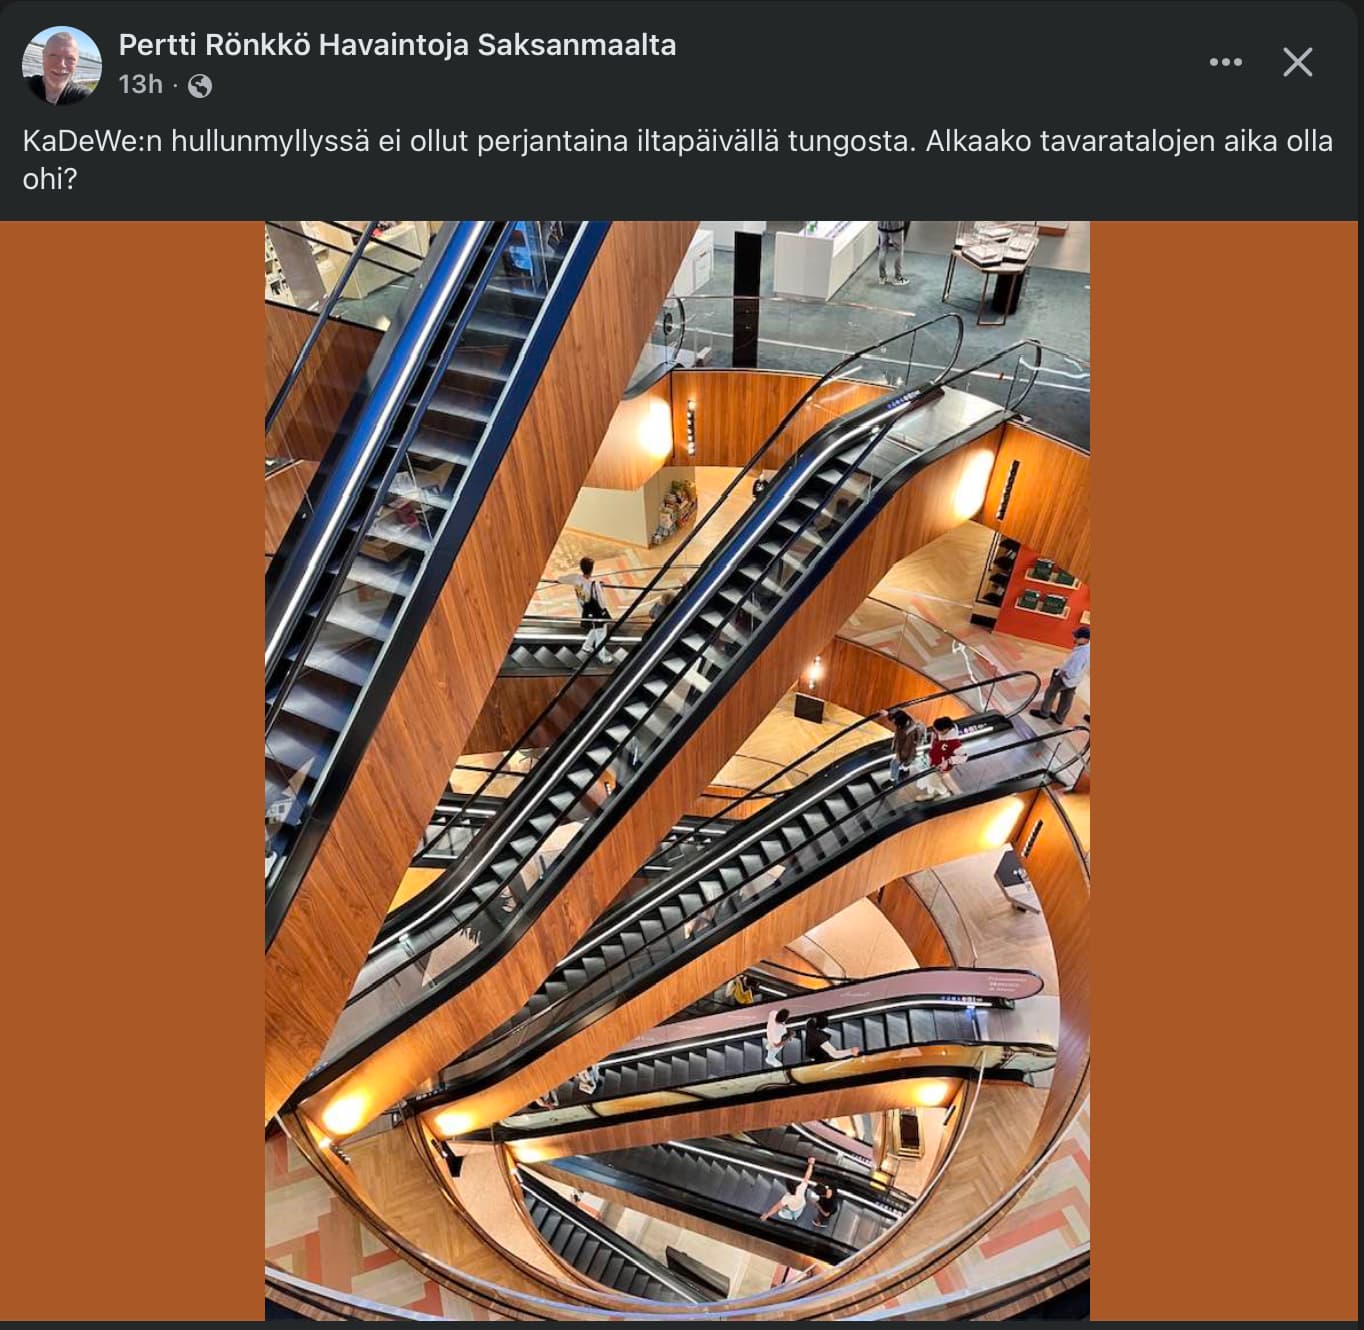
Could it be that all the young people were already at the square because of the European Basketball Championship semi-final…
”Especially in the young target group aged 18 to 29, interest is even higher, at 23%. This growing enthusiasm underscores the potential and attractiveness of this target group for brands and companies.
Basketball fans in Germany are young, urban, and keen to consume – an extremely attractive target group for brands.”
1 Like
It seems that yields for logistics centers in Sweden are in the 5-6% range.
It’s a different matter from what sum that yield is calculated. It’s hardly calculated from “the investment of the logistics center,” because then the square meter rent would probably go above market level. That investment actually includes absolutely everything: the land, the warehouse building, machinery and equipment, software, consulting costs related to the project, salaries of own employees, etc.
If the annual rent were 100eur/m2, the annual rental costs for a 40000m2 property would be 4M€, and with a 5.5% yield, the property’s selling price would be 72M€. With this equation, one would have to commit to a fairly long NNN lease agreement, and since it’s a long agreement, inflation adjustments would inevitably be made to it. It must also be noted about the NNN agreement that in addition to the rent, all ongoing maintenance costs of the property must be paid (as is currently paid), and various modernization investments, etc., will also arise along the way.
Numbers can be played with in many ways. I don’t believe that 100M could be freed from there, but these are all guesses until someone presents facts 
6 Likes
It shouldn’t be calculated from Lindex’s investment cost. The buyer shouldn’t be much concerned with what Lindex has “paid” for the hall.
Usually, these work in such a way that Lindex states the rent level and rough terms of the lease agreement, on which the S&LB is implemented, and then buyer candidates offer a suitable purchase price based on this. Alternatively, buyer candidates offer a ready package, meaning the rent level and other terms come directly from the buyers. The seller then decides which offer has the best terms. Lindex’s investment cost is not mixed into this bidding process.
So, do you have any market data or experience for this, or what is it based on?
1 Like
Here are Rauli’s comments on the strong August in the Swedish clothing market. Sweden is Lindex’s largest market.
10 Likes