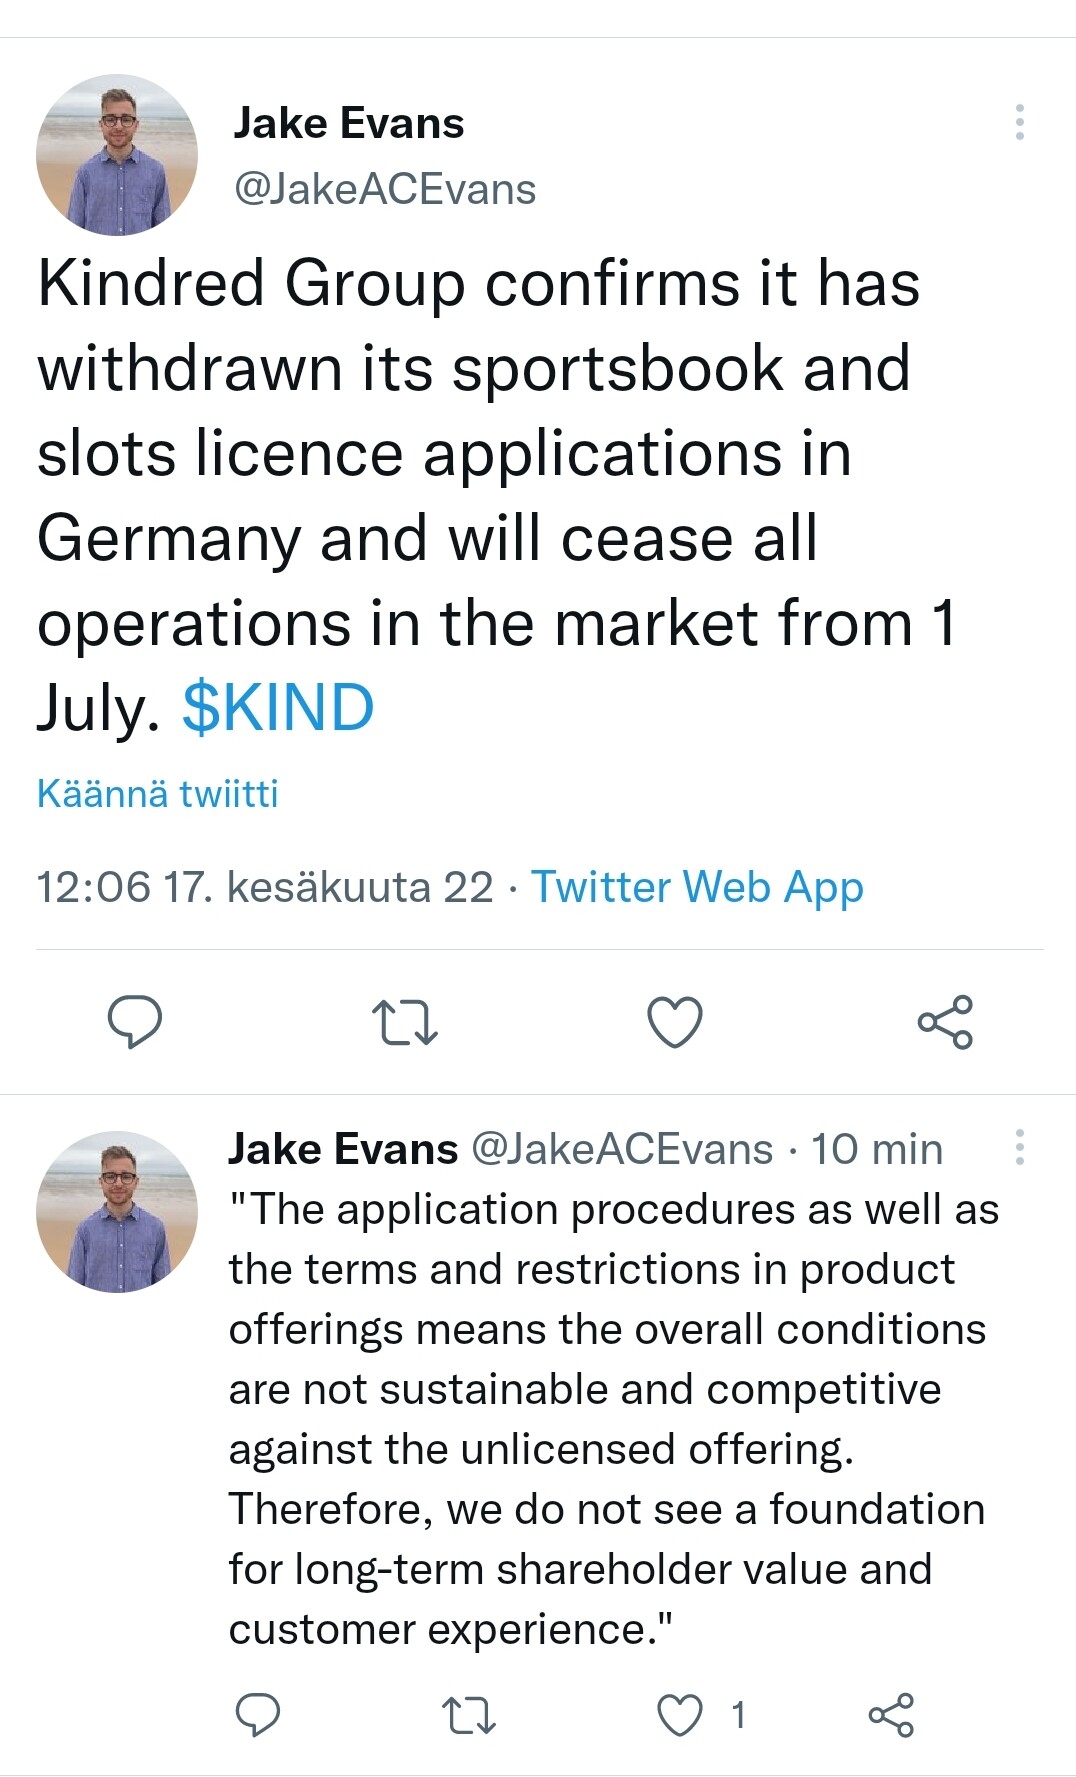
“It (EBITDA) also includes the impact of Relax Gaming on the Group’s consolidated numbers of GBP 3.7 million.”
Revenue was 28.9 million and full-year EBITDA was 13 million. The Relax acquisition was officially completed in the autumn, in my opinion, so only Q4 has been taken into account.
STOCKHOLM (Nyhetsbyrån Direkt) The Norwegian Gaming Authority The Norwegian Lotteries Authority has informed Kindred’s Norwegian subsidiary Trannel of a fine of the equivalent of NOK 437 million if the company does not stop turning to the Norwegian market. This is stated in a press release on the Lottery Authority’s website. “When a gaming company that operates illegally in Norway can earn NOK 437 million from its illegal activities within a year, we owe it to the Norwegian people to do what we can to stop the illegal activities,” says Atle Hamar, director of the Lottery and Foundation Authority. The authority wants to give the company a daily fine of SEK 1.2 million per day, which will run until the company ceases operations or until the amount amounts to the annual gross profit of SEK 437 million. It was in April 2019 that the Lottery Authority ordered Trannel to cease operations. The decision was appealed by the company but has so far not been heard for its appeal. The company has asked the Oslo District Court to find out the validity of the decision and in May the matter will be brought before the district court.
Kindred Group plc (“Kindred”) hereby announces that it, on 16 February 2022, has received a notification of major holdings in Kindred from Corvex Management LP., a company with its registered office in New York, USA.
According to the notification, Corvex Management LP. holds 5.29% of the shares and voting rights in Kindred as of 11 February 2022. Corvex Management LP. serves as investment adviser to investment funds and accounts, including Corvex Master Fund LP. and Corvex Select Equity Master Fund LP., which own the securities reported in the notification.
This information is information that Kindred Group plc is obliged to make public pursuant to the Listing Rules published by the Malta Financial Services Authority under the Financial Markets Act (Chapter 345 of the Laws of Malta).
For more information:
Patrick Kortman, Head of Corporate Development & Investor Relations, +46 723 877 438
Linda Lyth, Investor Relations Manager, +46 767 681 337
Here’s a comprehensive article about the kind of owner Kindred got. The company’s founder is Keith Meister, whose mentor was none other than Carl Icahn. This is an activist fund, so it’s possible that there’s already some kind of plan in the background for Kindred, and they won’t settle for just being an observer. The fund’s largest holding is MGM, which co-owns BetMGM with Entain, a company that has strongly entered the US online casino market.
It will be interesting to see if there’s a potential acquisition here, as Kindred would be significantly cheaper than Entain, which both MGM and Draftkings have already tried to buy. Has anyone been following the situation more closely? The company’s share price certainly reacted positively to this announcement.
Kindred maintains its momentum from the previous quarter and total revenue for the first quarter of 2022 amounted to approximately GBP 247 million.
Compared with the first quarter of 2021, operations have been negatively affected by the decision to temporarily suspend services to Dutch residents. Kindred’s active markets have developed well in relation to the very tough comparison period, a decrease of 5 percent (1 percent at unchanged exchange rates), which emphasizes the importance of a diversified market portfolio.
**The temporary negative impact on the Netherlands, combined with continued selective investment in future growth, is expected to result in an underlying EBITDA of approximately GBP 25 million during the first quarter of 2022.
Kindred Group plc (Kindred) has, despite headwinds, delivered a stable quarter with total revenues of approximately 247 million (Q1 2021: GBP 352.6 million). Total revenue decreased by 30 percent (27 percent at unchanged exchange rates) compared to the corresponding period last year and was negatively affected by the decision to temporarily cease activity in the Dutch market on 30 September 2021. Adjusted for the Dutch impact, the corresponding decrease is reduced to 5 percent ( 1 percent at unchanged exchange rates) and is mainly the result of a tough comparison period.
Underlying EBITDA for the first quarter of 2022 is estimated to amount to approximately GBP 25 million (Q1 2021: GBP 106.0 million), which is approximately in line with the result presented for the fourth quarter of 2021.
Could someone provide a summary of Kindred’s journey since the news at the beginning of last October when operations in the Netherlands were paused? They now have a license, but the stock price is roughly where it dropped after that bad news. Apparently, the conquest of America, at least, has not taken off as well as planned? This investment target would be interesting again, but I think the risks are quite high because one market might suddenly close, and the stock price immediately drops by tens of percentages.
Yes, the license is in hand, but to my knowledge, Kindred has to start its conquest of the Netherlands entirely from scratch; they apparently cannot use old databases/user accounts. America, on the other hand, has been a challenging market with fierce competition and large players spending billions on marketing. Now that, for example, DKNG and PENN’s stock prices have dropped 76% and 59% in one year, one would think that these companies would try to improve their profitability and reduce marketing costs, among other things, in the coming years.
The contract with Kambi expires, if I remember correctly, in 2026, which raises questions about the development of an in-house sportsbook. And if some entity were to buy out Kambi, I wouldn’t see this as a positive thing for Kindred, now that the poison pill is no longer there.
I myself sold Kindred around 110 and jumped on the competitor Betsson’s bandwagon at the beginning of the year. Betsson, of course, operates more in risky markets, but its business seems to be developing rapidly with a cheap valuation. In my opinion, Betsson is also a more attractive acquisition target than Kindred because of its own sportsbook. Regarding America, Betsson has also acted wisely; they haven’t rushed into the race to the grave but are entering gradually with the help of the sportsbook, at least in 2023.
Kindred seems to be a company that lacks the famous pricing power in an inflationary environment.
Regarding Kindred and other companies in the sector, I’m interested in the question of what happens to the purchase of casino and betting products when people’s finances start to decline. I don’t think it’s an impossible idea that, paradoxically, the consumption of gambling increases when consumers’ purchasing power generally weakens.
A positive signal for Kindred Group in the coming years as well. When the monopoly starts to be questioned by Veikkaus’ (Finnish national betting agency) own leadership, it will surely have long-term political effects. Kindred Group already has a very strong foothold in Finland, and the brand is well-known.
Hey, this is actually a bad thing for Kindred. The current situation is perfect for gaming companies—they get to operate in the market but don’t have to pay a license fee.
I suspect a possible advantage from dark operations in the shadows of monopoly markets; yes, market acquisition is more important. Open operation in the market would bring significantly more customers and more spending customers into the scope of services. One can, of course, still remain a dark operator outside the licensing system, just like now, if it is so profitable.
So Kindred is not some “dark horse” now. Finnish people are not prohibited from gambling with foreign operators. Those license fees can also be absolutely insane; for example, in Germany, they destroyed the entire gambling industry because the fees were so huge (I think it was a 5% tax per bet/round). In the US, for example, in New York, gambling companies pay a 50% tax.
I completely agree with @Anssi2. For those who actively engage in betting, Veikkaus is just one service provider among many. Using other gaming companies is often even faster and easier, and you also get welcome bonuses and better odds than Veikkaus. The last couple of points would likely take a hit with a licensing model.
I also don’t believe that a licensing model would bring in many more customers. Of course, they would probably be able to advertise more freely, but in the gambling industry, 10% of customers bring in 90% of the revenue, and that 10% are already very well aware of the offerings.
In connection with the Capital Markets Day, Kindred Group will present new financial targets for 2025 consisting of:
Revenue of above GBP 1.6 billion
Underlying EBITDA margin of 21 – 22 per cent
Distribution policy of ~75 – 100 per cent of free cash flow (after M&A)
Q3:n näkymiä: Trading update and indicative guidance for the third quarter 2022
As part of the CMD, Kindred provides more clarity on the performance for the period 1 July to 11 September and a non-recurring indicative guidance for the third quarter 2022. The trading update shows a solid Gross winnings revenue development driven by high activity across markets.
The average daily Gross winnings revenue for the Group, up to and including 11 September 2022, was GBP 2.9 million, 12 per cent (12 per cent in constant currency) lower than the daily average for the full third quarter of 2021. Excluding the Netherlands, the average daily Gross winnings revenue for the Group, up to and including 11 September 2022, was GBP 2.6 million, 6 per cent (7 per cent in constant currency) higher than the daily average for the full third quarter of 2021.
On the completion of a stringent license application and regulatory review process, Kindred launched in the Netherlands on 4 July and, during the period from going live up to and including 11 September, the average daily Gross winnings revenue for the Netherlands was GBP 317 thousand, increasing gradually throughout the period.
Depending on activity levels and the sports betting margin for the remainder of the quarter, Kindred estimates the revenue for the third quarter of 2022 to be in the range of GBP 270 to 280 million.
Underlying EBITDA for the third quarter of 2022 is estimated to be in the range GBP 37 to 42 million (Q3-2021: GBP 84.8 million).
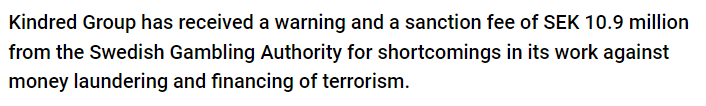
The Swedish gambling authority (Spelinspektionen) has issued a warning and a SEK 10.9 million fine to Kindred for neglecting to monitor money laundering and terrorist financing.
This certainly doesn’t improve the company’s reputation, especially when ESG funds are already avoiding the firm. On the other hand, strict regulations might be beneficial for established operators like this.