Has anyone looked into the options of Swedish/Danish companies in more detail? It seems several small companies there have option programs. The options of two Danish companies, in particular, caught my eye. Curasight’s option price is now 8 DKK, and with the option, one can subscribe to shares in the autumn at 17.2 DKK, but the share price is 27.9 DKK. Cessatech’s option price, on the other hand, is 6.3 DKK, and with the option, one can subscribe to shares later this year at 10 DKK. The current share price is 21 DKK. If I’ve understood correctly, either the share price or the option price is severely off. Especially considering that both are early-stage pharmaceutical companies, so the options should also have a fair amount of time value…
1 Like
With options, there’s a normal risk premium because there’s no guarantee what the stock will be at the end of the year. The price approaches the stock price (plus subscription price) as the subscription date nears.
A lower price means there are sellers who want cash now, not at year-end, and are willing to take a nominal loss for it.
3 Likes
High-speed trading firms are paying brokers bil-lions of dollars a year to execute options orders, leading them to promote the risky trades whose popularity has boomed among small investors.
The practice, called payment for order flow, has made options a cash cow for brokerages such as Robinhood Markets Inc. and TD Ameritrade. They can make twice as much or more from selling cus-tomers’ options orders as they do from selling order flow for stocks.
In the 12 months through June, the 11 largest U.S. retail brokerages col-lected $2.2 billion for selling customers’ options orders, according to Larry Tabb, head of market-structure research at Bloomberg Intelligence. That was about 60% higher than their take from selling equities orders.
During that period, major brokers were paid an average of about 16 cents for each 100 shares of their customers’ stock orders, compared with about 54 cents for equiva-lent-sized options orders, Mr. Tabb’s data show.
While the payments are legal and have existed for decades, they came under renewed scrutiny after the January trading frenzy in shares of Game-Stop Corp. The Securities and Ex-change Commission is reviewing payment for order flow, and its chair-man, Gary Gensler, has said the agency is open to banning the practice.
Critics say payment for order flow has reshaped brokers’ business models to make them intent on juicing more trading activity from customers, sometimes through gamelike smartphone apps. Some warn that larger order-flow pay-ments from options activity can effectively push inexperienced customers into risky trades they don’t under-stand, exposing them to large potential losses.
Apparently, losses from US options can also be deducted in taxation as a private individual?
1 Like
This Nasdaq article states that Nokia’s December 23, 2021 options are unlikely to be “on the money” when they expire,
https://www.nasdaq.com/articles/december-23rd-options-now-available-for-nokia-2021-11-04
December 23rd Options Now Available For Nokia
Contributor
Nov 4, 2021 11:49AM EDT
Turning to the calls side of the option chain, the call contract at the $7.50 strike price has a current bid of 2 cents. If an investor was to purchase shares of NOK stock at the current price level of $5.69/share, and then sell-to-open that call contract as a “covered call,” they are committing to sell the stock at $7.50.
Considering the call seller will also collect the premium, that would drive a total return (excluding dividends, if any) of 32.16% if the stock gets called away at the December 23rd expiration (before broker commissions).
Of course, a lot of upside could potentially be left on the table if NOK shares really soar, which is why looking at the trailing twelve month trading history for Nokia Corp, as well as studying the business fundamentals becomes important.
Below is a chart showing NOK’s trailing twelve month trading history, with the $7.50 strike highlighted in red:
Considering the fact that the $7.50 strike represents an approximate 32% premium to the current trading price of the stock (in other words it is out-of-the-money by that percentage), there is also the possibility that the covered call contract would expire worthless, in which case the investor would keep both their shares of stock and the premium collected. The current analytical data (including greeks and implied greeks) suggest the current odds of that happening are 99%
On our website under the contract detail page for this contract, Stock Options Channel will track those odds over time to see how they change and publish a chart of those numbers (the trading history of the option contract will also be charted). Should the covered call contract expire worthless, the premium would represent a 0.35% boost of extra return to the investor, or 2.62% annualized, which we refer to as the YieldBoost.
US ETFs cannot be bought in Finland, but can options on these ETFs be bought?
1 Like
Here’s a good calculator for long call options…
https://www.optionsprofitcalculator.com/calculator/long-call.html
3 Likes
Where or through which broker do you buy options?
1 Like
Mandatum Trader Go, which provides good access to the US markets.
1 Like
Is a warrant’s stop loss calculated based on the closing price, or is it sufficient for the stock to have traded below that level on the previous day? For example, a Tesla long warrant. Stop loss at $900, with the price above $900 at the start and end of the day. However, the price fell below $900 in the evening when the euro product couldn’t even be traded. Does a knock-out occur?
1 Like
That is stated in the product information of the derivative in question — essential characteristics must be based on reliable information.
Option Type Call
American Exercise Type
Exercise Time is 11:00 a.m. (Helsinki time)Reference Price shall mean the closing price of the Underlying determined and
published by the Reference Agent on the Valuation Date.For the purpose of determining whether the Observation Price touches or falls below
the Current Knock-Out Barrier, each determination of the price of the Underlying by the
Reference Agent during the Observation Period shall be relevant.
These are probably the essential parts of the document. What difficult jargon. I got the impression that Nordnet’s turbowarrant would be checked the next day based on the previous day’s closing price. This would mean that if the closing price is higher than the stop loss, the product won’t be knocked out even if the price has gone below. I could be wrong, though.
1 Like
Interactive Brokers. Comprehensive and functional, even for enthusiasts, offering automated options strategies, etc.
3 Likes
https://www.wsj.com/articles/these-options-terms-are-greek-to-you-11601858160
Sure, they probably know, or can easily learn, the basics: puts and calls; in-the-money and out-of-the money; HV (historic volatility) and IV (implied volatility); the naked and the spread.
But what about Vomma…..
If the term vomma is Greek to you, that is because it literally is. Options traders use various Greek letters and terms to describe the sensitivity of an option’s price to various factors, such as volatility in the underlying security. The most basic terms—delta, gamma, theta, vega, and rho—are referred to as “major Greeks.
” Vomma, on the other hand, is known as a minor Greek because it provides insight into vega.
Delta is a ratio that mea-sures how much an option’s price is expected to change for every $1 shift in the price of the underlying security. Deltas on puts (which give the owner the right to sell a security at a certain price) can range from 0 to negative 1; on calls (which give the owner the right to buy a security at a certain price) they are 0 to positive 1. If a call has a delta of 0.50 and the price of the underlying stock rises $1, the price of the call will go up, theoreti-cally, about 50 cents, as long as every thing else remains constant.
Delta can offer a rough gauge on the odds an option will wind up in the money at expiration. (A call option is in the money if the market price is above the strike price; a put option is in the money if the market price is below the strike price.) For example, a trader buying a far out-of-the-money put with a negative 0.05 delta has a 5% chance of the option expiring in the money. Not a good bet.
Delta neutral is a common phrase. It means a combina-tion of option deltas add up to zero, and the combined options will move, for a time, 100% in lockstep with the underlying stock. It’s very useful for hedging a stock’s movement.
Gamma This one is tougher; it measures the rate of change in the delta of an option for every one-point move in the price of the underlying security. What does this mean? An oft-used analogy is that delta is an option’s speed, and gamma reflects acceleration, a nuance that may be more important to professional traders hedg-ing large portfolios.
Gamma is small when an option is deep in or out of the money. It is at its largest when the option is near or at the money.
Retail traders may often hear advanced traders mention gamma scalping, which is, very broadly speaking, adjusting an options position frequently with a primary goal of not losing money due to theta (see below).
Theta measures the rate of change in an option’s value due to time, and is usually expressed as a negative. For example, if an option’s theta is minus 0.20, an investor can expect its premium to decline, or decay, 20 cents a day, if everything else remains constant. The rate of decay tends to accelerate as the option nears expira-tion.
Option writers, or sellers, collect theta when they open a trade, by receiving a small cash payment, a premium, for the risk they are taking on the trade, not unlike how insurance firms collect premiums.
Vega, which isn’t a Greek letter but one of the Greeks, nonetheless, measures an option’s price sensitivity—how much it could change—in response to implied volatility changes in the underlying security. Vega is a higher number for long-dated options than for those expiring soon; long posi-tions will be positive, however, and short posi-tions will be negative.Vega is useful for hedging against implied-volatility changes; changes in vega are mea-sured by the aforemen-tioned vomma, a minor Greek, (a Pyrrho not a Plato, you might say).
Perhaps more useful is this trader’s tip: If the vega is smaller than the option’s bid-ask spread, then the spread isn’t competitive.
RHO This comes in last, and for good reason. It measures the expected change in an option’s price for every one-percentage-point change in interest rates. Considering interest rates have pretty much disappeared, no one tracks it these days. [tilanne on alkanut muuttua 2/2022].
The above is intended to show new traders how much they may not know about the art and science of options trading, a type of investment (sort of) where smart people sometimes get wiped out (and mint mil-lions).
1 Like
I found a clear presentation of different options strategies. How many of those can one remember by heart?
I’m answering my own old question: yes, it’s possible. In principle, you can also acquire US ETFs this way when you redeem them upon expiry.
I’m replying to an old thread now that I’ve stumbled upon it.
There’s nothing really to remember about these. One shouldn’t overcomplicate options for themselves. A European option is ultimately a very simple product (and an American one’s payout is the same at maturity).
If you just consider what the value of an option is at maturity, it simply comes from the formula (when buying) max(0, S-K) in the case of a call option, and max(0, K-S) in the case of a put. Here, S is the stock price and K is the strike. When selling, you just add a minus sign. All those strategies in that link are just sums of these functions, except for those with options of multiple maturities. Interestingly, any European option whose payoff is a convex function h: R->R (or can be represented as a combination of convex functions) can actually be replicated by buying and selling a sufficient number of different options with the correct weights (Carr-Madan). This way, for example, volatility derivatives can be replicated with European vanilla options sold on the market.
However, I personally stay far away from stock options. Too much leverage, and one would need to have some opinion on stock movements. That’s difficult or nearly impossible. 
Could you elaborate a bit more on what you mean by that sentence? Or how it applies to American options?
Of course, if one doesn’t want to make investing more complicated, it’s probably best to generally stay away from options.
I haven’t really come across any discussions about free or half-price shares distributed to management. For example, I own Consti because it seems cheap. However, I started to feel uneasy when I looked at their option program. In 2020, 245,000 shares were distributed for free, and this year, 250,000 shares were distributed for free to management. There also seem to be random bonuses here and there.
Roughly 0.5 million shares have been given away, from an investor’s perspective, like dust in the wind.
According to Consti’s website, the total number of shares is 7,858,267, so it was about 7,358,000 before. This increase is large in percentage terms. In a few years, investors have lost about 6.8% due to the option program if I interpret this correctly ((7,858,267)/(7,358,000) -1 = 0.068 → 6.8%. Unfortunately, I see a pattern here that, if it continues, will be completely destructive to me. Management, of course, enjoys this, but this cannot be good for the share price development. And I don’t believe it creates any added value.
Options distributed to staff are, in my opinion, a good idea as it helps to engage and motivate employees. Management members are often major shareholders themselves, so they are already committed, and the addition to shares is just a nice bonus. There is no benefit to other shareholders. How many small companies are there on the stock exchange whose management wants large options for themselves and thus destroys the returns of small investors? Of course, the general meeting decides on these, but I see a fox guarding the henhouse situation here.
Am I unnecessarily worried since there isn’t much discussion about this? Am I interpreting the situation completely wrong?
4 Likes
So my point was that all those strategies are ultimately plus and minus calculations of weighted put and call options. The expansion to any function was mainly a curiosity that this actually applies to any payoff function h. For example, an iron condor strategy is the sum of the payoff of one bought put option, one sold put, and one sold call option. This can also be extended to so-called smooth payoff functions with the formula
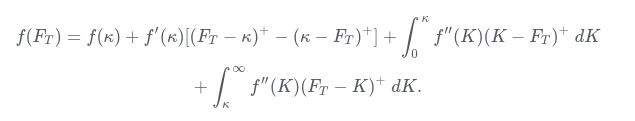
Assuming convexity, this can be further generalized to payoffs that are only continuous from the right with respect to the strike (for example, a digital option is one such).
In itself, although my side point might sound like academic rambling, it’s good to know if you’re trading VIX. The VIX index is calculated from the prices of SPX (S&P 500) options using a discretized special case of the formula above. On page 5 below.
3 Likes