Intrum as an investment

It doesn’t look like there’s a thread for this company here either, which isn’t a surprise in itself. The same problem seems to be affecting everywhere.

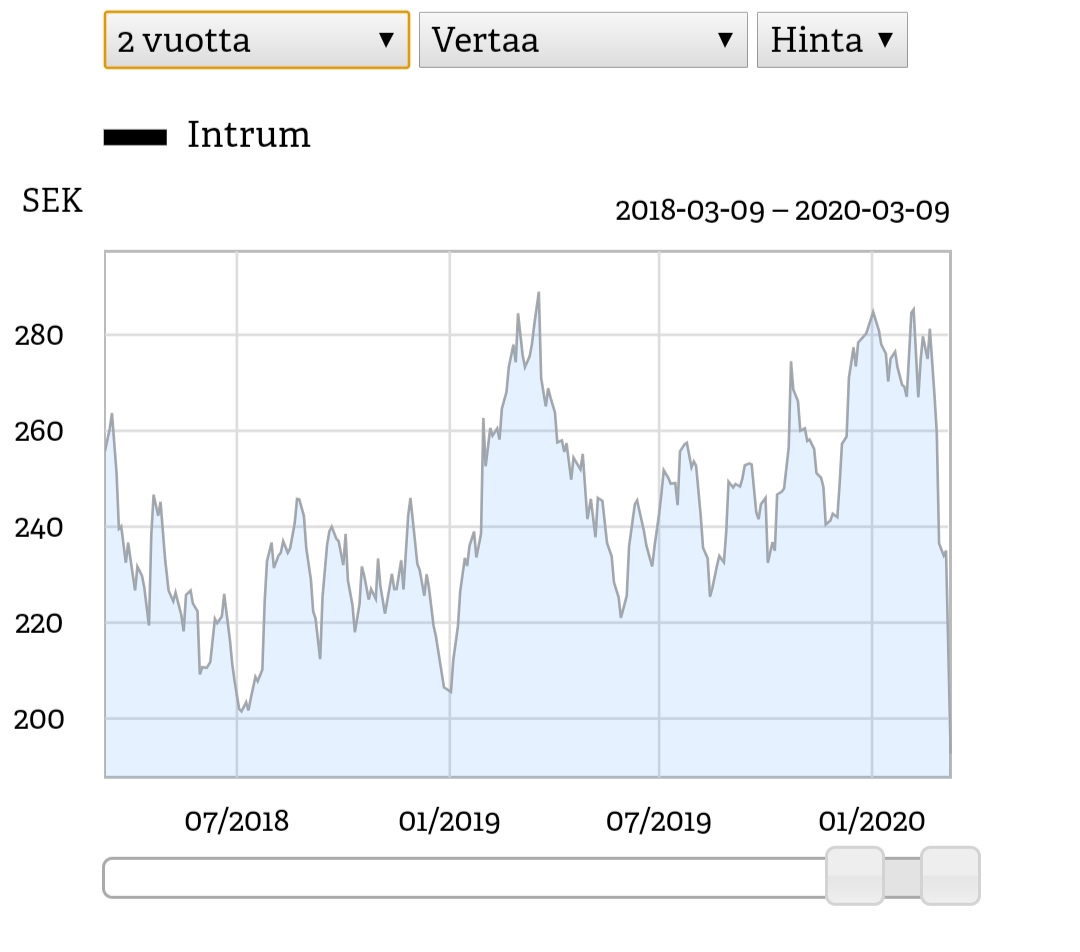
I’ve been interested in Intrum as an investment for quite some time. A quality company that currently seems to have quite a lot of turbulence, as seen in the attached price chart:
20200310_185933

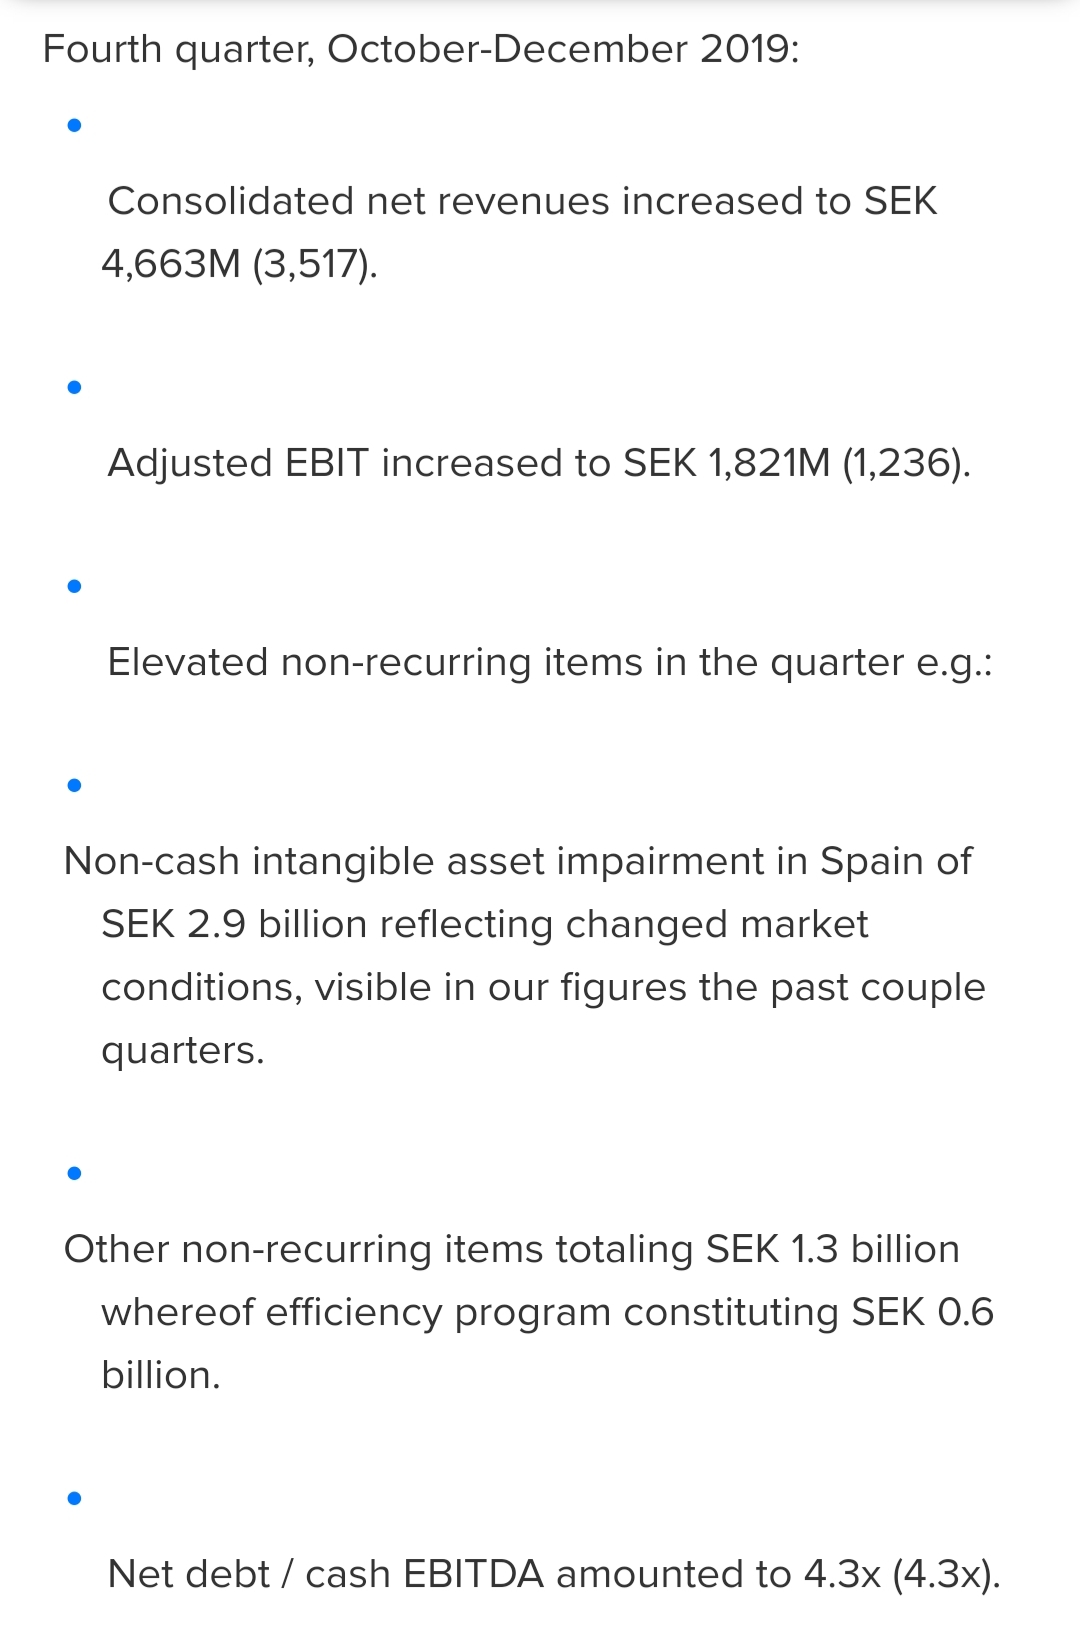
Intrum is thus a debt collection company operating in an almost monopolistic position in the Nordic countries, with Svea Ekonomi, which is clearly smaller, as a potential competitor in Finland. The company has also sought growth by, for example, buying large batches of Italian junk loans, and has been very profitable in recent years. Last year’s excellent result was mainly hindered by non-cash items.
20200310_190244

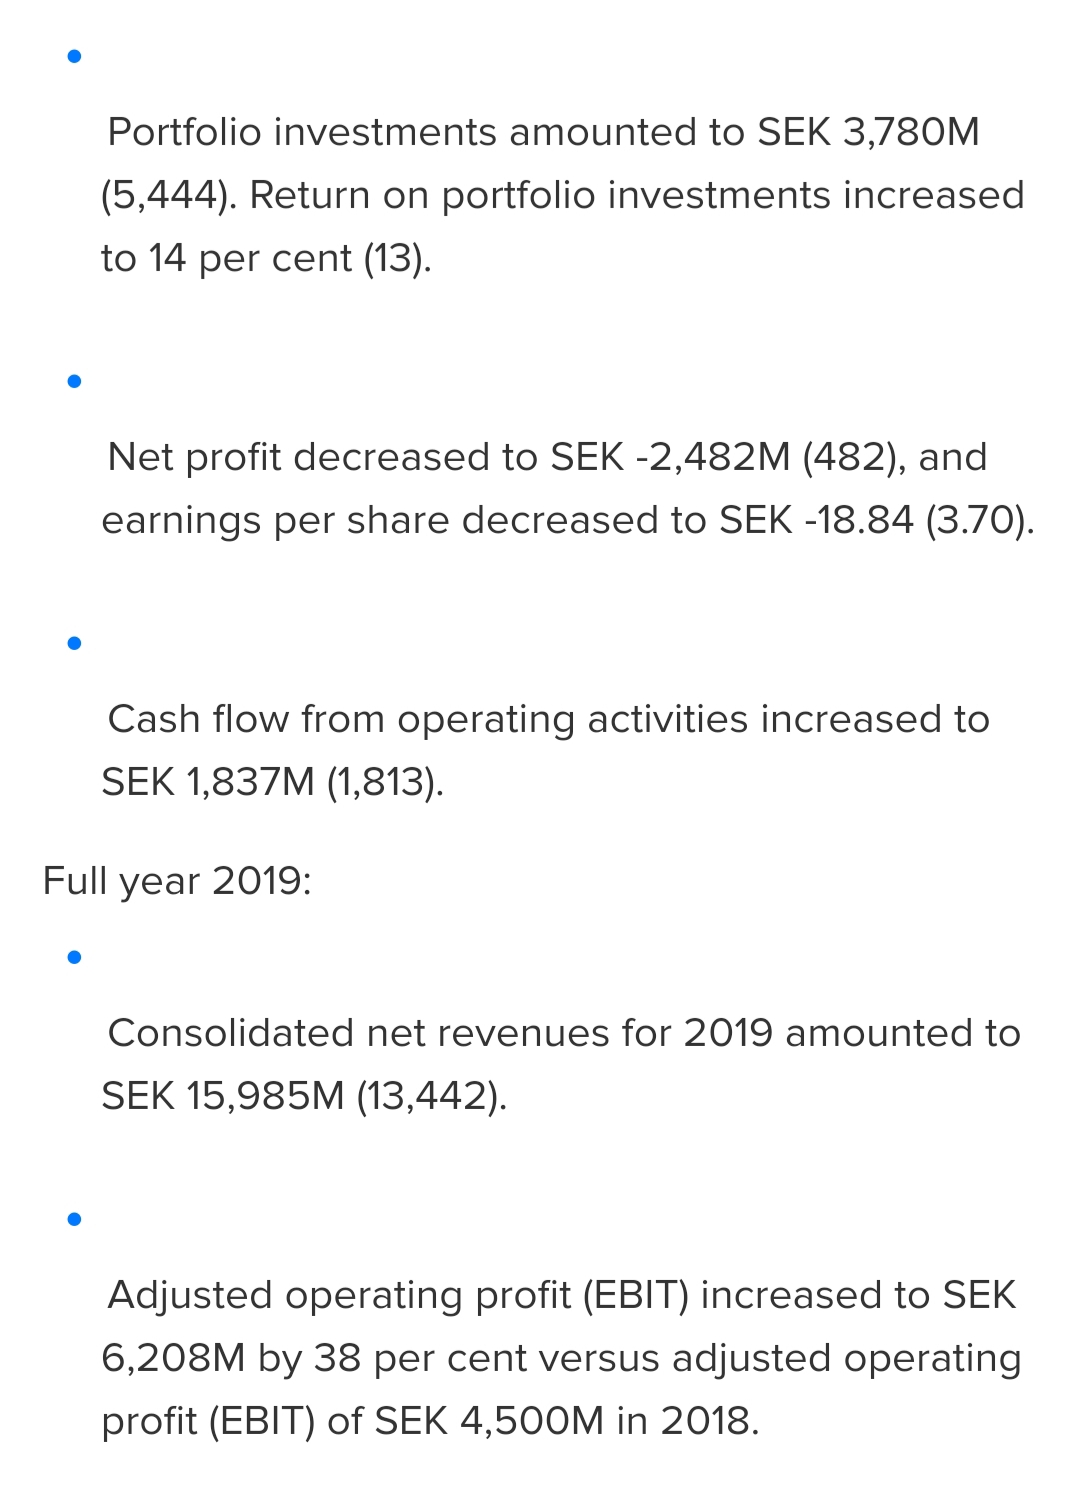
Intrum generates good cash flow, so a few weaker quarters won’t necessarily bring it down, even considering the debt burden.
20200310_190327

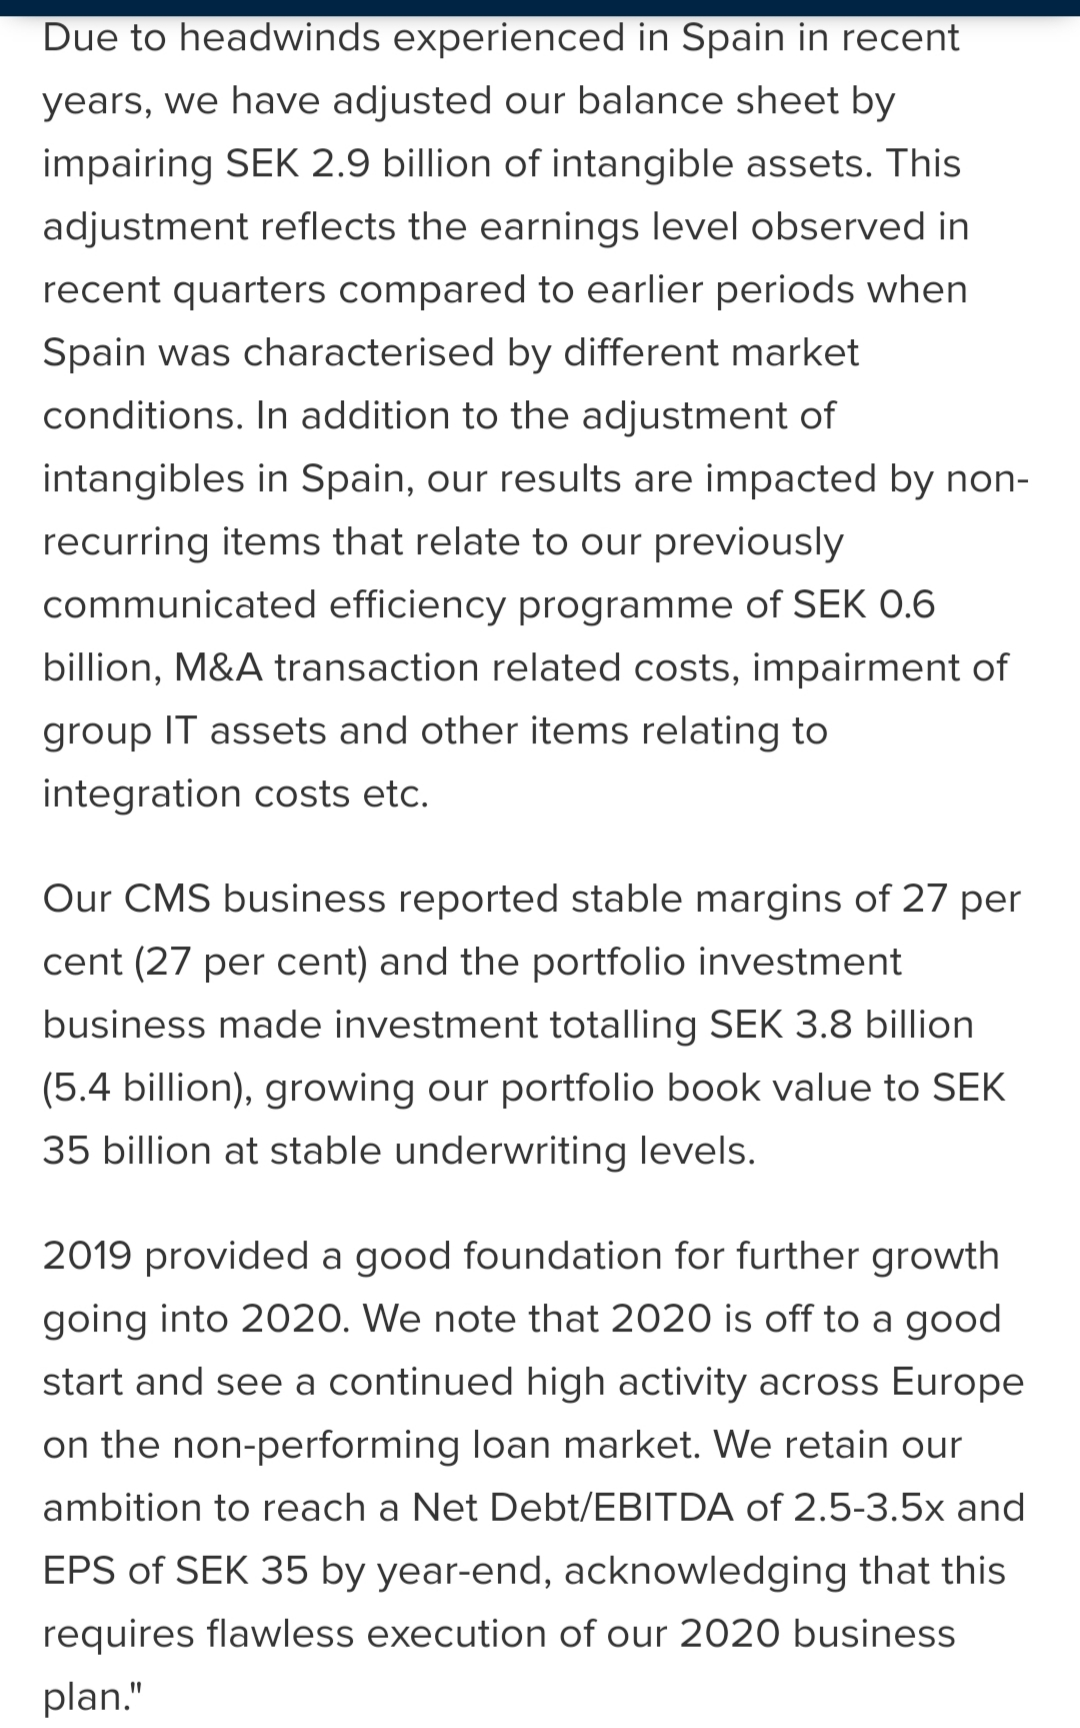
The target for 2020 was 35 SEK, which, given the current farce in Italy, is hard to imagine being realized. However, the company’s dividend (11 SEK in 2020) is on a solid foundation with a payout ratio of less than 50%.
20200310_190353

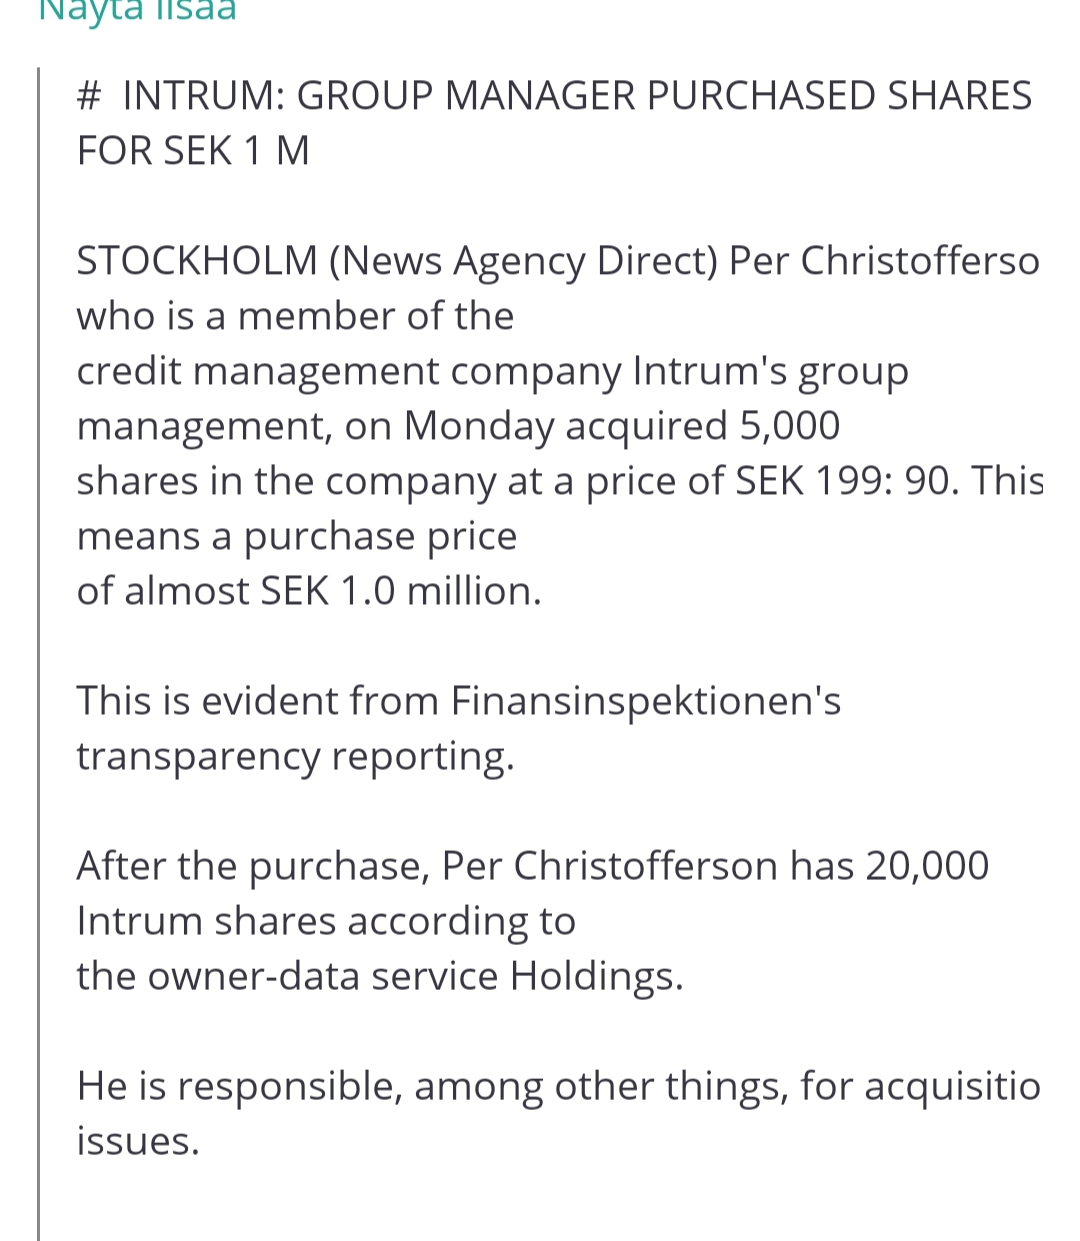
In addition, the company’s insiders have also been buying recently.
20200310_185958

Today it was announced that the Italian office is practically closed due to corona. The impact on earnings from Italy can be estimated at around 10-15%, so I can’t quite accept a drop like the one seen recently for that reason alone.

As one of Sweden’s most shorted companies, it’s understandable that bad news leads to a rapid decline. However, the same lever works in the other direction as well; in the best case, good news could trigger a significant squeeze.

Personally, I see the current price as almost confusingly cheap. The current dividend yield of over 6% provides a nice floor for this year, and with the current forecast (depending on the forecaster), a P/E ratio of 5.5-9 is also cheap for a company that has historically grown profitably. A small bonus could be the price effect of the Euro very likely weakening from its current level against the krona.

I’m slightly bothered by Sampo exiting the stock during February. Does the large owner know more than we do? On the other hand, Mirko managed to calm things down a bit at the investor evening in Tampere, saying that Intrum was just a financial investment and there was no intention to corner a larger piece. On the other hand, now that the price is almost 100 krona cheaper, why not?

Debt is not going to run out in Finland, for example. The number of payment defaults is only increasing, as are various monthly payment vehicles. You can get credit cards in cereal boxes. Even so, Finns, for instance, handle their debts remarkably well in the end, even if it’s only after going through court. The amount of credit losses in the Nordics is quite small.

Any other thoughts?

5 Likes

The company’s name is Intrum, and “Justitia” was dropped a while ago. Italy’s share of operating profit is less than 10%. It’s been in my portfolio for years, a company aiming for good growth that sometimes misses the mark (Spain and Brazil), and it remains to be seen if Italy will join them. They are starting more cautiously in Greece, but in its field, it is clearly the largest in Europe and brings a slightly different diversification to the portfolio.

I always ask myself in these companies, which involve ethical considerations, whether the markets and politicians have goodwill towards them in crisis situations. For example, I wouldn’t dare invest a single penny in Fellow Finance. Intrum, however, is a traditional and quite reputable operator that even survived the financial crisis, so the aforementioned problem is unlikely to exist.

1 Like

Alright, great!
https://www.inderes.fi/fi/tiedotteet/intrum-launches-buyback-program
https://www.inderes.fi/fi/tiedotteet/background-intrum-initiating-share-buy-backs

My own shares are quite heavily in loss now :laughing:
This is definitely a positive signal.

E:

3 Likes

Intrum is now at 128 SEK, and this company is starting to truly interest me. Are there any major risks that a small investor like me doesn’t understand, as the current price feels like a clear overreaction? Even with temporary difficulties due to Italy, a good dividend and ROE strongly support and reduce risk.

Good that you brought this up!

I haven’t really followed Intrum lately, but I guess a lot has happened there in recent years. Traditionally, one could say about these collection agencies that a buyer’s market is slowly emerging, meaning Intrum’s business will start to pick up.

During an economic boom, bad loans are scarce from banks, and their prices rise, which burdens the business of companies like Intrum. In a downturn, more and more portfolios gradually become available, and their prices become more favorable. The moment of truth ultimately comes when cheap portfolios have been accumulated, and the economic cycle starts to turn, allowing collection efforts to be intensified.

I need to reacquaint myself with this company when I have more time.

Intrum is now down to around 95-100 from 125 last week? Will the decline continue or is it time to put on my buying pants? My hands are itching to buy.

2 Likes

What has dropped this today? I was going to buy under a hundred, and now I’ve missed it. I need to investigate further. You’d think there would be enough business, but the sudden drop is a bit puzzling.

Muddy Waters went short quite aggressively. There might be a short squeeze once the Americans agree on a stimulus package.

The question right now seems to be what is the probability you believe the company will make it through this crisis/the coming years?

Because at these levels, there is historically no ambiguity about the price; it is cheap. However, in a bearish way, it is already so low that it is frightening.

I trust that the insider and the company’s board of directors are familiar with the situation. The insider bought (199 SEK) and the board subsequently decided to start repurchasing their own shares.

1 Like

I also have strong faith in the company. The company quickly and very decisively announced the repurchase of its own shares.

“Repurchase of shares is currently considered an attractive investment which is made possible by Intrum’s strong financial position.”

Additionally, it was stated that the maximum price they are willing to pay is 200 SEK/share.

One of the most shorted stocks in Stockholm. A good place to create shareholder value :+1:

About 10% of the shares are sold short. Now, if Nalle were to buy a large block with Sampo’s cash, the ride up would be strong.

The price is attractive, but MW is not a useless firm. It would be a big hit if something shady were found in Intrum’s balance sheet. My memory connects MW to busting Chinese companies, so it’s surprising to see MW going after a Nordic shop. Well, I guess a short report or at least the key points will be published about this sometime.

The pricing is absolutely crazy right now. It has been for a couple of weeks already. The MW (Management-Werke) is bothering me because they have an unpleasant habit of digging up all the skeletons in the closet. Hopefully, none will be found now. It’s a great time to buy their own shares; they should buy thoroughly and with both hands.

A while ago, this was considered a good buy at SEK 300, now you can get it for a third of the price. If anyone finds anything shady about Intrum, please let me know, because the current price seems really cheap.

Well said, dare I hit the buy button already?

I’m not 100% sure, but could this share issue have been due to this?

I’m happy with their buybacks now that they’ve bought almost 8% of the outstanding shares. As a shareholder, I thank them! :+1:

https://www.inderes.fi/fi/tiedotteet/intrums-share-buyback-program-completed
https://www.inderes.fi/fi/tiedotteet/intrum-press-release-notification-major-shareholding-own-shares

Intrum acquired Lindorff and was obligated to sell certain parts of Lindorff/itself, at least Nordic operations. The number of shares increased accordingly. I’ve been along for Intrum’s bumpy ride since 2014, and so far, dividends of almost 50 SEK/share have already fallen from it. My wife’s portfolio still holds 100% more shares than my own.

Intrum has a lot of debt, and according to market rumors, that’s why, for example, MuddyWater is shorting Intrum. It seems to be the most shorted stock in Stockholm. Intrum uses this debt to buy loans and has systematically achieved a 20% return on its investments. A couple of years ago, they bought loans from Italy when local banks were cleaning up their balance sheets under pressure from the ECB, even though the Bank of Italy tried to slow it down, saying they shouldn’t sell too cheaply.

Usually, I wouldn’t touch a company with a similar amount of debt with a ten-foot pole, but in Intrum’s case, curiosity has won out.

I bought my first two tranches of Intrum this April. Honestly, it’s too difficult to assess all the risks, but the stock price has probably plummeted due to these Italian loans, and high debt leverage also plays a part in why short sellers are interested. Nevertheless, I trust the management to know what they’re doing. There will always be enough loans to collect, and with the price below 150 SEK, it’s historically an exceptionally cheap price.