Huh, Fortum’s share price at its highest since 2008 

10 Likes
In 2007, it was over €32, well, everything was up then… waiting for that rerun…
2 Likes

Celebration day
8 Likes
I would expect a 10-year bear market like that to behave a bit differently. Not a sudden crash, but a slow decline as economic prospects weaken. This would be combined with a fall in valuation multiples as investor enthusiasm wanes. In practice, there would be a bigger, but slower, turn for the worse. In a decade-long bear market, the cause would be some major problem, until the problem became restoring investor confidence as the economy recovered.
If there’s a major macroeconomic downturn lasting 10 years, then even strong growth companies’ growth will likely slow down along with the rest of the market. Someone has to buy the service or product, and if the corporate sector is doing poorly, there’s less purchasing power. Only the very top growth companies will do well. They must be in sectors where the customer absolutely needs the service. For example, cybersecurity services.
These Peloton exercise bikes are not among those reliable growth companies 
This is a tough one. There are many sectors that are cyclical but are still expected to grow. For example, electronics contract manufacturing and pulp production. In the future, more of both will be needed, but at the same time, both industries are truly dependent on demand from the rest of the economy.
This has turned into rambling and thinking aloud. Someone once said that something that cannot go on forever will end. I have that feeling with this bull market, and I’m trying my best to prepare for its end. I will continue to buy stocks and not start hoarding cash, but the aim is to emphasize companies that can do well even in difficult times.
The only problem is, I don’t know how to I should pay for high margins, quality, and defensiveness, but at the same time, I shouldn’t pay too much, as the air will eventually seep out of valuation multiples. I guess I’ll just have to keep an eye on the bargain bins and hope that such a cheap company can’t fall much further.
7 Likes
In its interim report published on April 28, 2021, OP Financial Group estimated that its 2021 profit before taxes would be lower than the 2020 profit, which was EUR 785 million before taxes. According to the updated estimate on June 15, 2021, OP Financial Group’s 2021 profit before taxes is expected to be at the same level as or higher than the 2020 profit.
This bodes well for other banks too 
4 Likes
If one finds “surprises” or turnaround companies with P/E ratios of 10 during a bear market, who then triple their earnings in a couple of years, like Harvia or Rapala, then the portfolio is unlikely to perform poorly.
5 Likes
More thoughts on the same topic from my end:
I myself suspected that, going forward, it will be increasingly common that if quick profit opportunities don’t exist based on traditional fundamental thinking, those opportunities will then be created organically by (small) investors themselves.
The enablers of the WSB (WallStreetBets) antics, however, are factors that were not even close to being available in their current form around 2008, and they were essentially invented in the 90s. So, now that all the people in the world have been brought together by digitalization, there will be concentrations here and there in the mass, according to basic physics/chemistry. In other words, stupidity is what concentrates, and greed is one of the world’s best catalysts.
On the other hand, information also travels genuinely faster, and there will always be new good cases in the world that are then overshot more rapidly than before if and when everyone attacks the feeding grounds while a large mass of stocks slumps. Even now, after cryptocurrencies, there have been some AMC, etc. rounds when there’s otherwise nothing fun going on and boredom prevails. What will we see by the end of the year then?
So, I believe the quick-profit scene will thrive in the future. A proper “this time is different” speech then 
12 Likes
Information does travel faster, just like it did in the dot-com bubble. And even before, there were real speculative clubs where “wise heads” came together, whether it was the 1720 bubble (the first so-called “people’s” - well, relatively elite - bubble in England), 1820, 1840, etc., etc. 
Strangely enough, speculation and quick gains have withered before when the market slumps, even though all sorts of reasons have always been invented as to why it would be different this time.
The general mood changes quickly when the average lottery ticket brings losses instead of easy gains.
7 Likes
Yep, in that sense, it’s always a stock picker’s market. In a weak market, it’s just much harder when a larger portion of stocks don’t turn out to be Harvia-like. Now, it feels like every other company is, if not quite, then almost a Harvia in the eyes of investors.
This year has already been much more difficult than last year, which has been evident in the less frequent bragging of swing traders and day traders about their own returns.
11 Likes
Yes, certainly, but thousands upon thousands of new people have already been trained into hardened gamblers, even if a large mass of speculators can surely be cut off/scared away. The stock market has now effectively branded itself as a casino, which is not a new idea at all, but when it has moved even more forcefully than before from being an “elite” hobby to “people’s lottery” to some extent, there might be more permanent power in that. And especially in the fact that you can now play the East India Company AND/OR the crypto bubble from your phone anytime, anywhere. Or maybe not, time will tell.
3 Likes
A few comments from my perspective; I’ve been investing for several decades. Firstly, in the long run, people usually focus on price indices. Secondly, the comparison point is chosen by picking the worst-case scenario. If you invest in dividend stocks, in a bad situation, you can buy at a good price with dividends and get an excellent dividend yield. If you invest in a reinvesting index, it buys with dividends at a good price and good multiples, and the multiples will be higher in a few years. Even if the valuation goes down, the dividend yield rises, and the cork will eventually pop to the surface.
I can give an example from my own portfolio. I bought Walmart at $56.98 USD in 2010. Then in 2011, I bought with dividends at $53.96 USD, and in 2012, at $70.18 USD. In 2015, I bought at $58.21 USD. One might think that the stock has been stagnant since 2010. In 2010, the dividend was just under $1/share, whereas in 2015, it was $2/share and rising. The dividend had risen from about 1.8% to 3.4%. Well, it started to become attractive in its category, and the price began to follow. This leads to the point that multiples can decline for a long time, but 10 years is a long time. Expectations and multiples will eventually follow. Now, just over five years later, the stock is $140 USD, meaning it has doubled from the worst price it was bought at and almost tripled from the first dividend purchase.
Currently, certain companies benefit from loose monetary policy. Others, however, are struggling. Those that need interest rates for their operations, such as banks and the insurance sector, are facing difficulties. Poor companies will be eliminated, and as the operating environment improves, strong companies will achieve tremendous results, and it will be difficult to enter the industry due to, for example, regulation. There has been no inflation, and in such a situation, the valuations of companies that perform well tend to rise when it strikes.
8 Likes
Today, before work, I went to the gym and Basso radio station was playing. My weights almost dropped from my hands when the Puuilo IPO jingle started blasting at full volume  I almost feel like pulling out of the “market” completely and selling my portfolio empty, now that things have come to this level
25 Likes
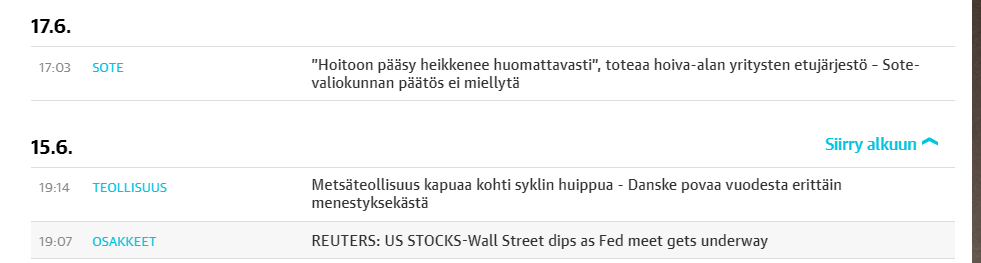
I have to say, Kauppalehti is wonderfully ahead of its time.  (they’ve apparently already fixed their mistake.)
3 Likes
These markets are interesting. Every day, people fear something, and then when there’s a small rustle, they panic and run aimlessly somewhere 
Try to make some sense of this, in addition to the basic advice (diversification, etc.):
-Leverage plays have gradually become a thing of the past, because the end of the world is constantly at hand. It’s better to play with futures with amounts that only cost you your pride.
-You can partially compensate for your own ignorance by putting money into funds monthly, regardless of anything.
10 Likes
Well, if the foundation is the basic advice mentioned, which has led to success throughout history with just patience, the emergency could be even greater.
One could always throw four-digit bets into football matches, for example, if one wants a casino experience.
I guess sometimes it’s also a kind of spiritual counterforce to Newton’s laws: if you rise quickly, you bounce around with the same force on the way.
3 Likes
Is today some kind of down day, or what? Has some data come in or something? Portfolio is in the red, what is this all about?
8 Likes
#investors cashed in their profits# day, it seems we’ll be seeing these for a while… The forum veterans will remember that phrase from MTV’s financial news.
7 Likes
In the casino business, there was a bit of panic about potential future taxes, and the price of copper also seemed to drop slightly. Tomorrow, they’ll probably be afraid of a solar eclipse/5G masts or something else unusual. It’s inevitably amusing how every day is somehow special from someone’s perspective in the stock market.
Your portfolio’s turnover rate is such that you probably don’t have time to notice anything but growing euros
6 Likes
The US central bankers are meeting today and tomorrow. Good reason to be nervous that what if the BRRrrrrr ends one day?
Additionally, some sly foxes dared to say “what if temporary inflation isn’t actually temporary” and the market naturally doesn’t like such talk, and since these guys can’t be burned at the stake as infidels, such talk causes nervousness.
2 Likes
I told a friend about the song, and their comment was: “Well, there’s this year’s summer hit” 
1 Like