Last week, among other things, a real estate transaction came to light, where UB Forest Fund was the buyer. Out of pure interest, I looked into what kind of plot it was, as it can be easily found with its property ID. It was a 45-hectare plot in central Finland, and based on satellite imagery, one-third of the plot is pure bog, one-third is stunted bog-mixed forest, and one-third is somewhat growth-capable-looking young coniferous/mixed forest.
I don’t know the purchase price of that particular plot, but seeing it, I couldn’t help but think how some “gel-haired” person sitting in an Espoo office is buying forests just to put cash somewhere.  However, it’s pointless to expect huge timber sales revenues from that plot.
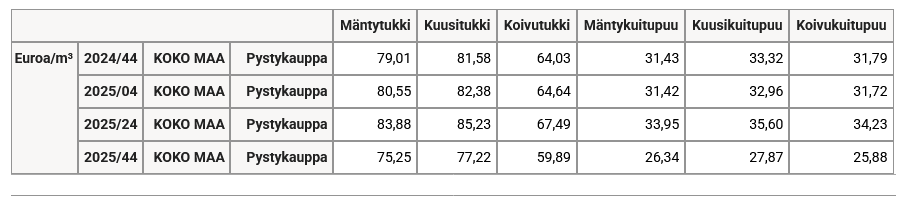
From Luke’s website, I looked at the development of stumpage prices for trees over the last year:
According to this, the price of sawlogs has fallen by about five percent across the board during the year, and the price of pulpwood by over 15%. Based on this, the highest price peak for timber might already be behind us.
These forest funds were discussed already at the beginning of the year, and my view has remained pretty much unchanged. OP-Metsä, which still presents huge return percentages, has made most of its returns through Tornator and revaluations of forests, and in my opinion, this cannot continue indefinitely. There are no buyers for the forests owned by the funds at the valuation levels of the funds, should they need to be converted into cash due to redemptions.
In my opinion, it’s only a matter of time before these funds also close their doors, similar to housing funds. In housing funds, the first redeemers still managed to save themselves before the closure.




 More than half of the people left/were sent away from Sentica already a year or two ago when the new fund didn’t materialize. So, in that sense, this was probably a way to get the last benefit out of the name. That listing plan is indeed very likely; otherwise, a share exchange would hardly have been acceptable.


 What has bothered me about the whole YLVA case is that the media has constantly talked about a “fire sale price” or “selling below fair value”. Yes, the properties were sold below book value, but that is different from fair value. The market still seems to have a strong misconception that there is some magical fair price for properties, which is clearly higher than current prices. No one says when and how this fair price will be reached, but it supposedly exists and is relied upon. This is why, for example, funds have also postponed redemptions, because they don’t want to sell properties below this mystical fair price.


