“Like in the previous quarter, the company justifies the soft performance by explaining that recent significant investments in embedded security have come at the expense of developing the Security Package business. Going forward, the company intends to invest more in the development and marketing of the security package to turn the direction around.”
-I have been paying attention to this in the company’s operations for a long time; in a fiercely competitive global market, it is impossible to succeed by splitting limited resources between two business areas that offer very little synergy to each other—at the very least, their marketing is completely different (B to B vs. B to C). According to F-Secure’s reports, they don’t support each other much from a development perspective either. Previously, during a CEO presentation, they said they were investing in the Total security package; in the next CEO presentation, he said the focus was on the Embedded market; now they are investing in the Total security package again. The focus shifts in almost every interim report. The company must split as soon as possible into two separate companies that can fully develop their own business domains, or sell one of them off. The current situation in a way reflects management’s uncertainty—they are trying to ride two horses at once, but at the same time, that could ruin the chances of success for both.
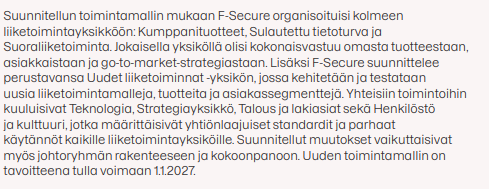
It really doesn’t make sense to split into two companies at this point anymore. But if you read about the planned operating model change, they are organizing into business units that have stricter accountability for their own performance.
Atte interviewed F-Secure’s CEO Timo Laaksonen regarding Q3
Topics:
(00:00) Intro
(00:10) ”A two-sided quarter”
(02:05) Potential contract loss and its impacts
(07:16) Operating model change
(11:57) Improving profitability
(13:12) New product solutions
We reiterate our Accumulate recommendation for F-Secure and our target price of EUR 1.70. Operationally, the Q3 figures were in line with our expectations, and the specification of the guidance was also consistent with our expectations. Our forecasts remained practically unchanged, as we had already factored in the loss of the AT&T customer and the cost savings from the operating model changes. Looking ahead to next year, F-Secure’s valuation (EV/EBIT 8.3x) is very low. We believe the valuation will correct through earnings growth, which the company continues to pursue despite the loss of AT&T. In the short term, however, a significant setback could weigh on stock sentiment unless significant positive news emerges regarding the Tier 1 strategy.
--
OP reiterates Buy and lowers target price to €2 (prev. €2.30). “Valuation has been pushed down unnecessarily low.”