By the way, I tried the competitor’s (Pragmatic’s) latest live game called… Money Time.
They have made an almost 1-to-1 copy of Crazy Time, and the only things they changed were that a couple of bonus games were different from Crazy Time. It certainly gave the impression of a so-called “knock-off,” but it’s scary how a competitor can and is able to make an almost identical copy without major problems. It certainly takes a bite out of Evolution. Pragmatic also seems to be doing well in the RNG segment and has sharpened up on the live side as well. Scary.
Evolution today announced the introduction of Ezugi as its second live dealer brand in the U.S. regulated market, further strengthening the company’s North American presence and expanding its world-class live casino offering.
New brand launch in the United States
Evolution’s upcoming live casino studio facility in Grand Rapids, Michigan will be home to a wide range of Evolution and Ezugi live titles, including Ezugi’s Ultimate Roulette and 000 Roulette, launching during the first half of 2026. In addition, Ezugi plans to bring its innovative Marble Race series to the U.S. Marble Race is an RNG-based racing game featuring five marbles on a custom-built track, with operator branding options available.
So, it seems the Michigan studio shifted from H2/2025 to H1/2026.
Could someone smarter explain this two-brand strategy? Is it just that they don’t want everything to be under Evolution’s umbrella?
Otherwise, it sounds good for progress in the regulated U.S. markets.
I’m speculating, but I’m no wiser: Evolution might change its name in a year or two, and it could even be Ezugi after that. If the Americans learn to know it by that name, then we will also have to learn a new name.
DNB Carnegie reiterates its target price of SEK 1100 and the classic “Buy the Dip in the Live Casino Industry Leader.”
Now, on October 23rd, exactly 2 weeks from now, the Q3 figures will be released. DNBC’s expectation is EUR 352.9 million EBITDA (operating profit) and an operating profit margin of 66.1%. H1 was 65.8%. EVO guides for a 66-68% range for 2025, meaning that for the rest of the year, it should clearly exceed that 66% for the company to be within that range.
Investors had argued that Evolution should be liable under US securities law, despite being a Swedish entity, because its American subsidiaries allegedly acted as the company’s “alter egos”.
However, in her ruling, Judge Mia Roberts Perez rejected that argument after months of jurisdictional discovery, finding that Evolution AB maintains “clear corporate separation” from its US subsidiaries.
Evolution CEO Martin Carlesund told NEXT.io that the expiry of the appeal deadline is “another win” for the company.
Nordea lowers target price and UBS initiates coverage with a target price of SEK 600
Was this extensive analysis, published after Q2/2025, already in this thread? It didn’t catch my eye while scrolling. Good to recall the basics of the company and speculate on future scenarios.
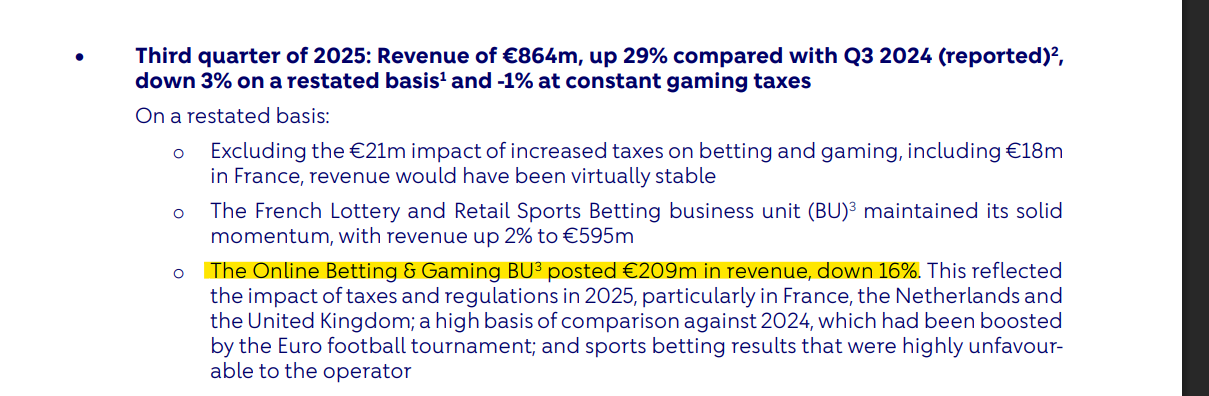
FDJ united (which owns, among others, Unibet) reported its Q3 results yesterday, where the Betting & Gaming BU’s revenue decreased by 16%.
This also indicates weak European revenue for EVO for Q3 (last year, e.g., the UEFA European Championship boosted it). Let’s hope that Asia and the US have performed strongly
Completely disagree. Do you mean that B2C operators don’t try to convert bettors to higher-margin casino products? Big events bring in more customers and customer deposits, some of which flow into iGaming products.
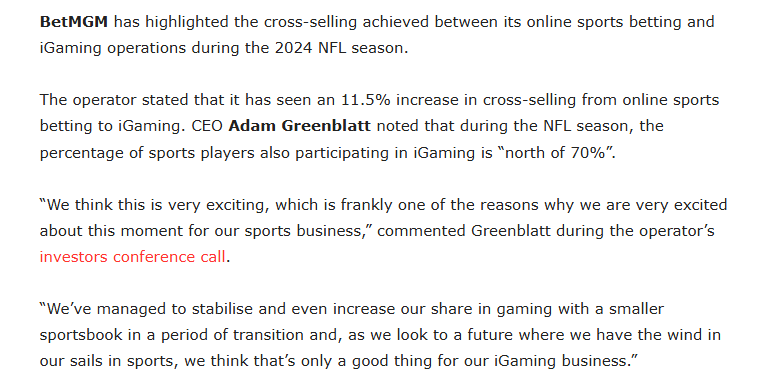
Below is MGM’s comment on sports betting cross-selling to iGaming products in FY24
The previous large(st?) owner, Capital Group, has been increasing its stake for a change, and quite significantly. Possibly just a rather opportunistic investor?
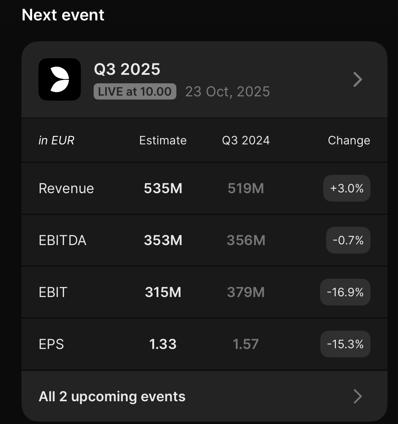
The results are indeed due on Thursday, and analysts seem to have quite weak expectations for the Q3 results. Revenue is expected to grow by 3% and the EBITDA margin to be 66.0%
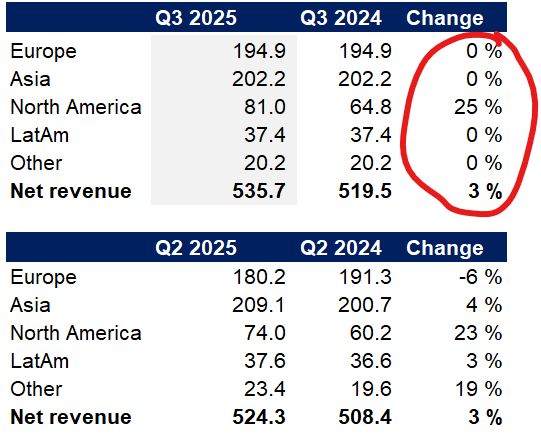
The revenue target would be met simply if all other markets were at last year’s level and the USA grew by 25% (A lot of positive news flow from the iGaming market supports the growth expectation).
Personally, I would like to see that all markets except Europe would be at least +5% Y-o-Y and the EBITDA margin +67% so there’s no need to worry about the full-year guidance.
Playtech’s reputation, if it ever really had much to begin with, takes a huge hit from this. And rightly so, completely substandard conduct. Good luck going forward.