The price was 16.00 euros
6 Likes
-
In the public offering, 125,116 Offered Shares are allocated. Commitments made in the public offering are fully accepted up to 40 Offered Shares, and if a subscription commitment was given for more than the minimum subscription amount of 50 Offered Shares, pro rata to the subscriptions made, which means approximately 45.3 percent of the commitments for the amount exceeding 50 Offered Shares; and
-
In the personnel offering, 8,618 New Shares are allocated. The company’s board of directors has decided to fully accept the commitments made in the personnel offering
After the listing sale and offering, Cityvarasto will have over 1,000 shareholders
Quite few owners resulted, and participation in the personnel offering was very weak.
I wish good luck to the new owners. Hopefully, a shareholder gets a discount when renting a storage unit.
18 Likes
An interesting company and investment target. The feeling is that people easily buy overpriced storage space for temporary use of a couple of months, but then a couple of variables come up in life for many, a couple of months stretches to half a year, and for some, the arrangement becomes permanent. If operations are automated, renting temporary storage spaces can be a good business.
In the past, I avoided this because as an unlisted company, it wasn’t interesting, and I found transactions made through Privanet difficult. Now, I will likely avoid it for at least a few quarters after the listing, as I want to see at least some earnings reports as a publicly listed company. But looking towards late 2026 and early 2027, it’s a very interesting company and a welcome addition to the stock exchange.
5 Likes
The listing didn’t go quite as planned, if you ask me. I’ll be interested to see what happens to the share price tomorrow when old small shareholders put their shares up for sale. At least they’ll make good profits. Approximately 380,000 shares have been reserved for stabilization (voluntary), and there are about 680,000 of these old shares, bought through Invesdor/Innovestor for €5-7. As an old shareholder, I would sell my shares immediately at the opening, collecting profits from years of holding.
I didn’t participate in the offering, as I was saving money for Posti’s listing.
8 Likes
I wouldn’t necessarily say it didn’t go well. It wasn’t appealing to retail investors, but foreign major investors, on the other hand, bought it. There will be fewer shares in circulation tomorrow, as institutions will only receive their shares next week.
The full number of shares will be in circulation tomorrow, and institutions can also sell their shares starting in the morning. It’s good to remember T+2 for share transactions.
The public offering went completely awry, and its volume was cut to less than half of the original amount. This made the public offering appear oversubscribed when approximately 140,000 shares were transferred to the institutional side.
In the institutional offering, anchor investors had subscription commitments up to 20 million euros at the upper end of the offering range. The price had to be lowered by one euro to raise another 20 million.
12 Likes
Agreed. I find it a bit hard to see that retail investors would have some unique insight into this company compared to institutional investors. My guess (note: purely speculative) is that the difference in opinion, if there is one, is particularly related to the quality of
1 Like
Here are yesterday’s voting results for the Seers:
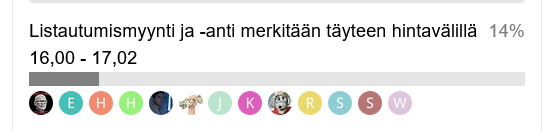
14% of voters got it right when the price settled at 16.00 euros.
Big Congratulations to all the Seers! 
8 Likes
The reason for the difference in opinion may be that a Finnish small-time investor considers this an expensive real estate investment, whereas a foreign major investor knows the valuations at which these assets trade abroad.
5 Likes
Or they don’t realize that a large part of the profit is real estate ‘appreciation’, which is valued according to the storage business. Of course, renting a few square meters yields enormous returns per square meter compared to traditional renting.
2 Likes
So did it happen that the bandwagoners were dropped, and next week we’ll rise?
2 Likes
No. It turned out that even the last smart ones jumped off the sinking ship. A rather subdued launch day. That’s a bad omen,
8 Likes
Doesn’t Cityvarasto utilize SEB’s stabilization arrangement now in connection with the listing… Hard to say how much it affects, but one could think that it pulls the share price specifically towards the listing price, as happened at the end of the first trading day (vs. the fact that the price was already 4% down).
4 Likes
It hasn’t become clear to me yet why this is or would be a €125M company.
I’ll have to observe the matter from the sidelines for a while.
4 Likes
There has been quite a lot of discussion here about balance sheet values and their changes, return expectations for self-storage units, as well as various other matters, including cash flow after investments. If I simplify my own thinking as to why I’m still not selling shares (even though I’ve been an investor in the company for a long time and have followed its development since crowdfunding), I see Cityvarasto as follows:
-
Economies of scale and brand - someone said that one can rent out a storage unit oneself with good returns. Great! I also have a real estate business that, when calculated without my own work, yields well, but considering my own work, the scaling potential is poor. Cityvarasto has a good brand, long-term customers, and a proven ability to fill new sites. There’s no reason to assume that sales wouldn’t work in the future - occupancy rates are good even in all new properties, so the business model works, has scaled, and will continue to scale. Entry into the market has proven surprisingly difficult, and new competitors have already gone bankrupt, but Cityvarasto continues to thrive with improving relative profitability.
-
Cash flow generation capability before new investments and financing costs (investments, of course, will generate more good in the future - and if the pace of investment were slowed down, the cash flow would remain with the owners). EBITDA for H1/25 was €5.5 M. Property acquisitions €2.0 M and other investments €2.2 M. If we assume that approximately €1 M of other investments are for ongoing needs (maintenance investments), the operational cash flow, including maintenance investments, was €4.5 M. Scaled for the full year, it is currently €9 M (and believing management’s comments, even €10 M this year), and growth has so far been in the tens of percent per year. I am confident that management’s promises, at least for next year, are quite solid, so let’s say that €11-12 M for next year is a perfectly valid assumption, and growth will continue beyond that.
-
Valuation - this is admittedly at a demanding level right now, depending on how one views Cityvarasto as an investment. After the share issue, net debt is approximately €25 M and market capitalization is €128 M, meaning an enterprise value of just over €150 M. EV/FCF is thus over ten even with 2026 figures (operational FCF corrected in my calculations as described above). Is this then a high level for a real estate company? If compared to residential properties, they easily go for 20x, in which case there would still be plenty of room for growth in value. If compared to service businesses, the multiple should be 5x. I personally consider the current level to be pretty much fair value for Cityvarasto (EV/FCF, for my part, could of course be even closer to ten, so I could buy more). In any case, I am not selling a quality company that has one of the longest growth streaks among listed companies behind it, and its performance shows no signs of slowing down.
17 Likes
On the Wendover channel, a video about the storage business in the United States. There is an exceptionally large number of storage units there due to a rather materialistic consumer culture. The industry has been growing for a long time, but there is also a lot of competition, and the barrier to entry is lower than for almost any other type of real estate; almost any plot of land is suitable, and the buildings are simple and cheap to construct.
Typically, the rent for storage space is very cheap at first to attract customers, and then the rent is regularly increased, with the hope that the customer won’t bother to move.
Duration 19 min.
5 Likes
Third-quarter results for the quiet thread: Cityvarasto Plc’s Interim Report 1.1.-30.9.2025: Strong Growth and Listing on the First North Marketplace - Inderes
The first earnings report was not a disappointment; hopefully, the good momentum will be maintained in the future as well. Analyst coverage would certainly be a welcome addition for a company like this. It is noteworthy that, according to the CEO, both operating segments showed positive development compared to the previous year.
8 Likes
Finnish recording:
Summary and Q&A:
6 Likes
Positive profit warning incoming
9 Likes
This is how life on the stock market is supposed to start 
It’s interesting to see what kind of growth the company targets this year, as the goal is an annual growth of 12% until the end of 2029. Ja-Ki Muutto supports growth inorganically by approximately EUR 1.0 million (3.7%), and the development of ancillary services was strong last year overall. Good performance, of course, creates tougher relative comparison periods. The leasable floor area for self-storage units had grown by 10% in Q3 compared to the end of 2024, and the total real estate portfolio by 5%.
11 Likes