Good old Pauli has put together an extensive report on Atria. 
Atria is one of Northern Europe’s leading food companies and a major player in the meat industry. The company’s new growth-oriented strategy continues to emphasize growth segments, but also aims to strengthen exports and cross-border sales between operating countries. The extensive investment program included in the strategy is weighted towards 2026–27, after which we see more significant earnings growth potential starting from 2028. We see the valuation as attractive (P/E 9x), considering the predictability of the company’s earnings and a reasonably good value creation profile in the context of the industry. We reiterate our Accumulate recommendation and a target price of EUR 18.
Quoted from the report:
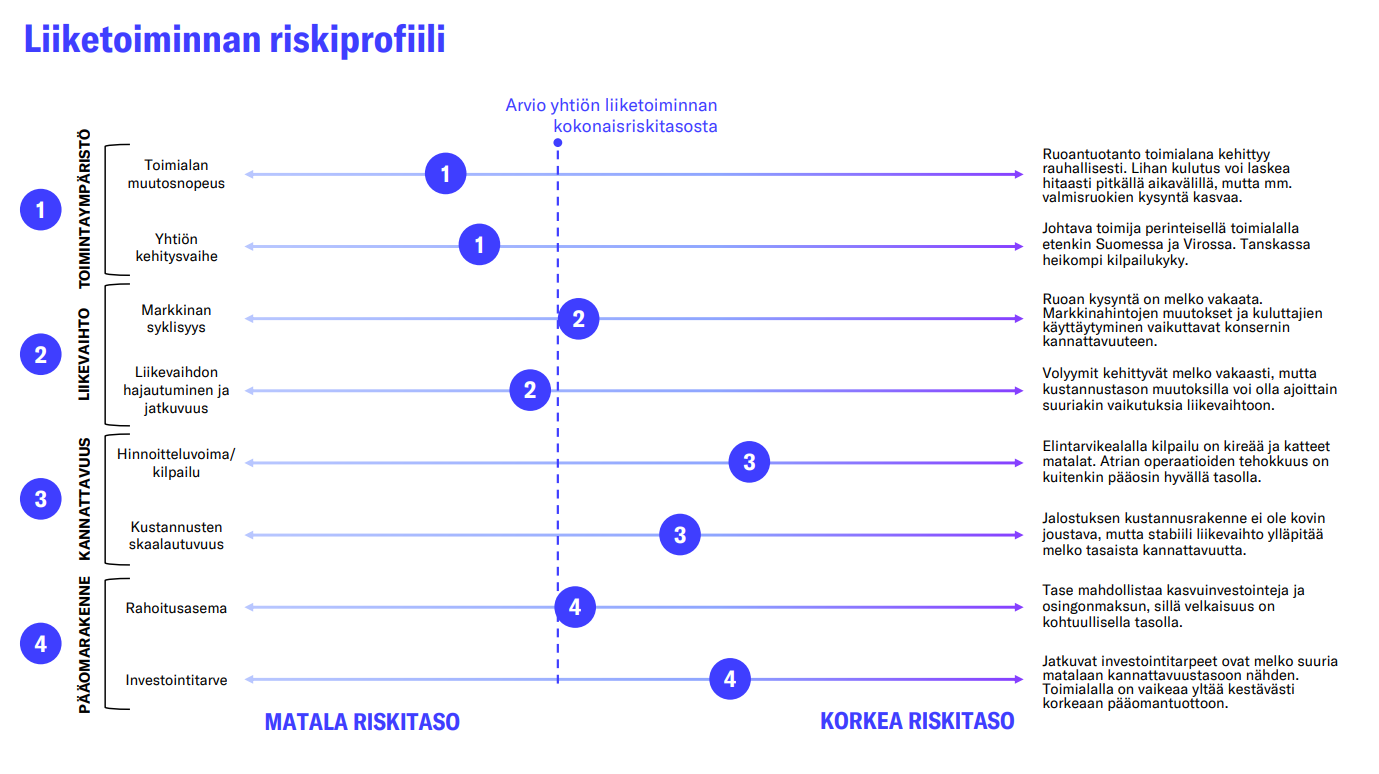
The balance sheet has sufficient capacity for growth projects
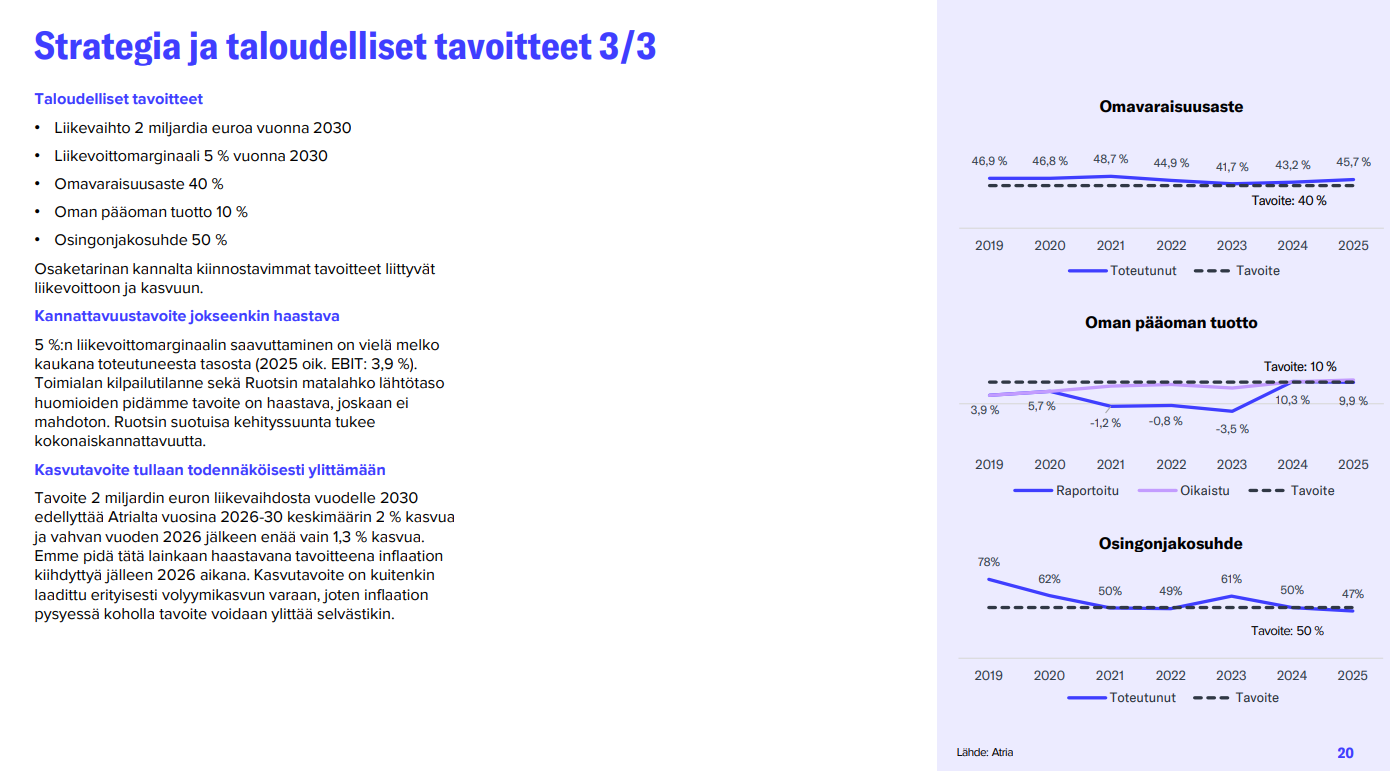
Atria has a significant amount of interest-bearing net debt on its balance sheet (2025: EUR 219m, Q3’26: EUR 284m), but leverage is at a reasonable level relative to earnings (Q3’26: 2.0x adj. EBITDA) - especially considering the company’s relatively stable earnings history. The equity ratio stood at 44% at the end of Q3’26, while the company targets a level of at least 40%. Typically, the company’s business does not tie up a huge amount of working capital, as receivables and inventories can be financed through accounts payable and factoring (estimated at EUR 100m). Accelerating inflation can often temporarily tie up working capital, as seen for instance in 2022 (general inflation) and to a lesser extent in 2026 (following the rise in beef prices). We assess that the balance sheet allows for small or medium-sized acquisitions as well as carrying out the announced significant industrial investments.