Here are Kassu’s preview comments as Aktia publishes its Q3 report on Thursday.
We expect Aktia’s earnings to have continued their decline due to shrinking net interest income. We estimate general loan demand to have remained relatively stable, meaning we do not expect the clear growth in the corporate loan portfolio seen in the previous quarter to have continued as vigorously. We would also gladly hear the new CEO’s comments on the lending outlook, as the messages provided by macro data have remained mixed. Furthermore, our interest is focused on new sales in wealth management, which is one of Aktia’s key earnings growth drivers.
Everything is almost ready… Tomorrow, November 6, 2025, Aktia’s Q3 report will be published at approximately 8 AM. At 10:30 AM, a webcast will begin, where together with CEO Anssi Huhta and CFO Sakari Järvelä, we will go through the quarter’s results. Welcome to join us: https://aktia.events.inderes.com/q3-2025
Net interest income decreased as expected, and specifically, it reduced earnings.
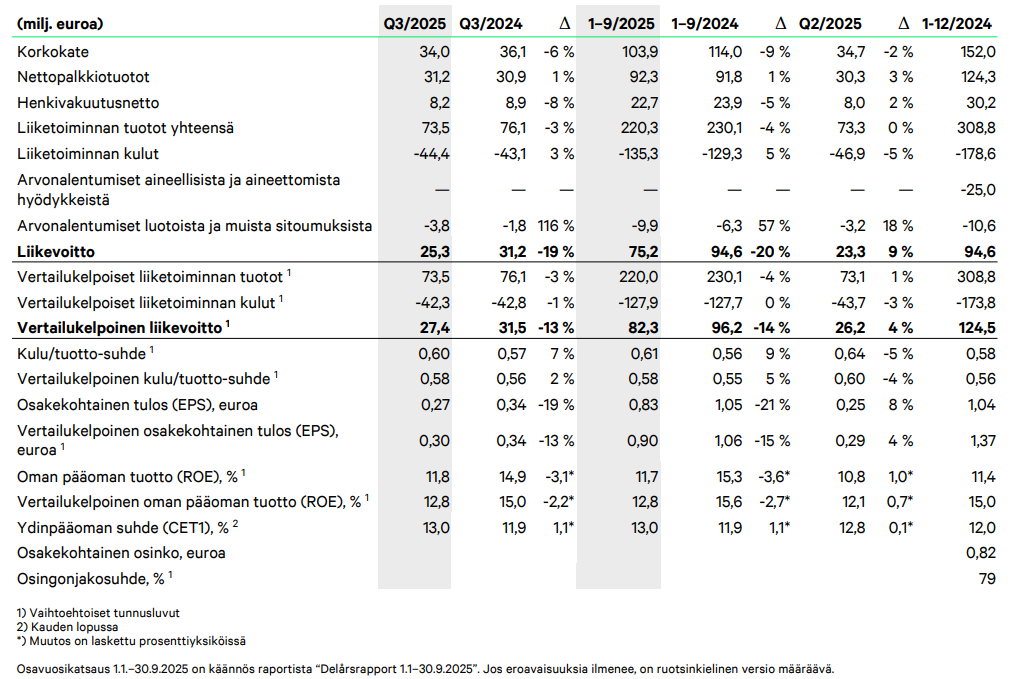
A quick look at what was left for us shareholders: EPS 0.34 (3Q2024) → EPS 0.27 (3Q2025) (0.30 adjusted). Correspondingly, 1-3Q2024 (1.06) → 0.83 (3Q2025) (0.90 adjusted).
Quarter in brief
Comparable operating profit: EUR 27.4 million, 13 percent lower than last year (31.5) mainly due to the changed interest rate situation.
Comparable return on equity (ROE): 12.8 (15.0) percent.
Net commission income: 1 percent higher than last year mainly due to the growth in income from structured products.
Net interest income: Decreased as expected and was 6 percent lower than last year due to the decline in market interest rates.
Net life insurance income: 8 percent lower than last year, which was due, among other things, to the decrease in real estate values. Insurance operations developed well.
Comparable operating expenses: Decreased by 1 percent from last year; focus on cost discipline continues.
Credit losses: EUR 3.8 (1.8) million mainly due to individual impairments of some loans.
Assets under management: Grew by 2.3 percent during the quarter to EUR 16.3 billion due to positive net subscriptions from all key customer segments and favorable market development.
Here are Kassu’s comments on the morning’s results. Aktia’s Q3 results did not offer any significant surprises. Revenues declined as expected along with the net interest income, which also kept comparable operating profit down. Both asset management sales and demand for new loans remained at a rather subdued level. However, the quality of the loan portfolio deteriorated, which also led to an increase in credit loss provisions.
Kasperi interviewed Aktia’s CEO Anssi Huhta after the Q3 results were released.
Topics:
00:00 Introduction
00:17 Q3 highlights
00:45 Development of loan demand
02:04 Growth in leasing, factoring, and hire purchase portfolios
03:15 Credit loss levels
05:06 When will the interest rate margin bottom out?
06:01 Improving asset management sales
07:00 Competitiveness of the product range
07:46 Impact of personnel changes on the organization
09:57 Impacts from the perspective of personnel and customer relationships
10:53 Does Aktia need something new in its operations?
Kassu has made a new company report on Aktia after Q3.
Aktia’s Q3 results did not offer any significant surprises. However, we slightly raised our earnings estimates for the coming years, especially due to the well-developed life insurance net. We still consider Aktia’s valuation to be inexpensive and see the dividend yield, together with the potential for valuation multiples to rise, offering investors an attractive return expectation. We reiterate our add recommendation and raise our target price to EUR 11.0 (previously EUR 10.5) in line with the forecast increases.
Quoted from the report:
We have examined Aktia’s valuation through balance sheet multiples, Nordic banking peers, and a dividend model. The methods indicate a share value of EUR 11.3–12.7, with the midpoint being approximately EUR 11.8. Overall, we still consider Aktia’s valuation to be inexpensive, and we see the potential for multiples to rise and a strong dividend yield (~8–9%) offering investors a good return expectation. However, the subdued development in wealth management and discontinuities due to personnel changes may delay the progress of the growth turnaround, which in turn dulls the sharpest edge of the return expectation.
I don’t doubt Aktia’s traditional banking operations, but for me, the most important question regarding Aktia is, by what means will the 2029 strategic goal of 25 billion in assets under management be achieved?
From the current approximately 16 billion, reaching the target would require an average annual growth of about 12% over each of the four years. If successful, that would probably enable an increase in valuation level as well, but by what means is that feat intended to be accomplished?
Even in Kasper’s analysis, it is stated that assets under management have grown mainly with the market, but that is not enough to reach the target; new customers are needed. With what product will they be acquired?
To this, I would point out that the last few quarters have not been bad in terms of sales; quite reasonable amounts have been sold to private customers. But as you said, to reach the targets, the pace should be accelerated, and preferably, assistance should be sought from the institutional side, where capital has continuously decreased in recent years.
They are hardly at the top of the plans, at least after the Taaleri deal. Now the management has left the door open for an even larger profit distribution, and I understand that they do not want to publicly anchor investors’ expectations to any specific level. In the coming years, however, profit distribution must increase if they want to maintain their solvency at their target level (~4% above the regulatory requirement). With a 60% payout ratio, the balance sheet is constantly strengthening, and I don’t see a need for this, especially since the intention is to grow in capital-light asset management. Of course, some changes may come from the regulation side; for example, the Financial Supervisory Authority has recently raised the capital requirements for some banks. However, this should not have a dramatic effect on the outlook for profit distribution.
Here’s one observation from the loan market, by the way. After this Helsingin Sanomat article, I dug up information on Ylva’s financiers, and at least in the 2021 financing package, Aktia was involved based on information available from public sources. Could this then be the single real estate sector player that has accounted for 40% of Aktia’s loan loss provision growth this year (EUR 4–5 million)?
This is mainly an interesting observation, as I don’t believe that significant loan losses will arise from this anymore, even if this particular case is in question. However, the selling price was largely known during Q3, and Aktia’s loan loss accounting policy has never surprised me. Large individual loan losses certainly explain, in part, why the bank aims to reduce its corporate customer sizes in the future.
Here are Kassu’s comments after the Financial Supervisory Authority slightly raised Aktia’s capital requirement
The 0.25 percentage point increase in the additional capital requirement is small, and its impact on the bank’s overall solvency is minor. Therefore, the announcement does not affect our assessment of Aktia’s dividend distribution potential.
A small piece of news from Aktia yesterday regarding an arrangement where the bank has acquired a majority stake in Suomen Yrittäjäturva. This is a joint venture established by Aktia and Veritas, whose task is practically to sell various insurance products. Consequently, the arrangement can be seen as a stronger investment in the insurance sector by Aktia than before. No significant change is occurring here, as Yrittäjäturva has been selling Aktia’s products before. However, the brand is changing from Suomen Yrittäjäturva to Aktia Yrittäjäturva. The income statement won’t be shaken by this subsidiary status either, as sales are commission-based due to the tied agent structure. The purchase price was not mentioned in the press release, but it is likely low due to the company’s business model (a sales organization with results close to zero).
Here is Kassu’s preview as Aktia releases its Q4 report on Thursday.
We expect the bank’s comparable result to have decreased from the comparison period as a result of a contracting net interest income. In the report, our attention is particularly focused on the development of asset management new sales, which is a key driver in the company’s long-term growth strategy, as well as the earnings outlook for the current year 2026.
From the analyst’s comment: “In asset management, assets under management developed well and the fee level remained stable. Gross assets under management grew by approximately 1.8% from the previous quarter to EUR 16.6 billion, thanks to both positive net subscriptions and value changes. Compared to peers that have already reported their results, the figure is not high, but considering Aktia’s weak new sales in recent years, the direction is nonetheless correct. The majority of new sales came from international institutional clients, while net subscriptions from Private Banking clients turned negative.”
It’s great that international institutions have become interested. Growth driven by aging Swedish-speaking Finns cannot be relied upon in the future.