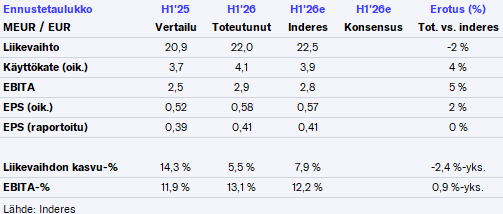
It would be interesting to see a forecast that takes into account the revenue growth generated by acquisitions in line with the company’s strategy for the coming years as well. There is already about half a dozen years of history behind us, the strategy has been implemented consistently, and as far as I know, there have been no changes to it. I don’t recall seeing this growth included in the forecasts used for calculating the target price. Perhaps the “Robo” [analyst model] considers something for next year.
The readiness to pilot their own accounting module says a lot about how significantly software development costs have decreased over the last 20 years. In my opinion, there is no major risk involved in Aallon Group’s lean development strategy. In fact, I think now is the perfect moment to implement such proprietary software; the implementation is, of course, natively web-based, but development can also natively take into account the possibilities brought by AI. Adding those to existing heavy and rigid systems is difficult, but at this stage, it is an interesting opportunity.
I also think it is completely clear that proprietary software development is the only right way to keep software costs reasonable, and combined with that, sufficient independence from any single software vendor is sensible. I have been slightly surprised by some of the fearful comments regarding this. As an investor, I am personally very happy that they are investing in such an important matter, which could drive both the company’s earnings and the share price significantly higher with almost negligible risk given the current investments.
A comment on AI. AI offers possibilities, but I think its threat to this industry is greatly exaggerated. It’s a bit like, after the development of the internal combustion engine, thinking that everyone will soon be traveling into space in their own rockets. Let me explain.
If you understand the growing requirements of AI from the perspectives of data volume, complexity, error-proneness, the difficulty of verifying errors, and increasing liabilities, you quickly notice that we are on an exponential requirement curve that it is not realistic for AI to reach without the industry being able to essentially adapt to it.
Error-proneness is in the genes of all generative large language models (x.AI, Claude, ChatGPT, Perplexity), and it hasn’t been solved, nor has any credible solution model been proposed, at least publicly. There is hype, certainly.
A separate challenge is posed by the interpretability and even contradictions in Finnish legislation, collective agreements, Supreme Court (KKO) decisions, guidelines, and so on. Accounting firms have liability insurance for errors, but, for example, Anthropic is unlikely to bear financial responsibility if Claude makes significant mistakes in the future, say, towards the tax authorities. Here we arrive at a problem somewhat similar to the one where if a Tesla in self-driving mode gets into an accident, who is responsible—the company that coded the AI or the owner of the car? When will Tesla start bearing responsibility for this? Never?
In my view, AI assistants will not achieve the capability to provide the level of financial management services that client companies need, at least when dealing with companies that are even remotely profitable. For the reasons mentioned above. Various stock portfolio companies are not the core business of the accounting industry, but rather a bit more like low-margin charity work. The idea that AI assistants would replace the need for financial management services for accounting firms’ highly profitable clients and thus significantly reduce the profitability or necessity of the accounting industry is, therefore, not realistic in my opinion yet.
Furthermore, services from efficient AI models are, for the most part, paid or are shifting to a paid model. For example, ChatGPT’s best model (PRO) costs over €100/month for a private individual (ChatGPT pointed out that the list price in the US is $200), so I wouldn’t consider it free either. Nor is there any sign of these costs going down in price trends—on the contrary. Among other things, rising energy costs and fiscal needs are set to grow in the future, but improving profitability is also necessary when investments are astronomical. The payers will be the users of these models, most likely companies in particular.
Of course, there is all sorts of talk, claims, and “information” about AI that different “players” use to serve their own interests. Or should we think that it’s best to just sell all stocks (or even that it’s good to sell) because Musk promises that in the future we won’t need to work, as androids will do all the work for free, meaning we won’t need companies anymore—and thus there won’t be, or won’t be a need for, company shares when companies are run by those same androids?
It would be interesting to hear what the target price for Aallon Group’s stock would be if AI were not primarily seen as a threat and future forecasts were in line with that. Or at least, I felt that strict lines were drawn now when it was seen as a threat, like Andromeda in its time.
Perhaps one could think at least that positive expectations (new services, better software, efficiency) and negative expectations (less need for service) cancel each other out, since these are speculative matters anyway??
In my opinion, the €10.50 target price feels very low. It also seems that the stock price follows the target price quite slavishly, staying about 1–2 euros below it.
ps. ChatGPT did not, at least in any significant way, disagree with the points I’ve presented here and nicely stylized this text as well. Some things are matters of opinion.

 The point earlier was precisely that I always try to preemptively shave a bit off those reported figures for the coming years to account for that “backboard leakage” (churn). Well, after the first year, that acquired revenue then develops “organically,” and the expectations set in the model for organic growth also apply to that revenue. Historically, my own organic growth assumptions have been too optimistic compared to the actual results. This has been partly influenced by the stagnation of the Finnish economy.