Here is a comprehensive report on Aallon Group from Atte 
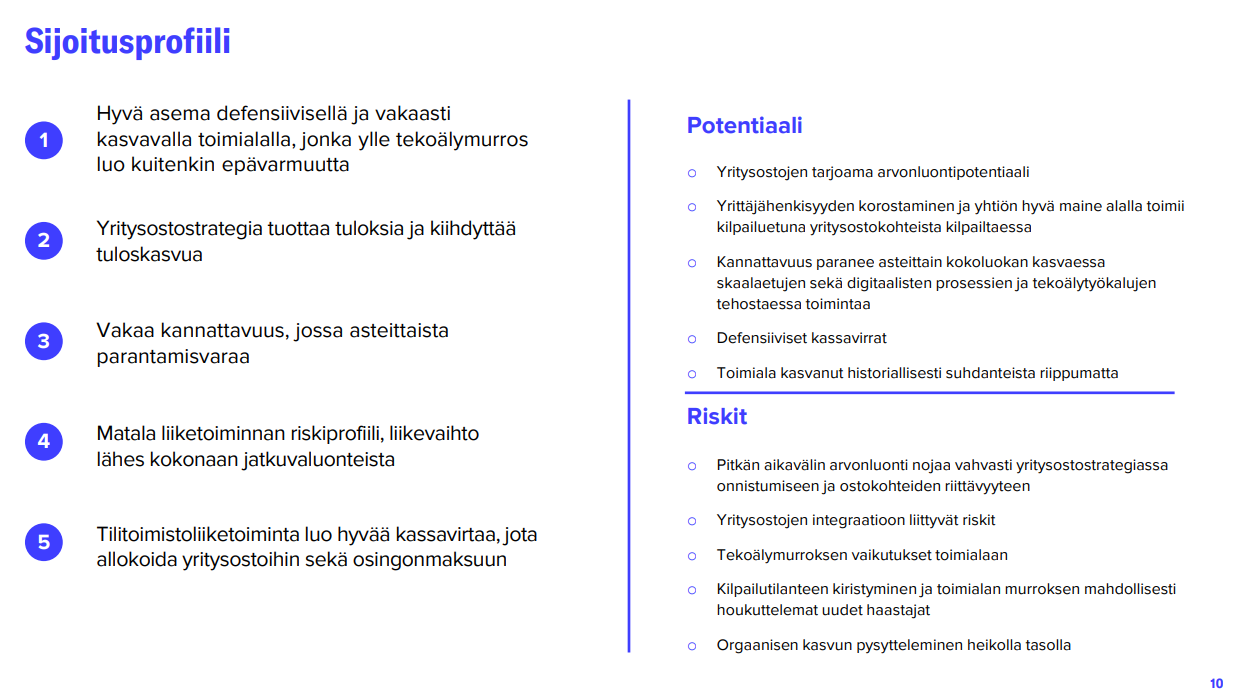
We reiterate Aallon Group’s accumulate recommendation and target price of EUR 10.5. The profitability improvement seen in H1’26 shows that the company’s implemented organizational restructuring is starting to bear fruit, and additional efficiency is being sought through the launched lean development program. Slow organic growth in recent years and uncertainty related to the AI disruption have weighed the stock’s valuation down to a very low level (2026e-2027e EV/EBIT 9x-7x), and expectations for future development are very modest. In our view, this makes the risk-reward ratio attractive, as we believe the company will continue its M&A activity, and the nascent recovery of the Finnish economy may also begin to gradually support performance starting next year.
Quoted from the report:
Fair value
In our view, assuming a slow organic growth outlook, Aallon Group’s fair P/E multiple could be around 10x-13x. If our 2027 forecasts materialize, the stock could therefore already have clear upside potential (23-40%). However, as the AI disruption continues, we see achieving the upper end of the valuation range as uncertain in the short term. The company’s recurring business model and strong cash flow support the valuation. On the flip side, the company’s small size and the stock’s low liquidity weigh down the acceptable valuation. At our target price, the stock would be priced at a P/E multiple of approximately 11x for this year, and the corresponding multiple for 2027 would be about 10x.