I finally received the 2025 financial statements for Hoiva, and I have updated the previous table accordingly. Hoiva performed better in 2025 than in 2023–2024, as the drop in interest rates favored the fund as expected. Cash flow yield improved clearly, and in 2025, Hoiva generated a 2.5% cash flow yield for its owners.
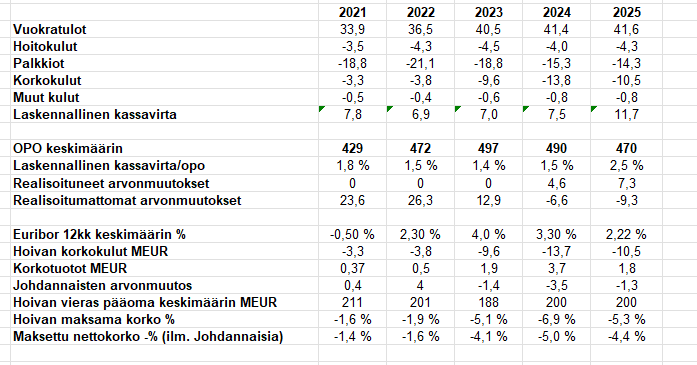
As I have calculated here previously (e.g., here: Titanium - Kasvun toista tukijalkaa etsimässä - #2078 käyttäjältä Sauli_Vilen), Hoiva’s cash flow yield should be slightly over 3% at current interest rates. The 2025 yield is weighed down by a cash position of over 60 MEUR. I see no reason to change my previous assumptions regarding this. For newer readers, it is worth noting that the 2021–2023 cash flows were dragged down by performance fees/transaction fees, which significantly penalized an otherwise good cash flow. Now, the fees are permanently lower, but unfortunately, the bank requires much higher compensation from the fund than before.
Regarding the PE fund, sales have unfortunately turned into a downward trend. Net subscriptions were 13 MEUR in Q4’25, 8 MEUR in Q1’26, and only 5 MEUR in Q2’26. That 5 MEUR/Q is only 20M/year, and that level is helplessly too low if the intention is to fill the upcoming crater in Hoiva. One can only hope that this weakness is explained by good progress in wealth management.