Redeye Premium news comments. I myself bought a small amount last week at an average price of 82.64. Today you could get it even cheaper. Yesterday it went below 80 Kr. Perhaps this will turn into joy again once people realize that gaming hasn’t stopped.
So the main point in that Premium comment was that Stillfront is cheap compared to its peers right now and there’s > 50% upside to Redeye’s Base price.
{“content”:“As someone working in the field, I would say it’s simply due to Stillfront’s games having above-average monetization. Often, the most popular free-to-play games and top-grossing games are not at all the same. Any fleeting weekly fad can make it onto the free list, but they have no business in the top-grossing category. Also, a highly monetizing game can be profitable with a smaller target audience, which is then targeted with ads, but they never attract large masses. Different game categories also affect monetization. A cute children’s game can be really popular, but you can’t put in-app purchases there.\nSo I wouldn’t draw any conclusions from this.”}
“In addition, we have ongoing dialogues with several targets and review hundreds of potential studios each year, and we feel very confident about the acquisition pipeline for the rest of the year.”
Waiting for new acquisitions. Based on this comment, several more might be coming this year.
I have been following Stillfront lately (and adding Embracer). The Q1 figures are strong in themselves and the forecasts were exceeded, but organic growth is now below 10% and the average payments per player have decreased.
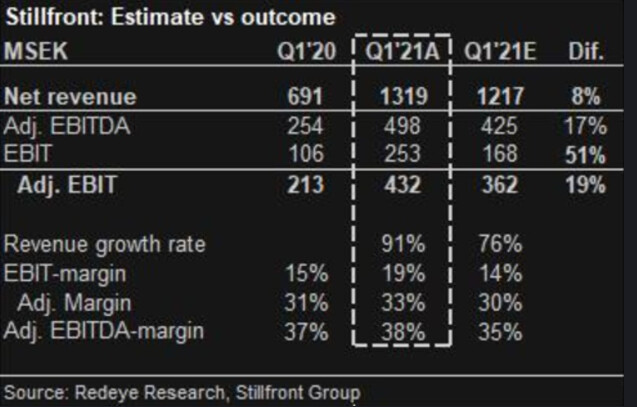
Revenue 4% higher than expected. Adjusted EBITDA 9% better than expected with a margin of 33% up from 31% in Q1 2020. Organic growth +9.5%
Average revenue from daily active user -43% y/y and -30% q/q
The transfer from First North to the main list is in full swing and may happen in the near future, in the coming months.
Perhaps the organic growth figures can be explained by last year’s strong figures (it will be interesting to compare them to Embracer).
STILLFRONT
EXPECTS NEGATIVE ORGANIC GROWTH IN Q2 (Direkt)
2021-05-05 07:20
STOCKHOLM (Nyhetsbyrån Direkt) Gaming company Stillfront expects negative organic growth in the second quarter due to tough pandemic-affected comparison figures.
This is stated in the interim report.
“From mid-March until the end of May last year, we experienced a large influx of new users due to the exceptionally good marketing conditions during the outbreak of covid-19. The tough comparison figures have had a negative impact on our organic growth at the end of Q1 and we expect the same comparison effect to lead to a negative organic growth figure in Q2 2021”, writes the company’s CEO Jörgen Larsson in the report.
Solid start to the year in
line with our expectations
• A solid start to 2021 with continued strong
growth and high profitability, in line with our
expectations
• Strong pipeline of games entering soft launch
in 2021
• Tough comparison numbers expected to lead
to a negative organic growth rate in Q2
• Intensified process to transfer from First
North to Nasdaq Stockholm’s main market
Net revenue of 1,319 (691) MSEK, an increase of 91 percent compared to the first quarter of 2020, of which 9.5 (10.2) percent was organic
EBIT of 253 (106) MSEK, an increase of 138 percent
Adjusted EBIT of 432 (213) MSEK, an increase of 103 percent, Adjusted EBIT margin of 33 (31) percent
Items affecting comparability impacting EBIT amounted to -35 (-50) MSEK, mainly driven by transaction costs related to the acquisition of Moonfrog Labs. Amortization of PPA-items amounted to -144 (-56) MSEK
Financial net of -45 (-4) MSEK
Net result of 148 (77) MSEK
Net result per share undiluted of 0.41 (0.29) SEK. Net result per share diluted of 0.41 (0.28) SEK
Net debt of 3,116 (1,787) MSEK and adjusted leverage ratio, pro forma of 1.3x (1.2x)
Cash position of 1,225 MSEK and 1,211 MSEK of undrawn credit facilities
RedEye remains optimistic, and the base case currently shows over 50% upside. They state that the risk-reward ratio is currently very attractive. Expectations were exceeded. Stillfront lowered its Q2 organic growth expectations, reflecting the corresponding period last year when the pandemic caused a significant boost.
“Founded in 2015, Game Labs is a rapidly growing independent game studio with a strong track record of developing strategy and action games for PC”
“Game Labs is expected to generate proforma IFRS net revenue of approximately SEK 70-80 million and an adjusted proforma IFRS EBIT margin of approximately 50-55 percent for the full year 2021. The financial assumptions in 2021 is based on forecasts for the acquisition and the expected growth is fueled by a planned early access release in the last quarter of 2021. The transaction will result in an attractive earnings multiple for Stillfront in line with previous acquisitions. The implied EV/Adjusted EBIT 2021 multiple will be 6.9x, assuming a mid-range EBIT for 2021”
Stillfront has had a cold ride on the stock exchange today. Apparently, there was an analyst call from which Pareto had said something to Dagens Industri → -12% from yesterday, stock price 10% below RedEye’s Bear case. -71% to the Base case. I had to buy more because I couldn’t find that story anywhere to read.
It’s quite baffling that Stillfront’s organic growth apparently won’t even be positive in Q3. Pareto’s information is based on an analyst conference they had with Stillfront representatives. At the same time, however, the mobile gaming market is growing strongly. Competition is tough, and quality is coming from other companies. I won’t be investing in this.
Organic growth is weak, which the company admits. If Stillfront’s games truly faced as much pressure during the worst COVID-19 quarters as shown in the organic growth figures, is it ultimately acceptable? When looking at the first quarter’s performance, it’s certainly not bad—not at all! Okay, organic growth is faltering, but otherwise, the pieces are falling into place admirably.
Stillfront’s own targets are:
Stillfront´s target is to reach a net revenue of 10,000 MSEK by 2023. Growth will be achieved organically as well as through acquisitions.
Stillfront´s target is to reach an Adjusted EBIT margin in the region of 35 percent. The Adjusted EBIT margin is defined as EBIT excluding amortization of PPA-items and items affecting comparability, in relation to net revenue.
The net debt/Adjusted EBITDA ratio should not exceed 1.5x.
Redeye’s forecasts were broken quite clearly, and they have stated that they believe the company is very likely to achieve its own targets. Even in light of Redeye’s conservative forecasts, there is significant upside/potential, not to mention a likely, quite large, upside from this. Growth rate in the table, EBIT margin… clearly, results are being generated, acquisitions are good, so how much weight should be given to organic growth at this stage?
Bring your own perspectives to the table! What value do you see in organic growth, the company’s outlook, etc.
Even looking at the highlights, you’ll find so much positive news there..
Stillfront’s soft figures are in, falling somewhat short of average estimates. At the same time, the guidance for the next quarter, which I interpret as negative. Of course, they are comparing to strong previous quarters, but still, considering the continued growth of mobile games.
Edit: Has investor communication been truly successful when negative information has long been known by some analyst firm through a conference call? One had to read about it in the general comments section when the stock price dropped particularly sharply.
FINANCIAL HIGHLIGHTS Q2
Net revenue of 1,382 (1,192) MSEK, an increase of 16 percent compared to the second quarter of 2020, of which -17 (22) percent was organic
EBIT of 289 (336) MSEK, a decrease of 14 percent
Adjusted EBIT of 477 (463) MSEK, an increase of 3 percent, Adjusted EBIT margin of 35 (39) percent
Items affecting comparability impacting EBIT amounted to -25 (-33) MSEK, mainly driven by costs for the listing change and costs related to the acquisition of Game Labs. Amortization of PPA-items amounted to -163 (-94) MSEK
Financial net of -72 (-85) MSEK
Net result of 149 (188) MSEK
Net result per share undiluted of 0.41 (0.57) SEK. Net result per share diluted of 0.41 (0.57) SEK
Net debt of 3,584 (665) MSEK and adjusted leverage ratio, pro forma of 1.6x (0.4x)
Cash position of 850 MSEK and 2,605 MSEK of undrawn credit facilities
The gaming industry is currently in such a slump that it cannot afford such reports. It might not be a completely hopeless case if one wants to buy lower and stay in for the long haul. However, I’m getting off the train at this station. Almost 50% loss (94 SEK → 50 SEK), but luckily it was a small position.
“Redeye has updated its estimates and fair value range after Stillfront’s Q2 results where we have lowered near-term growth expectations while the medium to long-term outlook remains positive.”