Stillfront’s latest acquisition, Everguild. Interesting-looking game genre, I need to try playing it.
I’m putting out the information published by Swedbank on how they see Q3:
Stillfront Group
| Recommendation: | Buy (Buy) |
|---|---|
| Target Price: | 1,150.00 SEK |
| Price: | 1,002.00 SEK |
| Analyst: | Hjalmar Ahlberg |
| Equity Analyst |
Analysis produced by Kepler Cheuvreux on 2020-11-11 at 07:50, and translated and distributed via Aktiellt on 2020-11-11 at 08:23.
AFTER REPORT
Q3 in line with expectations
Stillfront’s revenues for the third quarter were slightly weaker than expected, while EBITDA and adjusted operating profit were in line with market expectations. At the net profit level, the company was affected by an unusually high tax rate, a level the company does not expect going forward. Growth was negatively impacted by currency and seasonal effects during the third quarter. The company emphasized that it expects the large influx of players seen during the second quarter to remain long-term players of Stillfront games. In combination with the consolidation of the Nanobit acquisition in October, this provides positive outlooks for Q4, which is a seasonally stronger quarter. Overall, we expect the share to have a neutral reaction today, as it has performed weakly leading up to the report. We expect limited changes to market forecasts in light of the report. We reiterate Buy with a target price of SEK 1,150.
Stillfront’s Extraordinary General Meeting on December 17th, agenda includes:
- Stock split 10:1
- Authorization for new shares (dilution not to exceed 10%)
2 Likes
Stillfront Group presents unaudited proforma financials for YTD Q3 2020 and FY 2021 guidance for the acquisitions of Super Free Games and Sandbox Interactive
INSIDE INFORMATION: Stillfront Group AB (publ) (“Stillfront”) earlier today announced the signing of agreements to acquire 100 percent of the shares in Super Free Games, Inc. (under name change from Super Lucky Casino Inc.) (“Super Free”) and Sandbox Interactive GmbH (“Sandbox”) for a combined upfront payment of approximately SEK 2.6 billion (the “Acquisitions”). As a result of the Acquisitions, Stillfront has decided to communicate that its proforma Net revenue and adjusted EBITDA including the Acquisitions amounted to SEK 3,550 million and SEK 1,373 million, respectively, for the period January to September 2020. Furthermore, Stillfront estimates that the Acquisitions will contribute with proforma Net revenue and adjusted EBITDA to Stillfront for the full year 2021 in the range of SEK 1,500-2,000 million and SEK 350-450 million, respectively. All numbers are preliminary and unaudited. Closing of the acquisition of Sandbox is expected no later than 30 December 2020 and closing of the acquisition of Super Free is expected no later than 29 January 2021, as communicated separately earlier today.
3 Likes
Sandbox Interactive
- The total upfront consideration payable upon completion of the acquisition of 100 percent of the shares in Sandbox amounts to EUR 130 million on a cash and debt free basis (the “Upfront Purchase Price”). Of the Upfront Purchase Price, approximately EUR 30 million, is payable in 337,403 newly issued shares in Stillfront, and the remaining part of the Upfront Purchase Price, equivalent of approximately EUR 100 million, is payable in cash to the sellers.
- In addition, the sellers may receive an earn-out payment of 1x EBIT for each of the financial years 2021, 2022, 2023 and 2024 (the “Earn-out Purchase Price”), depending on the level of EBIT generated during each of those years, payable approximately 78 percent in cash and approx. 22 percent in newly issued shares in Stillfront.
- Sandbox has a preliminary unaudited IFRS converted net revenue and adjusted EBITDA for the period Jan-Sep 2020 of approximately EUR 9.5 million and approximately EUR 5.2 million, respectively.
Stillfront Group acquires Sandbox Interactive, a cross-platform free-to-play MMORPG studio – Stillfront Group
Super Free
- The total upfront consideration payable upon completion of the acquisition of 100 percent of the shares in Super Free amounts to USD 150 million on a cash and debt free basis (the “Upfront Purchase Price”). Of the Upfront Purchase Price, 47.5 percent, equivalent of approximately USD 71 million, is payable in cash, and 52.5 percent, equivalent of approximately USD 79 million, is payable in 750,324 newly issued shares in Stillfront to the sellers.
- In addition, the sellers may receive an earn-out payment of 0-2x EBITDA for each of the financial years 2021, 2022 and 2023 (the “Earn-out Purchase Price”) depending on the level of EBITDA generated by Super Free during each of those years, whereof 47.5 percent is payable in cash and 52.5 percent in newly issued shares in Stillfront to the sellers.
- Super Free has a preliminary unaudited IFRS converted net revenue and adjusted EBITDA for the period Jan-Sep 2020 of approximately USD 57.6 million and approximately USD 8.7 million, respectively.
Stillfront Group acquires Super Free Games, a leading developer of Casual Word games – Stillfront Group
So, through Sandbox, there’s a direct dilution of €30M, and through Super Free, about €65M. This means it’s not a huge dilution to the current market cap of approximately €3.2 billion. Of course, there are also potential bonus systems in 2021-2024. I also noted that the Q1-Q3 reported EBITDA was SEK 1,135M, which is about a 21% increase in EBITDA due to the acquisitions, assuming that SEK 1,373M eventually holds true. Correspondingly, net revenue was 2,910, or about a 15% increase. Am I missing something here?
At first glance, Sandbox seems to be operating with a really strong EBITDA margin, but the price paid for it in euros was also quite high. The stock price has been slowly declining for a while, and this company still doesn’t seem expensive if you look at the 2023 target: SEK 10,000M in revenue and a 35% adjusted EBIT margin. However, if they’re making acquisitions at over 10x sales, like with Sandbox, then I’m not so sure anymore.
What are your overall thoughts on these acquisitions, @KimiN?
2 Likes
Hey, I’m a bit busy with work now and haven’t really had time to digest and familiarize myself with the acquired companies yet. I’ll have to try to think it over and look at the bigger picture this weekend.
I made a company page for this, so the announcements will start coming here now  Stillfront Group - osake - Inderes
8 Likes
RedEye published a company comment after the acquisitions and an updated valuation table with pro forma figures.
This doesn’t seem very expensive with 2021 forecasts. Pro forma EV/EBITDA 13 and EV/S 5…
I’ve been following Stillfront on my watchlist since the summer, but after yesterday I decided to take a position…

7 Likes
To the Indian gaming market:
https://twitter.com/alexisbonte/status/1356150055347093508?s=21
1 Like
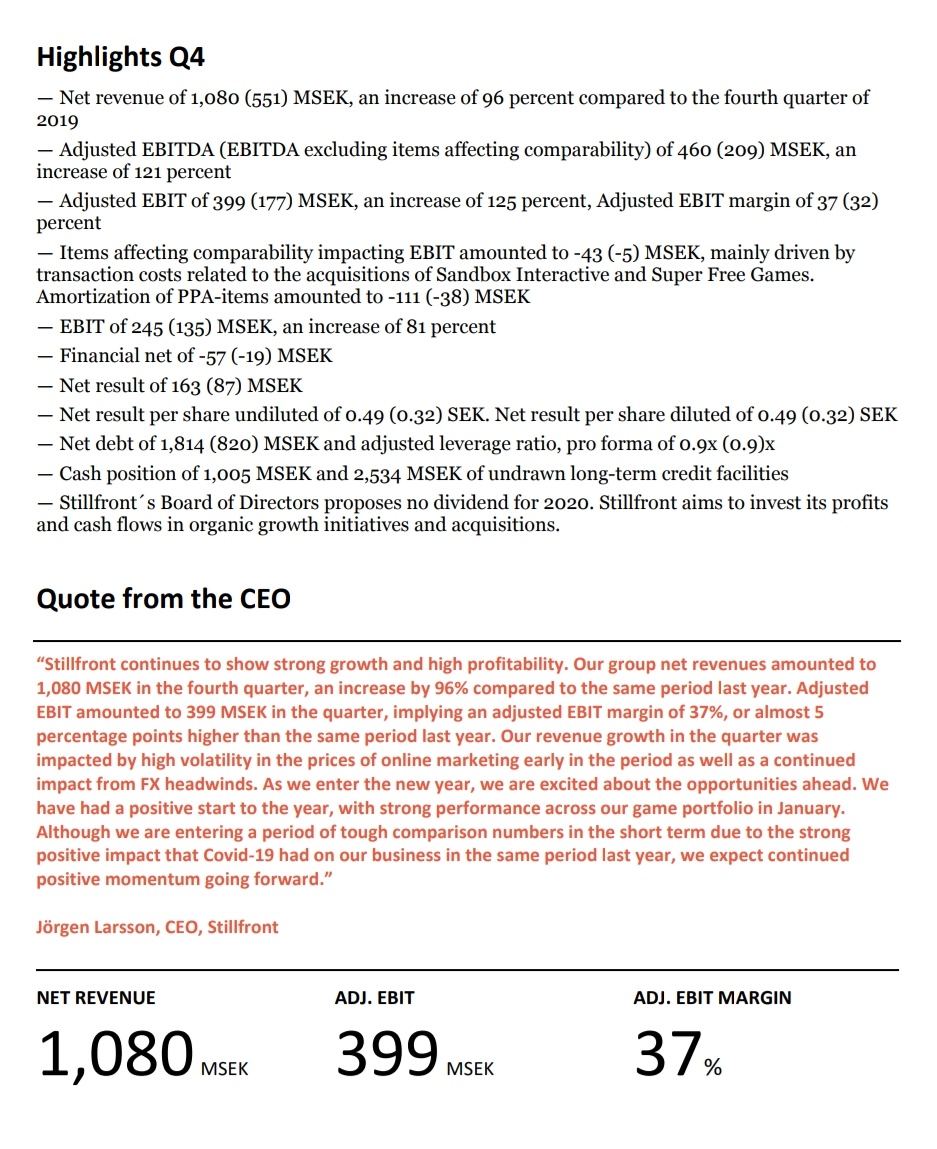
The numbers are strong. It will be interesting to see how the share price reacts, especially after having risen so much from recent lows. What concerns me most here is the guidance and how it will be received.
1 Like
I checked Avanza’s news coverage, and the results, etc., fell short of forecasts:
Daily active unique users were up 215 percent to approximately 4.25 million.
In terms of monthly active unique users, these increased by 274 percent to 21.7 million, with the number of monthly paying users up 278 percent to 877,000.
The average revenue per daily active unique user, ARPDAU, decreased by 38 percent to SEK 2.70.
User acquisition costs amounted to SEK 215 million during the quarter, which is 20 percent in relation to both bookings and net sales.
1 Like
“We have a fair value range of SEK 75-140 and a base case of SEK 113. We maintain a positive stance and will make upward revisions to our estimates and valuation as Redeye feels that the market has yet fully appreciated the value-adding acquisitions of Nanobit, Everguild, Sandbox Interactive, Super Free Games, and Moonfrog, as it is too focused on the short-term. Keep an eye out for a more extensive research update. The future of the Company seems brighter than ever.”
4 Likes
The recent decline in stock price certainly has clear reasons; in addition to the vague guidance, the weakness in organic growth is definitely the biggest reason.
Today’s press release reveals that it is weaker than I personally estimated:
As a result of the inclusion of the new KPI in its financial reporting, Stillfront today reports that the organic growth rate in local currency for the group amounted to 12 percent for the fourth quarter of 2020, compared to the same period previous year, and 16 percent for the full-year 2020, compared to the full-year 2019.
Embracer is on a different level, currently around 20%, despite having ten delayed game projects and approximately 70 games coming in the next fiscal year, which will significantly accelerate organic growth.
1 Like
I’m reducing my position in Stillfront due to the weakening organic growth. The stock still represents a fairly large portion of my portfolio, and I have confidence in the management’s expertise, but performance will be the deciding factor.
1 Like
Andrew N. Green hired by Stillfront to lead Operations & Growth (Senior Vice President of Operations & Growth). The guy has almost 20 years of experience in the gaming industry in various roles, leading teams and accelerating growth, e.g. at Electronic Arts.
Taaleri portfolio manager Niko Fagernäs’ tweet on the subject:

2 Likes
RedEye’s updated report is available, new base case 125SEK
6 Likes


https://twitter.com/FagernasNiko/status/1374379762685112320?s=19
The stock price has been hit hard lately and is currently at RedEye’s bear case levels. It will be interesting to see what kind of results are reported for Q1 and what, for example, the Indian Moonfrog Labs brings with it.
However, Stillfront is predicted to grow and future prospects look good according to analysts, so a P/E of ~20 for next year seems very moderate.
6 Likes
Are there any App Store statistics gurus for mobile games here? I’m trying to understand why, for example, Stillfront has 33 games in the top 1000 “grossing” list, but only 8 in the “free” section (iPhone category). That is, why there are more paying players relative to all players than with an average App Store game.
I came up with one possible story (note! a complete guess):
Stillfront is currently spending less money on user acquisition at the company level, so old players continue to play and pay, but the number of new experimenters is lower → positive for cash flow/profit, but negative for the organic growth of current games.
I used this free page as a source: https://www.gamechartz.com/