A few days ago I came across the ROCR and QualTek USA, LLC combination, for which a DA has been made some time ago. It went unnoticed by me, but at least with a quick browse, it would fit into my long-term portfolio strategy.
Investor Prese:
Qualtek builds infrastructure and provides related services. So, it’s not a hype / high-tech / 0-revenue company, but an established business operating since 2012 with a history of real revenue and cash flow.
- Major operators as clients, 5G construction starting big, solar and wind power installation, etc.
- 2-year backlog of $1.7B, which by itself corresponds to the 2021E revenue forecast of $818M, plus already small growth for 2022.
- Significant infrastructure support coming from the government budget.
- Several acquisitions between 2018-2021.
- EV $828.7M → P/S ~1.01 2021E, so it doesn’t sound very expensive from this angle.
- Large one-off expenses in 2020 significantly affected the result.
- A larger acquisition is planned before the merger, with pre-PIPE financing of $44.4M for it.
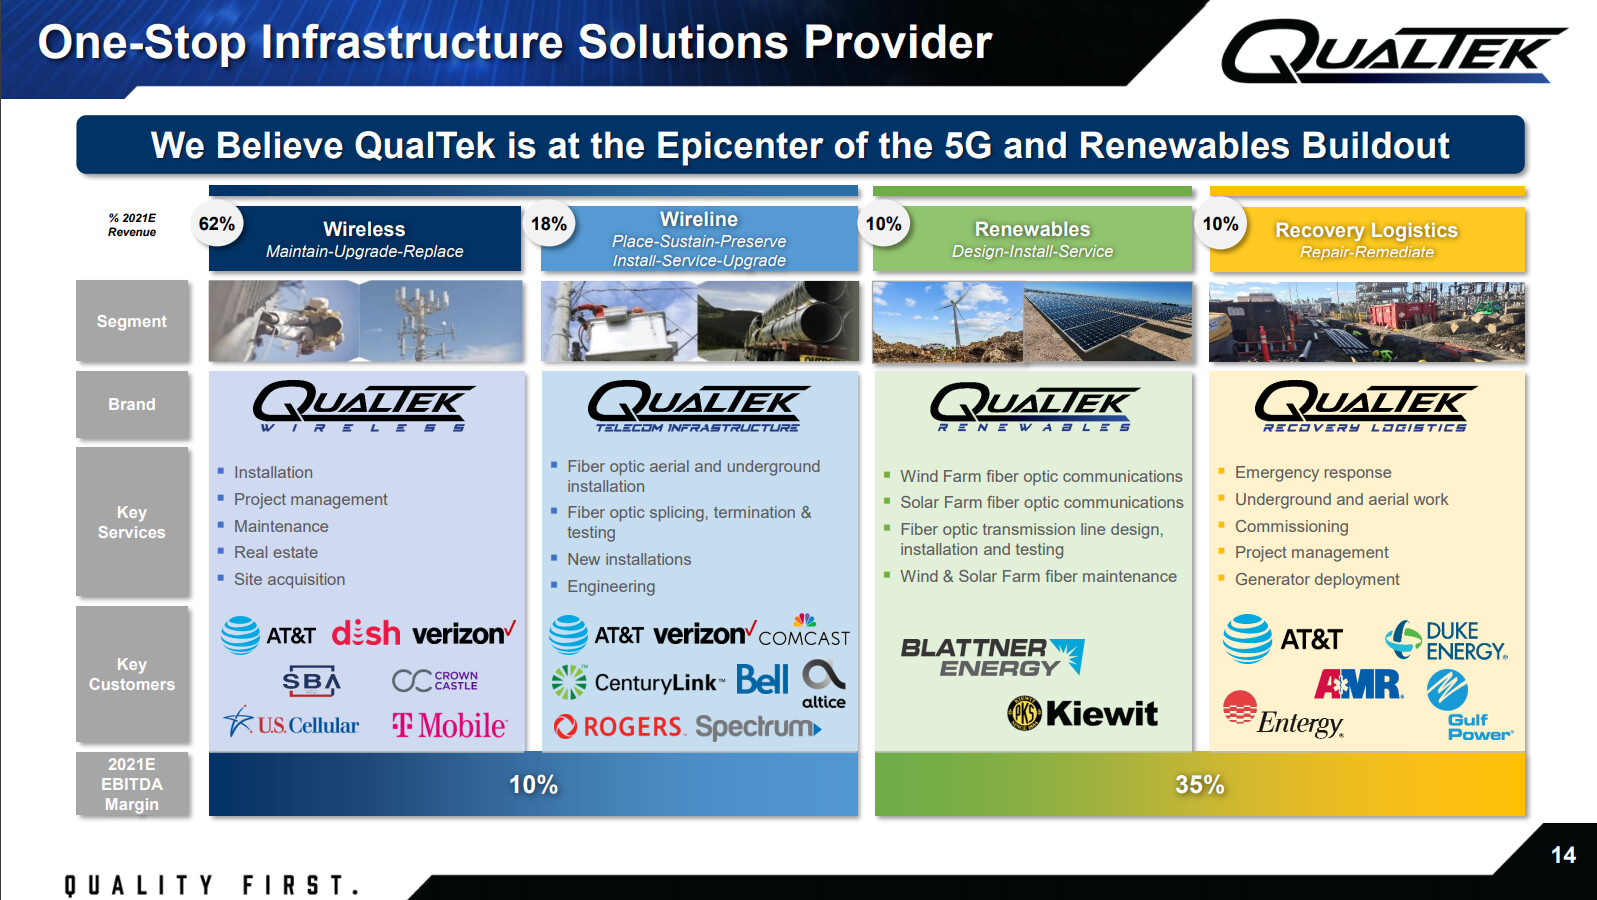
In a nutshell, services:
And to my knowledge, it’s not related to Qualtek Electronics, despite the same name 
I haven’t opened a position yet; I need to free up cash from previous investments first. It has been trading below $10 for a longer time despite the DA, so there should be no rush yet – at least not before the mentioned acquisition. The merger is estimated for Q3, no exact time is known.
One more summary
