I find the overall development of Revenio quite interesting, to be honest. Previously, Revenio was seen as such a reliable cash-flow machine and arguably one of the best companies on the Helsinki Stock Exchange, with a lot of potential. Now, this one acquisition has practically watered down Revenio’s “defensiveness” (for lack of a better word) in the minds of investors, and investors see many (and I mean really many, based on the interpretation of the equity issue) risks in this stock. In practice, it makes me suspicious about whether the current price level is one of the best buying opportunities in a long time, or if Revenio’s reputation will be completely ruined if this acquisition goes sideways. I guess it’s time to evaluate the success of the integration and its risks, right?
Revenio’s earnings have indeed fallen in 2023, 2024, and 2025. Sure, there have been headwinds from the dollar and such, but the “star stock” status has certainly been deservedly buried. The multiples have melted away, and the earned valuation is visible on the stock chart.
In my opinion, in the case of Revenio, one can ask whether even the top management believes in that acquisition since they aren’t buying shares.
I hope the acquisition was a good thing.
Fun to see such high activity in this thread! Feels like an appropriate place to mention that, with Revenio set to release its Q2 report next week, interest among private investors on Pinpoint Estimates is high and continuing to grow.
Investors have already shared their forecasts, expecting stable sales growth but somewhat weaker profitability compared with the same quarter last year.
What do you think — will Revenio deliver in line with expectations, or surprise the market?
Submit your own estimate and compare your forecast with the consensus via the Pinpoint feature on Inderes here: Revenio Group - Investerarkonsensus - Inderes
So stories change.
Nowadays, there is a strong belief in efficient markets, and every single thing is “priced in”.
Benjamin Graham used to talk about Mr. Market, who is sometimes willing to pay a fortune for stock X, and conversely, in the right mood, is willing to sell stock Y ridiculously cheap.
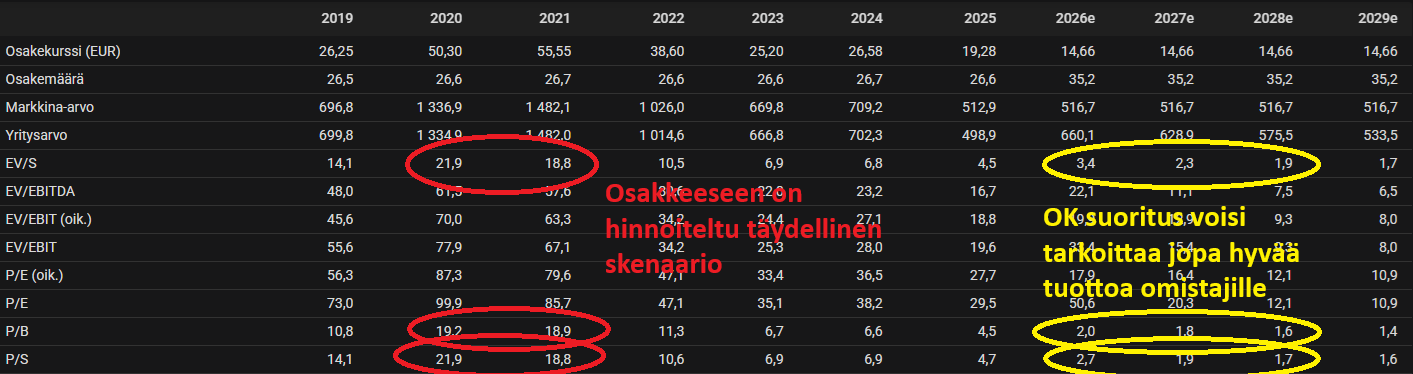
Revenio looks like a very classic example of this: previously, everyone was sure that this stock was going to the moon, and five years later, the axe has been thrown in the well (all hope is lost), and it’s concluded that nothing will come of this.
With Revenio, you don’t even have to exaggerate or predict that much when you can just look at the numbers.
Is this company a screaming buy with a market cap of over 500 MEUR?

Is this a “quality company” for which it’s worth paying very high multiples?
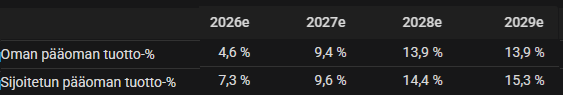
Those following Revenio will probably notice that those are quite extreme examples.
But in the long run, the investment story boils down to this:
A small target price increase from Kauppalehti’s flash news: Danske Bank raises Revenio’s target price to €20.00 from €19.00 and reiterates its buy rating.
I think I am in a situation with this stock for the 1st time where I have to/get to receive subscription rights (merkintäoikeudet) in connection with a rights issue? Tell a novice how this works. So if I own €10,000 worth, how much money do I need approximately if I redeem the shares? How are the subscription rights sold and do they have significant value? And what do the veterans plan to do? It annoys me because Revenio is already heavily overweight, at about 25% of my direct stocks, on the other hand, stocks make up only about 30% [of my total portfolio]. This is a rare stock for me in that right now the timing seems to have worked out and it has performed quite well in a couple of months.
The rights offering aims to raise 80 million from shareholders, and there are currently about 26.7 million shares. Thus, approximately 3 euros of new money is needed per share. With a 10,000 € investment at the current price, you own about 667 shares, meaning you would need to invest around 2,000 € more in the offering.
The directed share issues related to the transaction have already been completed, and they have increased the number of shares to approximately 29.2 million. In that case, it would be about 2.75 euros per share. So, slightly less, but the order of magnitude does not change due to that clarification.
Here is Juha’s preliminary company report ahead of Revenio’s Q2 earnings release on Tuesday, September 8th 
We reiterate our buy recommendation for Revenio with a target price of EUR 20.0. Revenio will release its quarterly report on Tuesday, September 8th, which will also include a one-month contribution from the Visionix acquisition. From the report, we are particularly looking for visibility into the new entity: Visionix’s current earnings performance, the first steps of the integration, measures for the rest of the year, and the schedule for the upcoming rights issue. We consider it particularly essential to clarify the operational earnings performance and outlook in the middle of a major process. Concrete insights into this will likely be provided by new guidance for the combined entity.
What’s going on here, given the large volume in yesterday’s closing auction and the sharp rise today? Has there been some sort of block trade?
At the top of the exchange’s trading volume in the morning was health tech company Revenio, whose share jumped 8.6 percent upon the market’s opening.
DNB Carnegie raised Revenio’s target price late last night from 15 euros to 21.60 euros.
This seems to be going right according to my playbook  , it’s probably also a minor relief for @Juha_Kinnunen that the market is finally starting to believe in Revenio and a buy recommendation with a €20 price target isn’t just shouting into the wind – or how did it feel when the share price was hovering below €12 !? By the way, a “short squeeze” might also be underway.
Looks good for your playbook. Now the company just needs to deliver. If the numbers and outlook align with what I assume, I’m not worried about the thesis.
Having pitched this case to investors quite a bit over the past few months, many have noted that it sounds great, but not yet—let’s wait, and you can always get them in the rights issue (merkikkari). That’s how it goes, of course, but if a large portion of potential investors think that way, at some point the sellers will run out and buyers will be in a hurry. Perhaps that’s what just happened.
Well, let’s watch calmly. Next week we’ll be wiser.
Research on home measurements published in a leading industry journal.
https://pubmed.ncbi.nlm.nih.gov/42610624/
iCare HOME survey for ophthalmologists and patients, involving 157 ophthalmologists, of whom 59% used home measurements. The data obtained in this manner influenced 85% of cases and increased treatment confidence. 72% of patients found home measurements easy to use.
"Conclusions: HT was generally valued by physicians and patients, increasing physician confidence and positively influencing patient well-being. Broader integration remains limited by patient financial barriers and physician skepticism about device reliability and patient proficiency. Further research on outcomes of HT use versus nonuse may help address these limitations."
Bearish analysis and perspective from Sijoitustieto’s Almanac.
The market agreed, noting a drop from 22 to 14€, but a small rebound has been served up ahead of the earnings report and CMD. The ride could get bumpy when the matter is unpacked.
Summary:
We’ve reached the line on the eye chart where you have to start guessing what the next symbols are.
The long-awaited half-year report fell short of analyst expectations: Revenio Group Oyj: Puolivuosikatsaus 1.1.-30.6.2026 | Kauppalehti
April–June 2026
- Net sales were EUR 39.3 (26.5) million, an increase of 48.1%. Visionix is included in the consolidated figures from the beginning of June.
- Adjusted for exchange rate fluctuations, net sales grew by 50.7% in April–June.
- Operating profit was EUR 2.4 (6.1) million, representing 6.1% of net sales, a decrease of 60.9%. Operating profit was impacted by approximately EUR 3.4 million in total non-recurring costs related to the acquisition.
- Adjusted operating profit was EUR 5.8 (6.6) million, representing 14.6% of net sales, a decrease of 12.3%.
- EBITDA was EUR 4.3 (7.2) million, representing 10.9% of net sales, a decrease of 40.9%.
- Cash flow from operating activities was EUR -2.4 (6.7) million.
- Earnings per share were EUR 0.020 (0.116).
- The integration of Visionix has progressed according to plan following the completion of the acquisition. The core of the integration work has been securing business continuity and customer relationships, as well as building a joint organization, operating models, and culture.
- Revenio will host a Capital Markets Day on September 15, 2026, during which Revenio’s updated strategy will be presented.
January–June 2026
- Net sales were EUR 66.6 (52.6) million, an increase of 26.6%.
- Net sales growth adjusted for exchange rate fluctuations was 28.8%.
- Operating profit was EUR 4.8 (12.7) million, representing 7.2% of net sales, a decrease of 62.4%. Operating profit was impacted by approximately EUR 6.9 million in total non-recurring costs related to the acquisition.
- Adjusted operating profit was EUR 11.7 (13.2) million, representing 17.5% of net sales, a decrease of 11.6%.
- EBITDA was EUR 7.8 (15.0) million, representing 11.7% of net sales, a decrease of 48.1%.
- Cash flow from operating activities was EUR -5.8 (11.4) million.
- Earnings per share were EUR 0.112 (0.273).
- The Annual General Meeting was held on May 12, 2026; the General Meeting decided that no dividend will be distributed for the 2025 financial year.
Financial Guidance for 2026
Revenio’s new financial guidance:
Revenio Group’s foreign exchange-adjusted net sales are estimated to be EUR 190–205 million, and EBITA excluding non-recurring items is estimated to remain at a satisfactory level.
The lower end of the guidance assumes that market demand will remain soft and customer activity will stay slower. The upper end of the guidance assumes an improvement in market conditions combined with successful commercial execution.
Revenio’s previous financial guidance:
Revenio withdrew its previous financial guidance for 2026 due to the corporate transaction announced on April 13, 2026.
This really didn’t go very well, as we fell short of all of Inderes’s figures.
(image of Robocomment)
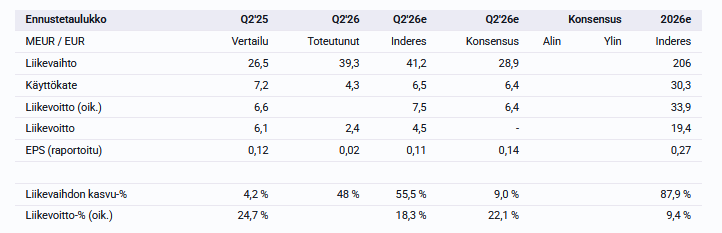
Edit: Let’s also add this one which is missing from the image.
Adjusted operating profit was 5.8 (6.6) million euros, being 14.6% of revenue, a decrease of 12.3%.
Inderes forecasted 7.5M€ and 13.6% growth
Yup, looks like a very ugly earnings miss unless there are explaining factors behind the headline numbers. AI did pick up that one-off costs were 3.4 million euros instead of the 3.0 million euros expected by Inderes. So an explanation isn’t found here to a sufficient degree either.
Revenue missed expectations, and so did profitability (adjusted EBIT-% was 14.6 compared to the expected 18.3) – meaning leakage is happening at both ends now.
It will be interesting to see the share price reaction after a strong July-August. Personally, I expect the lows @ €11.86 to be tested shortly. If it doesn’t hold, the next stop would be marked around €9.80–9.50. 
| Metric (MEUR) | Q2/26 Actual | Q2/26e Inderes | Deviation / Note |
|---|---|---|---|
| Revenue | 39.3 | 41.2 | Missed estimate by -1.9 MEUR (-4.6%). |
| EBITDA | 4.3 | 6.5 | Missed estimate by -2.2 MEUR (-33.8%). |
| Adjusted EBIT | 5.8 | 7.5 | Missed estimate by -1.7 MEUR (-22.7%). |
| Adjusted EBIT-% | 14.6% | 18.3% | Profitability was squeezed clearly more than expected (-3.7 percentage points). |
| EBIT (reported) | 2.4 | 4.5 | Missed estimate by -2.1 MEUR (-46.7%). |
| One-off costs | ~3.4 | ~3.0 | One-off costs materialized slightly higher than expected. |
| EPS (EUR) | 0.02 | 0.08 | Clearly below estimate. |
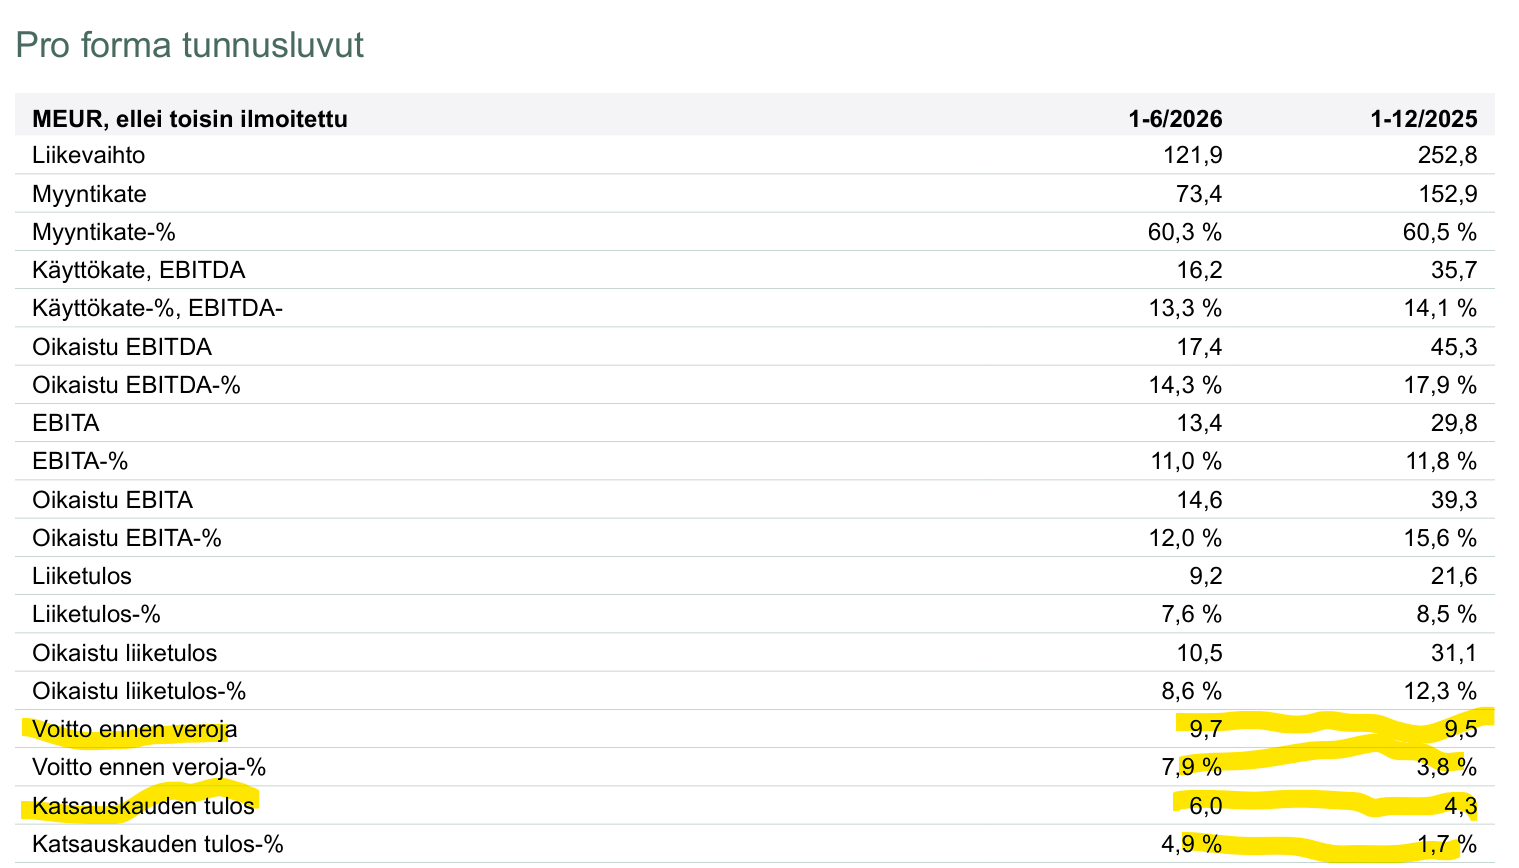
I was left a bit puzzled when the Pro Forma result looked so good.
I got an explanation for it using Claude:
Summary: Operational profitability actually weakened (adjusted EBITA-% 15.6% → 12.0%), but “Profit before taxes” and “Profit for the period” look good in H1/2026 mainly because the pro forma method has piled all one-time M&A costs and a larger portion of Visionix’s heavy legacy financing costs into the comparison period (2025), and not because the actual profitability of early 2026 has improved.