These events have gained exceptional popularity, which means Marianne has received great questions, and the thread has also seen good messages and links during the event.
To ensure everyone has a pleasant experience and the event is as clear as possible to follow, I’d like to highlight a few things:
My uneducated guess: An unsurprising +0.5% rate hike, after which the skittish market will correct upwards somewhat as fears of more dramatic moves fade. What they’ll babble about the future, I can’t say, hopefully boringly predictably the same as before. And popcorn ready.
Oh, what a day of joy it would be if the free market could operate without the control of central banks. I personally guess that there is a long way down if the Fed’s talk about future interest rate hikes remains the same.
And for the past decade or so, we’ve been thinking, oh what a joyful day it would be if central banks would stop messing with the markets and inflating stock prices with their endless money injections.
That’s a relatively common comment, which is why I’m addressing it.
If you scroll through market comments decades back, you can observe a certain repetition: “Fed, too much debt, about to collapse.”
Central banks are a part of the economy, but they don’t control the markets. They do have a lot of influence on the markets, however. They also adapt to market and economic realities. The Fed is currently caught between a rock and a hard place, having to raise interest rates while inflation rages, but at the same time needing to ensure employment and its own credibility.
US government debt interest rates clearly show how rates rebound before the Fed has even properly started with its hikes.
There is no such thing as a “free market” in the sense* that the market operates in a complete vacuum. US markets were truly chaotic before the Fed. Central banks elsewhere are much older.
In my opinion, the Fed gets too much weight: good companies push forward regardless of where the Fed’s actions and rates are.
It’s just a very clear actor with a face, and it’s easy to make memes about it.
*Completely free markets have never been known to exist, and probably never will, and for good reason
This is how interest rate forecasts live. Less than a year ago, it was considered almost certain that the Fed’s policy rate would be close to zero at the end of 2022. Currently, expectations are around 3%, but the change can ultimately be sudden in the other direction as well.
An unfortunate error by a Citi employee caused the Nordic stock exchanges to briefly plummet on Monday. Jukka and Tuomas discuss the causes and consequences of the flash crash, examine potential buying opportunities in tech stocks, and review the Q1 earnings season as it approaches its conclusion. Watch the episode and stay up-to-date on the latest market developments! 0:00 Intro 1:13 Markets Now 16:56 Market Review 27:26 Portfolio Review
It would be interesting to know if central banks truly believed in that transience or merely communicated transience just to lower inflation expectations? The latter would admittedly be quite a gamble for confidence.
I personally don’t believe, nor is there strong evidence, that QE has significantly affected the current underlying inflation. It has certainly boosted asset prices. The reasons for inflation lie in global supply chains, which lockdowns etc. disrupted in an unprecedented way. It’s difficult to find indicators for supply chains, so researching the topic is relatively hard. Perhaps that was one of the reasons why the true nature of the situation wasn’t fully understood.
The price of oil even dropped to negative at one point. Such a second price shock doesn’t immediately come to mind. The consequences of this will surely be investigated. This price shock was one of the first indications for me that we were seeing something completely new in the economy and that traditional models and interpretations should be critically examined.
In the long run, the economy will adapt, and these problems will be fixed, and competitive companies will thrive in any environment.
IMO, a recession is a given because inflation is outpacing wages, and interest rates are rising simultaneously. I’m already noticing that I don’t have as much left over after essential expenses as before, and it’s practically the same for everyone else.
These changes in interest rates and net wages will only start to take effect after at least a few months’ delay. Currently, many people are still making large one-time purchases fearing that prices will rise even further, but this cycle will break at some point. My guess is that the break will happen last in the USA because the strengthening dollar will support local consumers for a while.
The Fed is being watched with interest, but my feeling is that now that we’ve moved into a situation where inflation is a problem and needs to be eradicated, the ball has shifted back to the interest rate markets. If the Fed doesn’t tighten its monetary policy enough, long-term interest rates will rise as market confidence wanes and/or inflation accelerates. If, on the other hand, the Fed tightens more and credibly curbs inflation, then long-term interest rates will fall.
It might be somewhat irrelevant for stocks whether the Fed takes a stricter or more dovish stance. A more dovish stance is bad for stocks when long-term interest rates and inflation expectations rise, while a stricter stance causes ever-increasing recession fears.
I’ll certainly watch the Fed’s press conference for entertainment, but whatever comes out of it, it won’t affect my investment decisions It never should have, if it did…
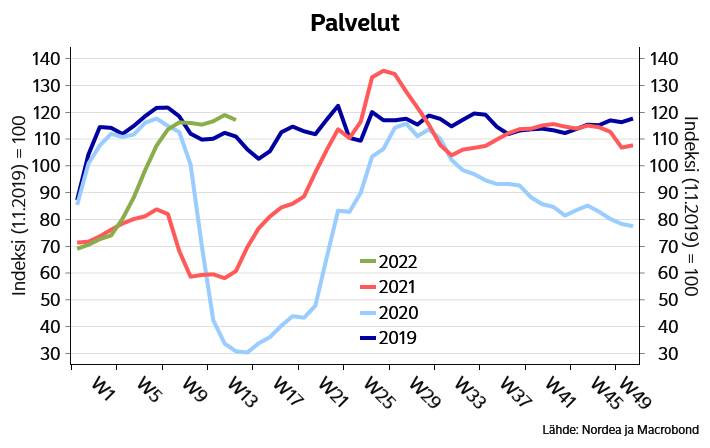
I wonder if this roughly one-week-old Nordea card payment data analysis was still here:
Services are indeed being purchased more now than in 2019, so at least people haven’t started to slow down their consumption yet. This is also supported by my own anecdotal observations from recent weeks; many have really started to move now that the coronavirus restrictions have been lifted and we’ve returned to “normal.” Is an excellent summer ahead for service companies?
No big surprises, so rally gear on because the market was perhaps fearing something worse. We’ll see if JPow manages to talk the prices back down during the press conference. We’ve seen that happen sometimes
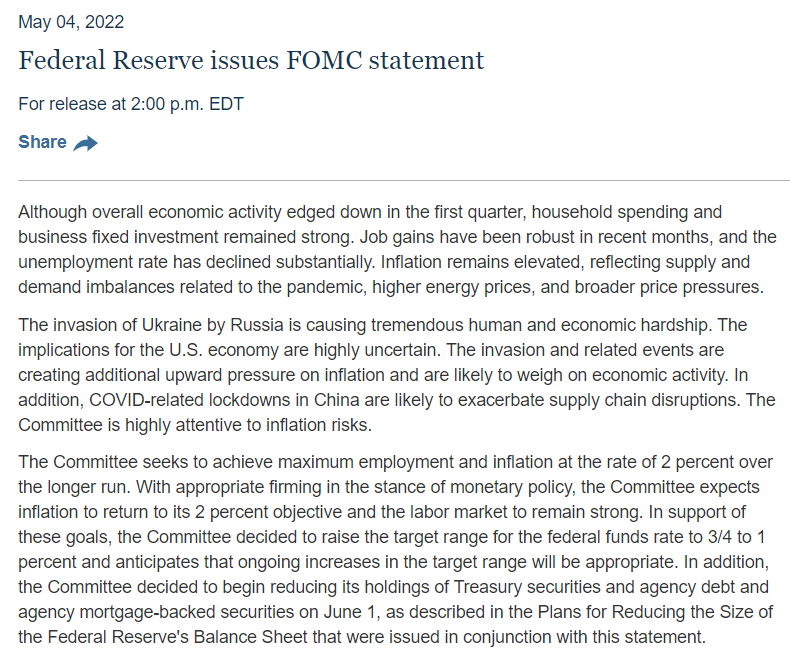
The statement says: “–anticipates that ongoing increases in the target range will be appropriate.” This is largely the same wording as in the previous decision, and we will surely hear in the press conference whether 0.75 percentage point increases are also on the table for next time.
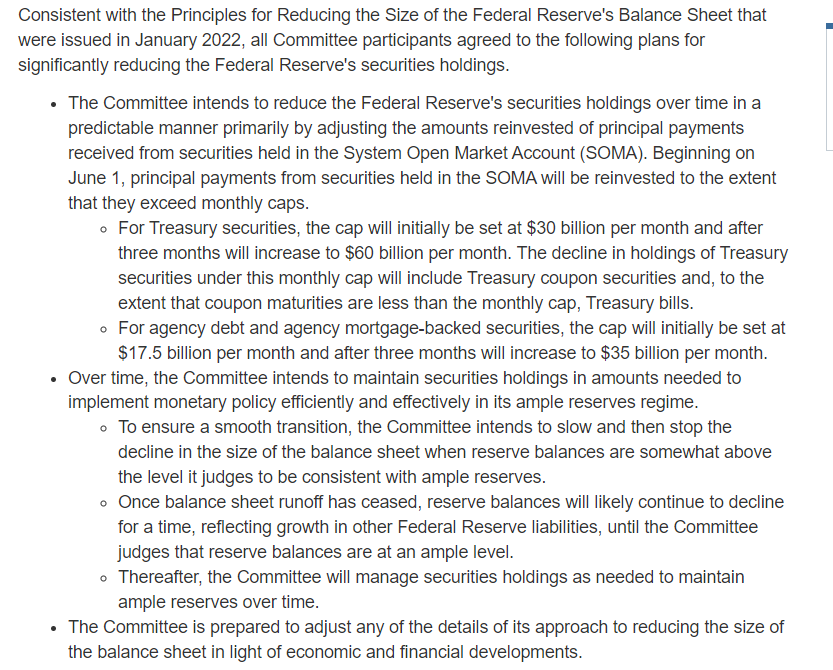
A separate announcement was received regarding the balance sheet reduction measures. It was largely in line with previous Fed statements. That is, starting in early June, the process will proceed gradually, with government bond holdings being reduced by $30 billion initially, and then by $60 billion per month after three months. A similar procedure will be applied to mortgage-backed securities (MBS), starting with $17.5 billion and increasing to $35 billion after 3 months. This was largely in line with expectations.
If the same pace continues into the distant future (reductions of $95 billion per month), it would take almost three years before the balance sheet would be at pre-pandemic levels.
Let’s go back to the beginning of the Fed’s statement. US GDP contracted in Q1, but investments and household consumption remained stable, and the labor market is strong. Inflation, less surprisingly, remained elevated. As new risks, in addition to the war in Ukraine, the central bank mentioned China’s COVID-19 lockdowns, which are disrupting supply chains.