I haven’t followed how taxi fares follow fuel prices. But even if the prices of rides, etc., were not lowered when oil prices fall, it can still compensate for the rise in other costs and curb price increases.
We have had low inflation for almost thirty years, and yet for some reason, there seems to be a general narrative of continuous price increases. Of course, even small price increases are increases, but still.
From that, we can see how inflation dropped after the recession (and some other factors) and has not returned to the same level. I am old enough to remember well (if I remember anything well at all ) the beginning of that curve.
The Goodhart & Pradhan theory about the effect of aging is interesting, but I would still see the world’s production capacity as still being so large relative to demand that it keeps price pressures in check.
And I am still willing to change my mind if necessary. To paraphrase Groucho Marx: These are my principles, and if you don’t like them, well, I have others.
Here’s yesterday’s Talouselämä article, which is not behind a paywall:
“Views expecting clear tightening measures from the ECB are rare. For example, Danske Bank’s chief economist Pasi Kuoppamäki believes that the ECB should not curb aggregate demand, because recovery in the euro area has been slower and tightening labor markets are yet to be seen.”
Here’s the same thing I posted in the Coffee Room, but it might be good to post it here too before The Event starts at 2:45 PM:
You can follow the event in this thread and, if necessary, post relevant information about it.
In the Coffee Room, “lighter writings” might also activate around this event, which might not be suitable here.
So, at 2:45 PM, Marianne will be here commenting on the ECB’s interest rate decision, and she already published her morning article here earlier, which is worth reading before this event.
I think this is an excellent article on European energy policy. I was wondering which thread to post it in, but it fits perfectly here. In short, this is not a situation into which Russia has forcibly driven Europe, but a direction in which we have guided ourselves.
Edit. @Jarnis too much opportunism comes back to haunt you. It comes back to haunt you like spot electricity. And too naive and ambitious ESG policy. Inventories in all energy look very weak, and without major political changes, I personally don’t believe that energy-induced inflation is as short-lived as many hope. Of course, it will surely go down for the summer, unless we go from one extreme weather to another and unless there is war, but inventories will be emptier again in the fall with this trend, and we will possibly start the next cold cycle from a worse situation.
But yeah, really good journalism in my eyes, so it’s worth reading, even if it’s a bit of a longer article.
More specifically, we drove ourselves into a corner where the only support and security is Putin and gas from the pipeline. Then we complain when Putin leverages the intentionally given advantage as a bargaining chip. One can only wonder if this was done on purpose or what the hell is going on?
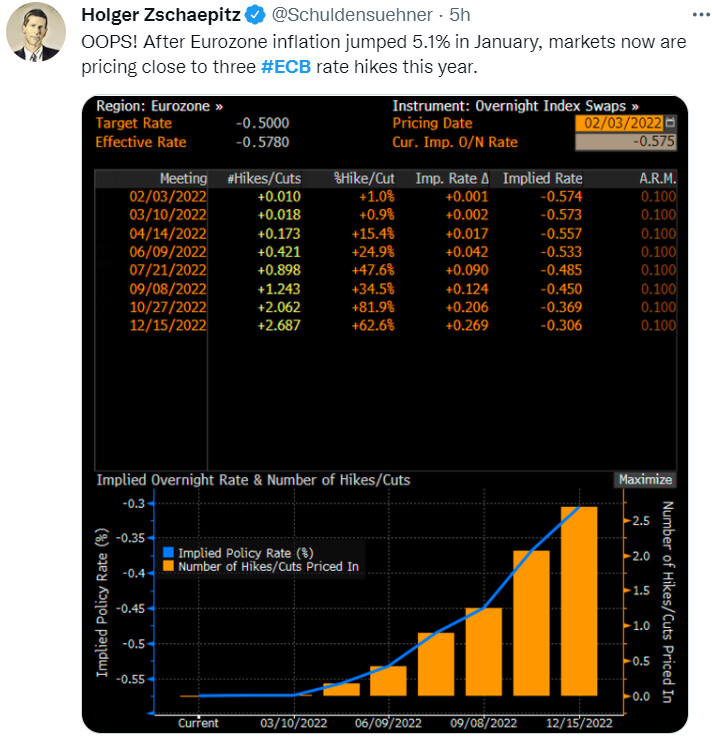
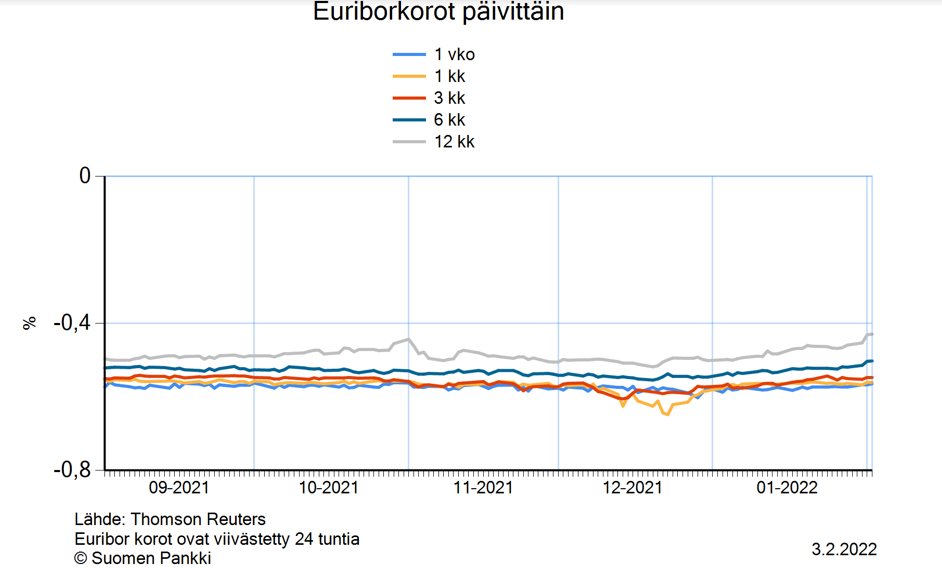
A very good Thursday afternoon to all! The ECB’s interest rate decision will be published soon, and before that, a couple of figures to spice up the monitoring. There has been talk of rising interest rate expectations in the euro area already for this year, but homeowners should not be alarmed yet. The discussion has been about increases in the deposit rate (currently -0.5%), and even then, it’s about three 0.1 percentage point increases, as can be seen from the tweet below, if I interpret it correctly. The deposit rate is likely to be used as a tool in monetary policy before touching the key interest rate. Interest rate expectations have not yet moved euribor rates much either, as can be seen from the Bank of Finland’s statistics. Nevertheless, I remind you that the bottom in these rates has been seen and the direction is upwards, albeit slowly.
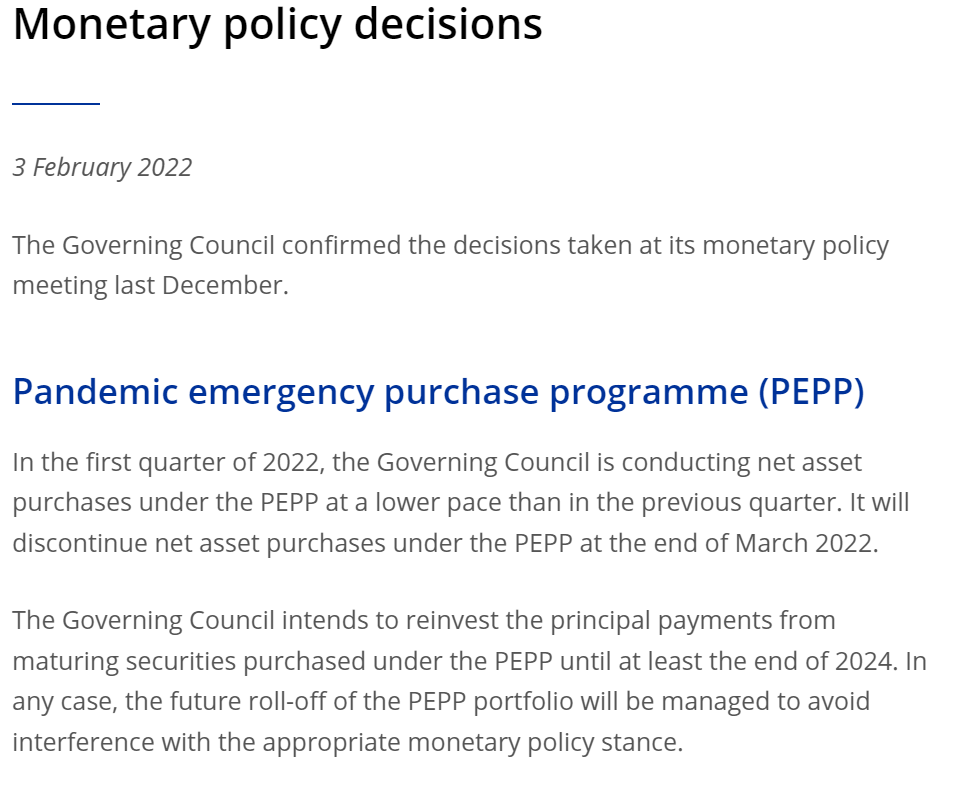
This decision didn’t have as much “speed and dangerous situations” as the Federal Reserve’s interest rate decision last week. At the press conference starting at 3:30, President Lagarde’s views on inflation persistence, wage development, and of course, all kinds of hints about interest rate policy, mainly whether she will stick to her words that no rate hikes (not even deposit rates) will be seen this year, will be of interest.
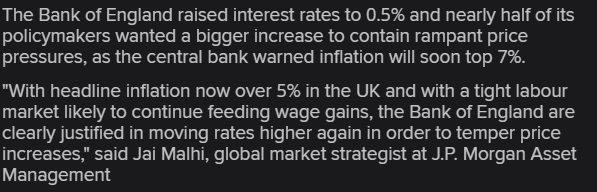
The situation on Europe’s western edge is quite different from Frankfurt, as the Bank of England raised its policy rate again earlier today, now to 0.5%. Almost half of the policymakers would have preferred a larger hike. Here’s a snippet from Reuters:
EDIT. Here are the differences in interest rate policies, even though inflation figures in the Eurozone and Great Britain are almost the same, around 5%.
Now I’m going into an area I probably shouldn’t meddle with, but I’m mainly wondering if England’s current unemployment rate and Brexit could have some impact on a different view of inflation’s persistence? Within the EU, production can still be directed to cheaper countries within the union over some period of time, or labor can be obtained from these countries. England, after Brexit, seems to have partly stumbled over its own cleverness regarding labor.
That’s an interesting idea that probably needs to be investigated. There have likely already been research papers published on the effects of Brexit on economic price pressures.
Then to the press conference. Inflation is expected to remain high in the short term. According to Lagarde, prices have risen in several commodity groups, but the persistence of inflation is uncertain. Wage growth has been moderate.
According to Lagarde, economic growth risks are balanced, but inflation risks have increased. This means that an inflation forecast hike is likely again in March.
Lagarde was asked if her view that there would be no interest rate hikes this year was still valid. She did not commit to this now, but merely stated that the ECB’s decisions depend on future data and that they would be wiser after reviewing the coming weeks.
Lagarde’s speeches often refer to March, when the central bank will have new forecasts to support its decisions, and when, for example, the interest rate outlook can be assessed. Based on this, it’s not surprising that interest rate decisions are often linked to these forecast publications. On the other hand, it seems that the central bank’s forecasts are still aging rapidly (in a few months), which also diminishes their informational value.
@Marianne_Palmu What do you think would be the interest rate level that a highly indebted EU could still withstand? Or that the most indebted countries could withstand without collapsing? I haven’t really seen any speculation about this anywhere yet.
When talking about these, it’s good to remember that states do not borrow at variable rates. Interest rate changes are therefore reflected in debt servicing costs with a delay, depending on the maturity of the loans. For example, the maturity of Italian loans is just under 7 years.
 ) the beginning of that curve.