Pharming Group - A rare opportunity with rare drugs

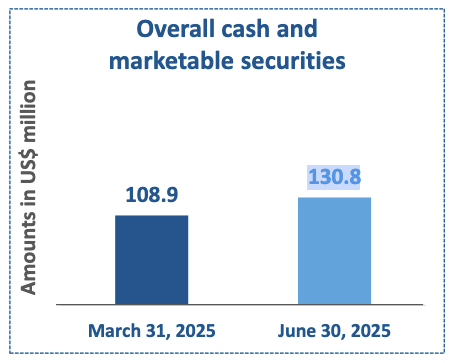
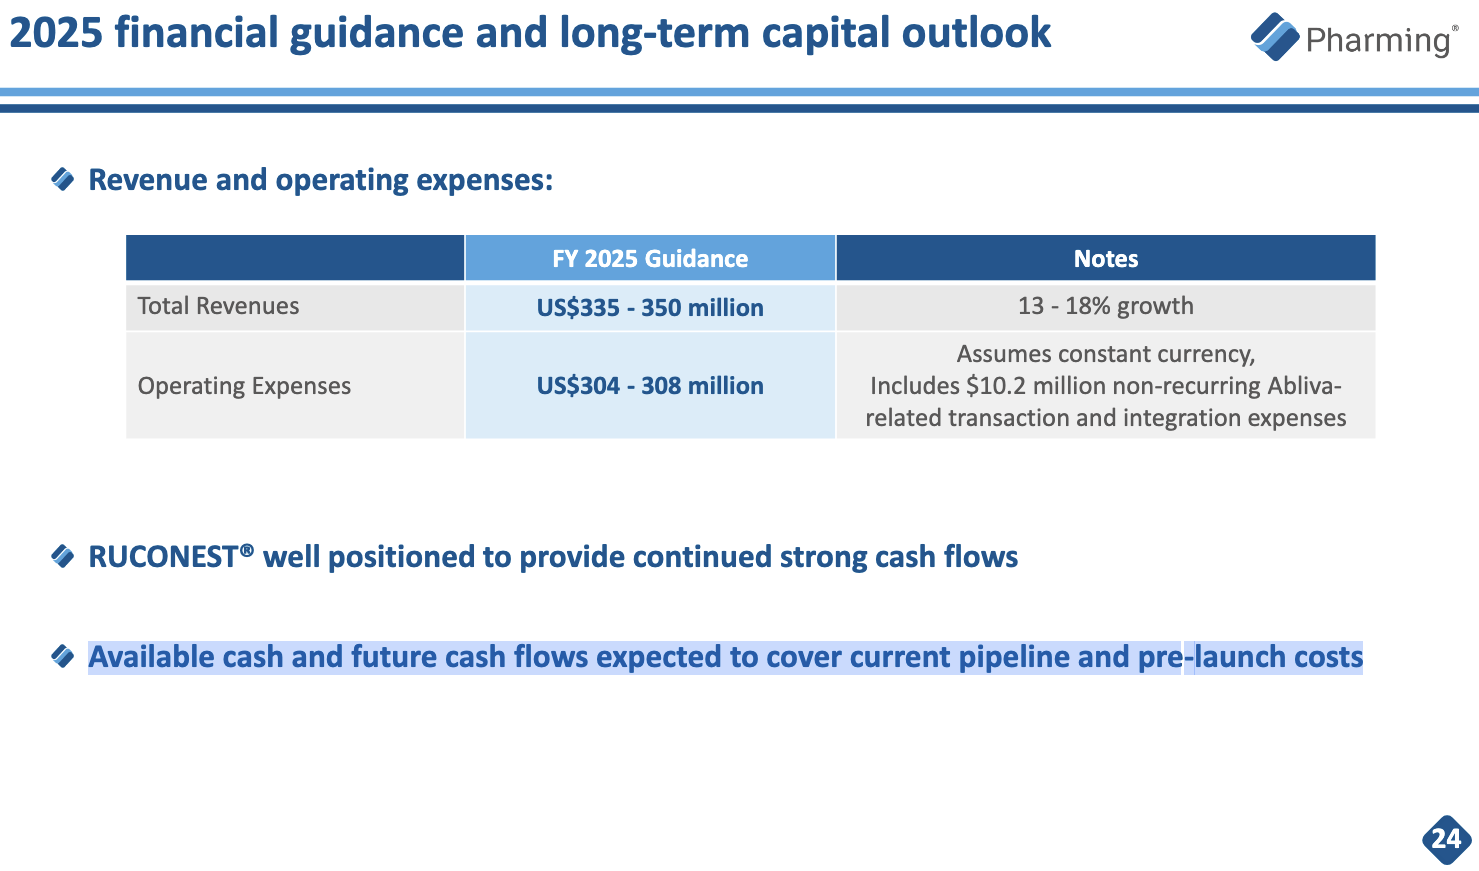
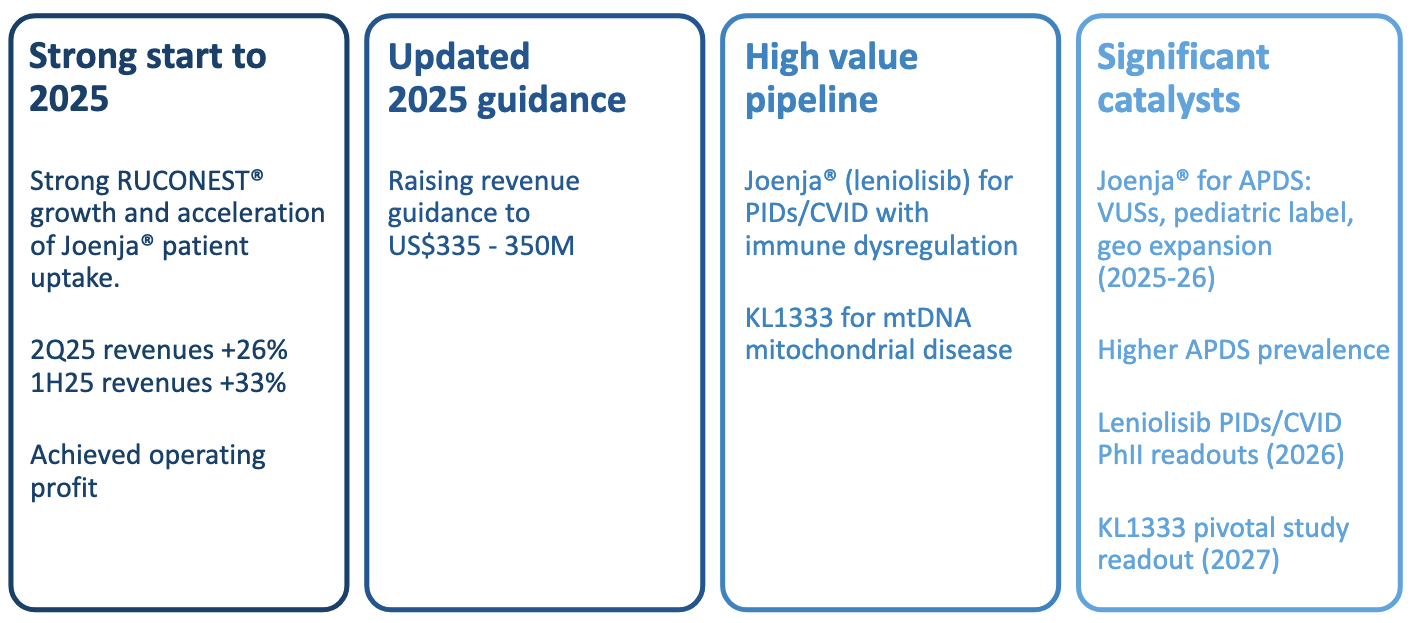
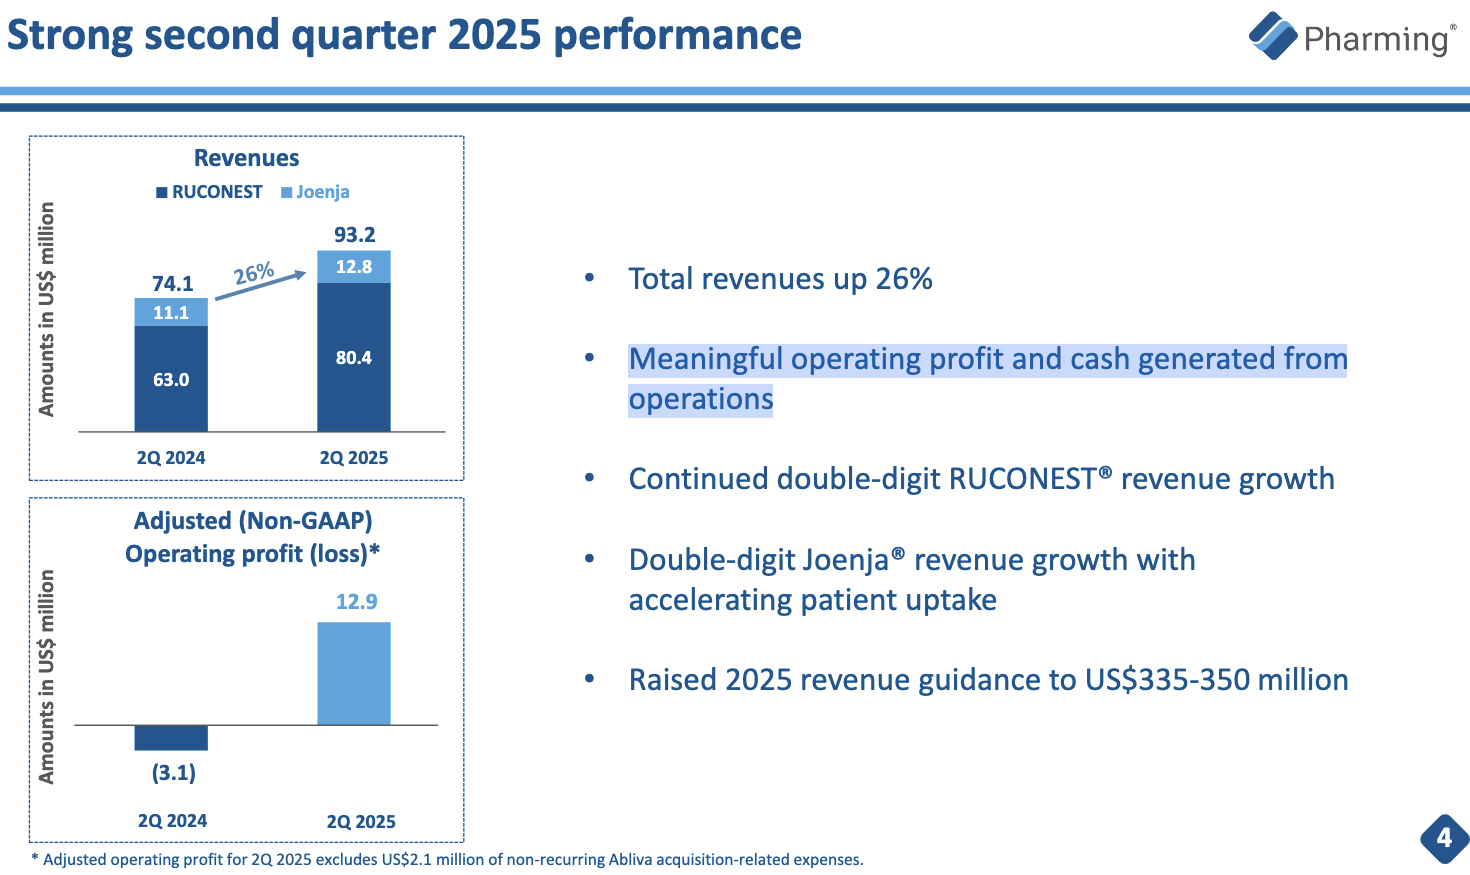
Pharming Group is a small Dutch pharmaceutical company that focuses its drug development on medications for extremely rare diseases. Unlike a typical development company, Pharming not only has future promises but also genuine pharmaceutical products for sale, which bring it significant growth-oriented revenue and cash flow. Following a positive profit warning issued this year, revenue is expected to reach hundreds of millions of dollars, and at the end of June, the company held a substantial war chest of cash reserves and equivalent assets totaling 131 MUSD. Current cash reserves and cash flow from sales are guided to be sufficient to fund the development of future products, so investors do not need to be begged for money, and in fact, the company is now rather looking for promising acquisition targets in the market.
The company has three main pharmaceutical products for sale and/or under research, which I will go through in more detail below, one by one.
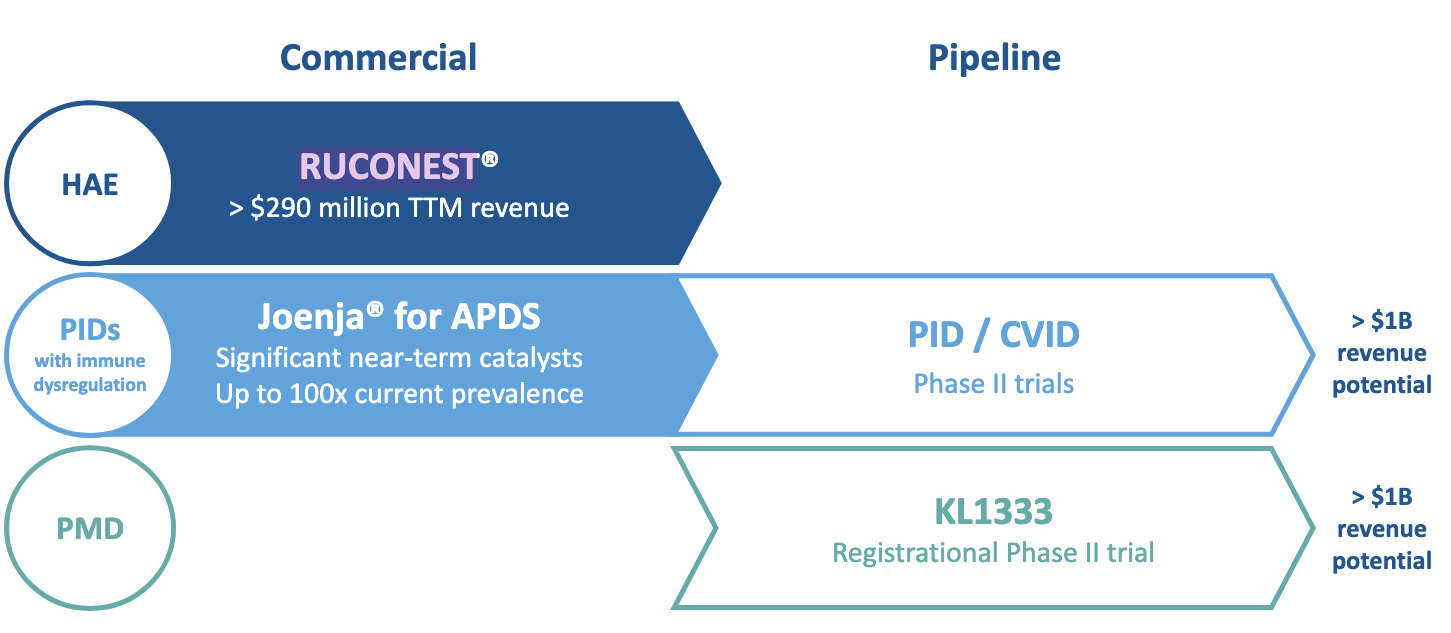
Ruconest

Ruconest is a preparation made from the milk of transgenic rabbits, used to treat acute severe hereditary angioedema, which is a type of swelling of the skin and mucous membranes caused by an allergic reaction. This expensive medicine is applied only in the most severe cases and must be used to treat attacks lasting several days, so each individual new customer generates tens of thousands to hundreds of thousands in revenue for the company annually.

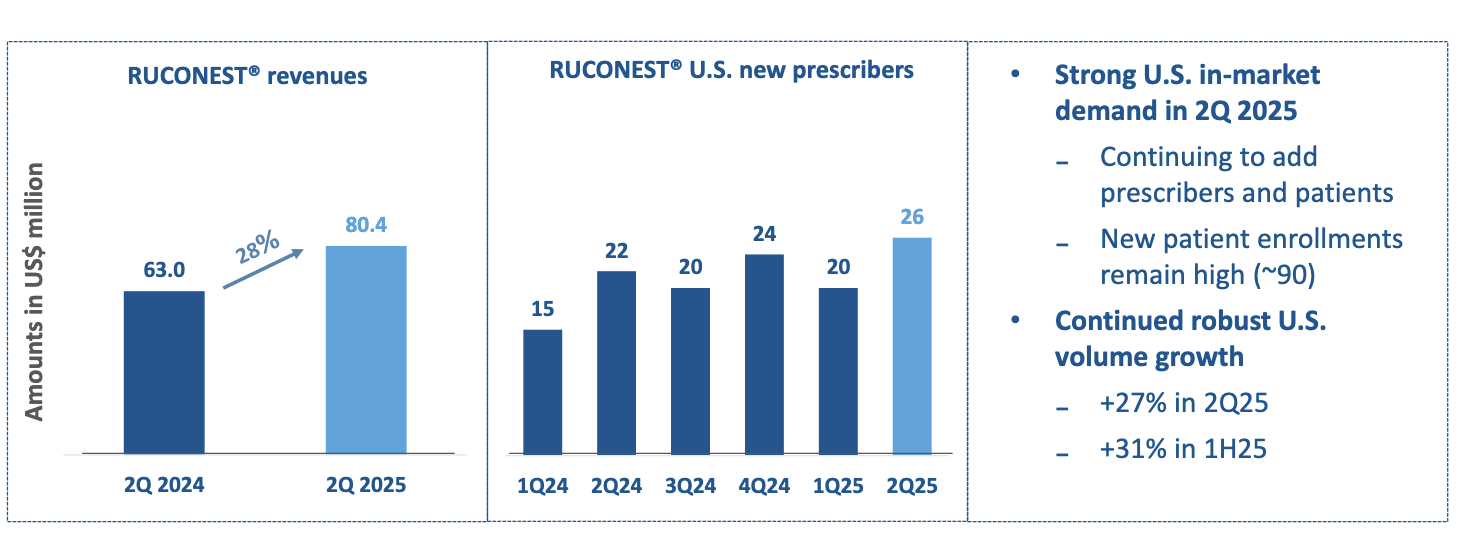
Although the number of new users increases at a slow pace of only about twenty per quarter, Ruconest has generated nearly 300 MUSD in revenue for the company over the past 12 months. However, the American FDA has recently approved competing drugs for the market (for example, KalVistan’s Ekterlyn), so there are some question marks regarding the product’s stability. For now, sales and revenue are still growing, and it always takes time for competitors to make a breakthrough, so the cow can still be milked well in the near future.
Joenja

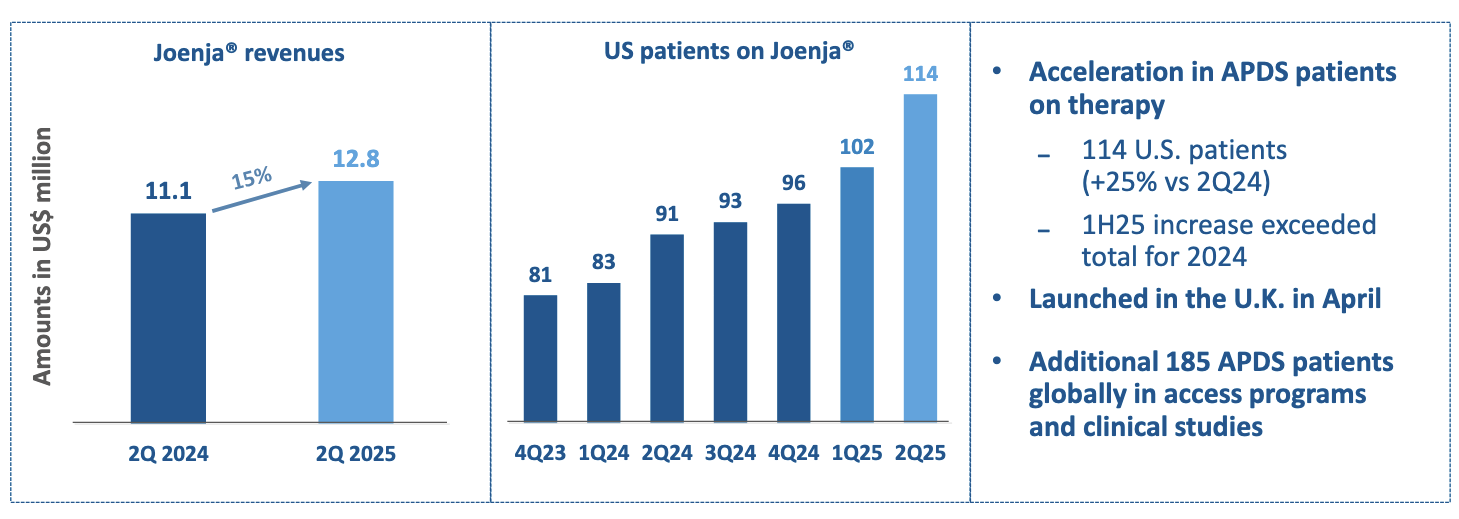
Joenja treats a rare primary immunodeficiency condition called APDS (Activated PI3K delta syndrome). Primary immunodeficiency is a condition where the body’s immune system is genetically unable to defend against infections. Joenja inhibits PI3Kδ hyperactivity and thereby improves the patient’s immune system function. There are currently over one hundred patients using the drug in America, out of a total of five hundred potential patients. The numbers may sound small, but each of them is invaluable and generates approximately 400 kUSD in revenue per year for the company.

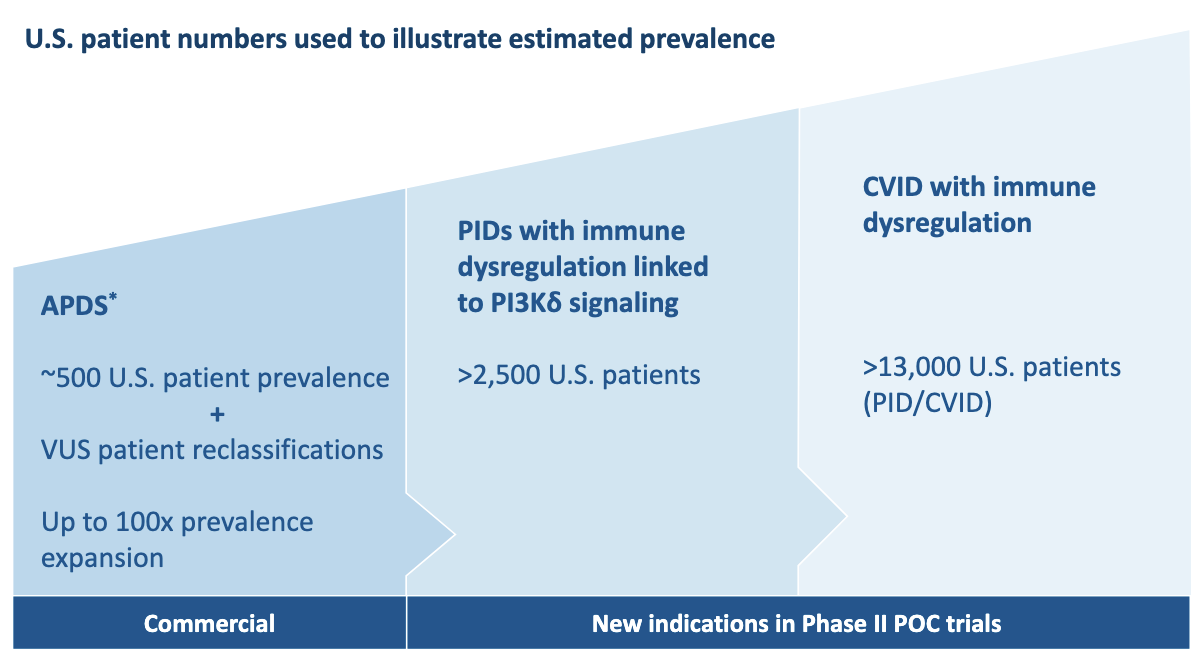
However, Joenja still has additional potential to develop into a genuine blockbuster drug, because there are so-called VUS patients (Variant of Uncertain Significance) worldwide, who, according to new studies, may turn out to be APDS-related, and thanks to whom the prevalence of APDS may be significantly greater than previously thought. With the latest research, the company expects the redefinition of VUS patients as APDS sufferers, and thus Joenja users, to start showing in revenue growth already by the end of the year.

Geographical expansions into Europe are also underway, as well as additional research into the drug’s use for 4-11 year olds, which, if successful, will significantly expand the valuable drug’s customer base. In addition, as a wild card, research is being conducted into whether Joenja could also treat other immunodeficiency conditions. It is not yet known how big a hit this will be, but clear possibilities for a billion-dollar drug exist, and if everything goes well, we are talking about sales of several billions. However, information about possible success does not have to be waited for long, as a significant flow of announcements regarding these possibilities is expected already this year and next.
KL1333

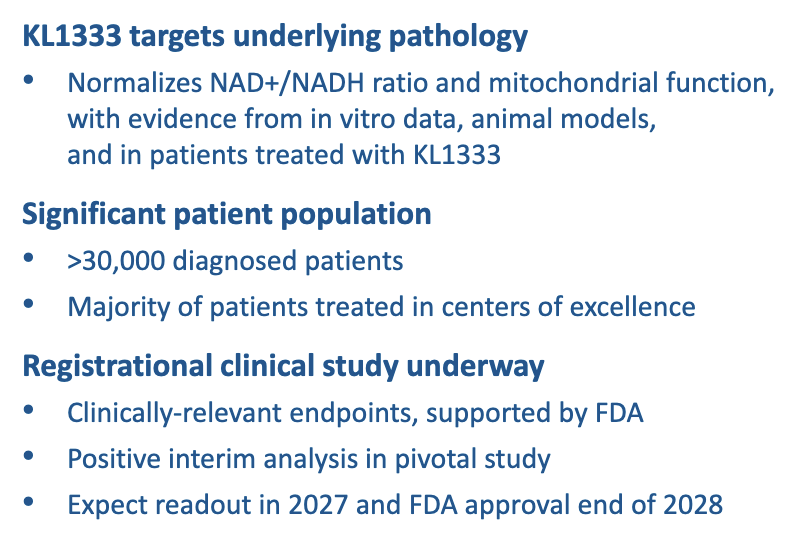
In 2024, Pharming announced that it would acquire Swedish Abliva AB for 66.1 MUSD to gain control of a very promising drug candidate for primary mitochondrial dysfunction. This is a genetic defect inherited from parents, due to which cells do not receive enough high-energy compounds, which can cause, among other things, muscle weakness and heart failure. Over 30,000 people worldwide have been diagnosed, so there is demand for the drug, and if successful, this will become another billion-dollar drug in Pharming’s portfolio in the coming years.
At the time of writing, there are only 21 owners on Nordnet, so there is still plenty of time to get on board, and with a continuous stream of news and profitable, upward-trending revenue, it’s easy to smile as a Pharming owner.
The opening post was originally written for the forum’s pitching competition:

30 Likes

The number of owners increased by only six after the pitch, so my message apparently didn’t cause any rush of forum investors into the stock.

A few days ago, First Berlin analyst Simon Scholes issued a rather hefty target price for the stock, which is based practically solely on the sales potential of current products and doesn’t even take into account the KL1333 option, which, if successful, could bring billions more in sales.

Rating: BUY
Target Price: €2.40 (previously €2.30)
Return Potential: 129%
Risk: High

For this reason, I would be interested to hear the opinion of the forum’s most active pharmaceutical discussants @Clark_kent and @Vino_Pino, as well as forum doctors @JNivala and @Johannes_Sippola, on the company, if you have the time and interest to get to know the company. Is there a catch here that I or the analyst haven’t noticed?

13 Likes

How would you answer yourself to those theses of yours with the Pharming idea? So that one would see the raisins from the bun, in the name of truth, the whole message too.

Full message: Faron Pharmaceuticals - Innovatiivisia lääketieteen ratkaisuja (Osa 1) - #7847 käyttäjältä Pohjolan_Eka

Message: Faron Pharmaceuticals - Innovatiivisia lääketieteen ratkaisuja (Osa 1) - #7838 käyttäjältä Pohjolan_Eka

Message: https://forum.inderes.com/t/faron-pharmaceuticals-innovatiivisia-laaketieteen-ratkaisuja/2655/7838?u=vino_pino

Message: https://forum.inderes.com/t/faron-pharmaceuticals-innovatiivisia-laaketieteen-ratkaisuja/2655/7829?u=vino_pino

By the way, the teachings of the gateway theory have been questioned; correlation is not causation.

Is the dog you are looking for described in your messages? “Billions in drugs soon - a rare opportunity” and hardly anyone buys the stock. I’m not dismissing the investment target, as I’m not deeply familiar with it; I just got stuck on those dog hairs.

12 Likes

Oho, if previous messages in the Faron thread have left such a bad taste, we can certainly continue the discussion on the topic in a private message :smiley:

Generally, junior drug development companies (like Faron, which you mentioned) should be viewed critically precisely because developing a completely new drug is extremely expensive and, on average, value-destroying for shareholders. However, the difference between Pharming as an investment target compared to, for example, Faron, is clear to me already from the second sentence of the opening message:

Unlike a typical development company, Pharming, in addition to future promises, has genuine pharmaceutical products for sale, which bring it significant growth-oriented revenue and cash flow.

So, for these cash-flow-generating drugs, the enormous binary risks in phase completion and company bankruptcy have already been overcome, and fundamentally, the company no longer needs to seek external financing. Instead, the continued development of current and new products can be financed entirely with its own resources, and negotiations with other players can be conducted from a very strong position. As I understand it, the question now is more about how much the customer base and sales of the products can be expanded, which is clearly less risky than developing a new drug from scratch to sales.

kuva
kuva
kuva

19 Likes

Oh, right. There’s no need for a private breakdown; let’s go through it openly and fairly and try to learn from ourselves and each other at the same time.

If we start comparing to Faron, it’s certainly not developing a drug from scratch at the moment. Phase 3 has been planned with the FDA. We’re just waiting for a payer :smiley:. At the time of those messages I confronted, Phase 2 was underway.

True, Pharming has an approved product, but how much of the nearly billion USD market cap is justified by hoped-for additional indications or entirely new ventures for which there is no evidence yet? Thus, your messages fit Pharming. Existing revenue sounds safe, but net profit is probably at a loss, and costs won’t decrease if the pipeline is expanded. It might go very well, but as for how well to justify the value, I’ll leave the speculating to others.

HAE is a competitive area. Thus, uncertain revenue from that indication. I wonder what a rabbit milking machine looks like. Apparently, this drug substance doesn’t work in a fermenter but requires a mammal’s mammary gland?

4 Likes

Kl1333’s mechanism of action via NQ01 is already de-risked to some

9 Likes

Absolutely all constructive criticism is welcome, and I’m interested to hear if the forum’s seasoned members find any fundamental weakness in this that would explain the current low market value.

In my opinion, it’s fair to describe that developing a new drug in Phase III without secured funding is a completely different level of risk-taking, because failure in funding or in Phase III easily causes a -90% loss for the investor, and even with success, it can be a surprisingly long journey before the drug generates revenue and cash flow.

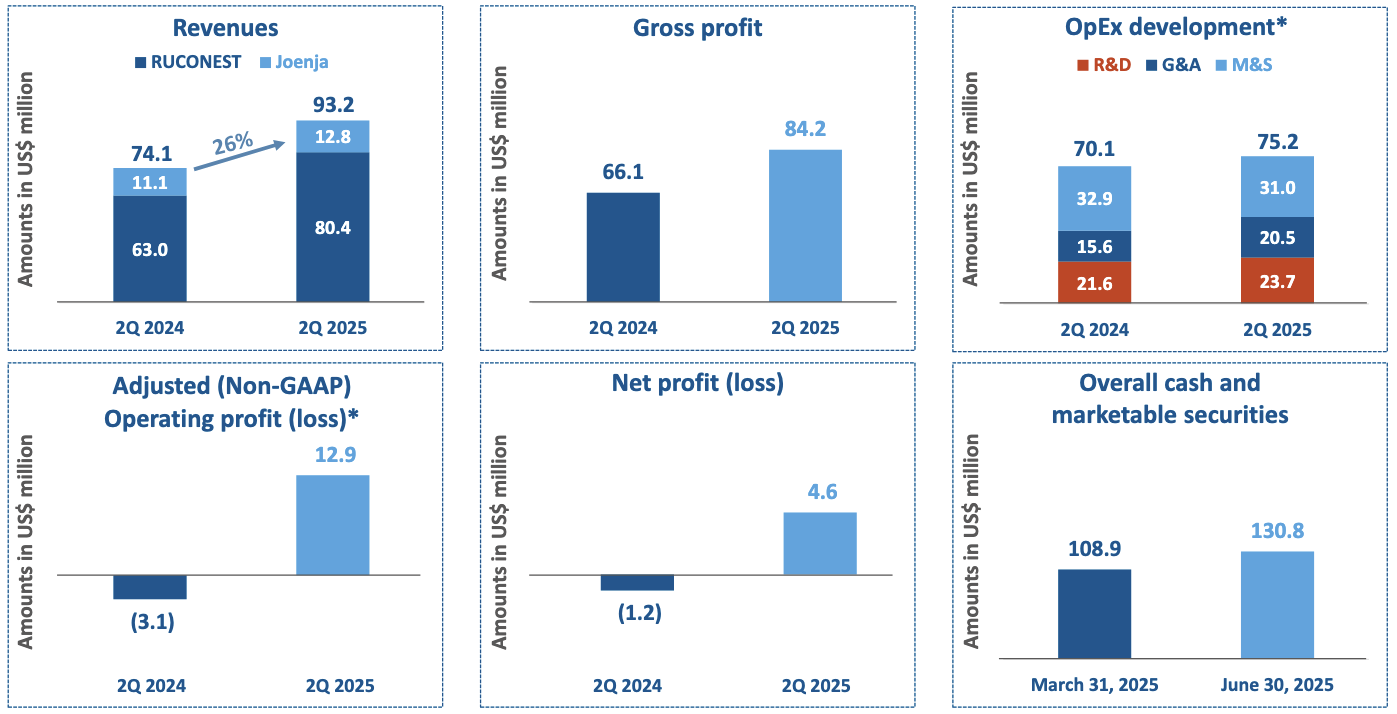
HAE is extremely competitive, but competing products have proven insufficient, at least for now. As I understand it, this is the most potent stuff available on the market, and customers first try competing drugs, and when those don’t work, they ultimately turn to Ruconest. Once a customer is acquired and efficacy is demonstrated, there’s a huge barrier to switching away from the drug. In my opinion, the revenue development has demonstrated Ruconest’s permanence and competitive advantages, and although it’s clear that the money machine won’t grind indefinitely, so far, customer demand and revenue growth have been more than reasonable, in my opinion:

Ruconest Revenue:
2021 198.9 MUSD
2022 205.6 MUSD
2023 227.1 MUSD
2024 252.2 MUSD
1Q25 Ruconest grew +49 %
2Q25 Ruconest grew +28 %

The gross margin for the drug is around 90 %, so revenue growth scales exceptionally nicely into cash flow.

Regarding Joenja (leniolisib), the only APDS drug on the market, geographical expansion (Japan, EU and Canada) and indication expansion to 4 - 11 year olds are being undertaken, which are in all respects significantly lower-risk projects, because they target a drug already approved for the market and proven effective through studies.

This summer, a news bombshell also dropped, to which the markets, in my opinion, have not reacted at all.
Walsh Z.H. et al published the study Scalable generation and functional classification of genetic variants in inborn errors of immunity to accelerate clinical diagnosis and treatment

https://www.cell.com/cell/abstract/S0092-8674(25)00624-5

This study states that VUS patients can be redefined as APDS patients, i.e., Joenja users, by reinterpreting existing laboratory data. This study alone multiplies Joenja’s current customer potential, without any new approval applications, and Pharming predicts it will start to be reflected in revenue already by the end of this year. New similar studies are reportedly in the pipeline, so Joenja’s customer numbers could still grow dramatically from the current level without having to go through that extremely heavy approval process.

In this news article, the same information has been summarized into an easier-to-understand format:

My bolding:

Only a few hundred Americans are thought to have APDS, but based on a search of hundreds of thousands of genomes, the new study suggests that APDS could be magnitudes of order more common than previously estimated, possibly affecting one in every 10,000 Americans.

Since Joenja (leniolisib) is the only APDS drug available on the market and each new American patient brings in approximately 400,000 USD in revenue per year, I believe the significance of this finding should not be underestimated. One in ten thousand Americans is 34,200 people, and even if that proves to be an exaggeration, the difference from the current maximum of about 500 American patients is an incredible improvement in sales potential for such an expensive drug, not to mention the increased global sales potential.

On top of all this, there are also the additional studies for Joenja in Phase II and KL1333, which, in my opinion, act as a free, but, if successful, extremely lucrative option for the investor.

The company is already deeply profitable, but this is not reflected in the results, as the money is currently being used for product investments, which is why earnings will be around zero or slightly negative for a couple of years.

With the analyst’s projected low double-digit growth, we reach 2029e
Revenue 580.3
Gross Profit 525.8
Gross Margin % 90.6 %
Research & Development –140.0
Sales & Administration –289.5
EBIT 96.3
EBIT Margin % 16.6 %
Net Income 82.1
EPS (USD) 0.10

If you apply even a normal valuation multiple of four to that revenue, then 872 MUSD MCAP —> 2321 MUSD MCAP just based on the income statement. Of course, if KL1333 also succeeds on top of that, we’ll be in completely different spheres. Isn’t this clearly an exceptional company in the junior field of drug development, when usually you have to gamble heavily on some late-stage development company or a one-drug wonder and take enormous binary risk through that.

For me, such one-card wonders never succeed, at least, as I wasn’t born under a lucky star :frowning:

14 Likes

Is it realistic to keep the price nearly that high if the market were to expand in that way? Payers (from public funds or insurance companies) might resist.

1 Like

Buffetti said something like, If you don’t understand the business, you don’t know what it’s worth.
The idea of selling sauna heaters, and even better, selling used cars, can be understood. And hey, these can even be scaled to Sweden, Germany, etc.

Then, when it comes to understanding the company’s fundamentals in the case of Faron or Pharming, understanding cancer immunology (Faron actually also does science, not just applies it) or understanding the mechanisms of rare diseases, while also understanding their significance for the individual and for society, which often bears the costs, and whether money can be made from them, sets a limit.

A Pharming investor cannot be convinced by ”Scalable generation and functional classification of genetic variants in inborn errors of immunity to accelerate clinical diagnosis and treatment” or ”The Kl1333 mechanism of action via NQ01 is already de-risked to some extent because idebenone, which acts via the same pathway, has approval for the mitochondrial disease LHON. Kl1333 studies are high-quality placebo-controlled already from phase 1”.

You described it like this

If an investor feels they become a passenger due to a difficult-to-understand topic, it likely causes a little paranoia. Or the investment is called gambling. In that case, perhaps one invests because someone else invests, or invests in the stock, not the company. Or to gamble. Perhaps that’s why an investor rush hasn’t happened yet?

Simply put, with Pharming, it’s about administering a protein, e.g., an enzyme, missing due to a genetic cause. One needs to understand what the disease is and its mechanisms, how patients are found, how the genetic defect is diagnosed, how the protein is introduced into the body, how it is produced and at what cost, what people are willing to pay for the treatment, how long it will be monetized, and who the competitors are.

Will gene therapy eventually take over the market if expensive “replacement therapy” becomes cumulatively more expensive (medicine, its administration costs)? The protein is faulty, so its coder in humans is repaired. Pharming has already transferred the gene to a rabbit and it is being milked.

Gene therapy sounds simple, is complex, but will likely become more common and cheaper. For example, Roctavian for hemophilia. It still costs millions now.

Pharming certainly has years to monetize its replacement therapies before a permanent decline due to gene therapies. Here, I wasn’t even thinking about inherited changes yet, but rather individual treatments. How many years should one estimate for that to be the case for an investment to be justified? @jerej is probably most on top of gene therapy.

3 Likes

These drugs focusing on rare diseases (so-called orphan drugs) usually have completely exorbitant prices, because developing one new successful drug can very well cost over a billion, and if you have, say, a few thousand potential patients in the world, a simple division shows that it’s not profitable without a huge reimbursement price for the pharmaceutical company. However, the risk you raised about the company’s earned reimbursements is justified, because for example, Trump might disrupt the markets in an unpredictable way with both tariffs and by trying to lower the payable reimbursements in general:

This gene therapy is probably not genuinely relevant as a threat within the next 10 years, is it? Of course, one can always paint devils on the wall about how future wonder technologies will displace current products, but their widespread adoption and implementation often take a long time compared to proven solutions.

In the case of Ruconest, competition will certainly come immediately from the recently approved Ekterly (sebetralstat), and in the coming quarters, we will see how badly it impacts Ruconest’s drug sales growth. Ruconest is a biological drug, and I am not aware of any projects to develop a biosimilar, so ‘similar products’ are unlikely to enter the market to compete on price with the original product.

Regarding Joenja and KL1333, to my knowledge, there is no alternative treatment on the market, so for now, we are safe from competition, and currently, the majority of the company’s value is, in my opinion, in Joenja, with Ruconest acting as a cash cow to finance these ongoing massive upfront investments in expanding Joenja’s markets and indications.

I would also politely ask you to stop trolling. I pinged you into the thread because I thought that as an experienced pharmaceutical company investor, you would be able to provide factual and sharp comments on the company’s business for the benefit of everyone reading the forum. Now it seems a bit like you have some personal vendetta going on due to my previous Faron writings. If you feel that I have offended you or written inappropriately or incorrectly in another thread, I am willing to discuss the matter via private messages and apologize if necessary. I want to believe that you can do better.

6 Likes

I wouldn’t see gene therapy as a viable threat in this case yet. Your example of hemophilia is, in my opinion, a good point of comparison. Hemophilia is currently treated mainly with recombinant proteins, but there are also various AAV-based gene therapies for its treatment that have received marketing authorizations.

The Case of Sangamo Therapeutics from the turn of the year is a good example of a problem related to gene therapies: https://www.fiercebiotech.com/biotech/pfizer-cuts-losses-near-approval-hemophilia-gene-therapy-adding-troubled-sangamos-woes. Sangamo was developing an AAV gene therapy for hemophilia A with Pfizer and was very close to approval, until Pfizer terminated the collaboration agreement. The reason was a re-evaluation of the market situation and the drug being deemed commercially unprofitable. Two of those hemophilia A AAV therapies have apparently been approved at the moment, and Sangamo’s drug would be the third on the market. However, around the time of that news, I looked at their sales, and the market’s second player, BioMarin’s AAV drug, had sold exactly one unit in the previous quarter for $800k. That doesn’t cover development costs very quickly yet.

If Pharming’s protein can be produced cheaply in rabbits, it may be very difficult to bring a competing commercially viable gene therapy to the market.

5 Likes

Yep, replacement therapies for enzyme deficiencies and hemophilia can cost hundreds of thousands a year. Good for Pharming. But, if and when gene therapies arrive, their current cost of a couple of million is small.

Everyone can calculate how long they believe it will take before a replacement therapy comes. 5-10-15 years? On the other hand, patents for ordinary medicines don’t last much longer than that, so the money has to be made in that time. So it wouldn’t be a very exceptional risk. I can’t think of any other very dramatic risks for Pharming right now, but I haven’t delved deeply into it, not even to invest.

First, if presenting your generalizing statements about biotechs in a biotech thread is trolling, then it’s good that you understood your message as trolling. I know that this time this case is different. Peace and love :heart_hands:t2::handshake:

2 Likes

At the EU level, political will seems to be towards better recognition and treatment of rare diseases. https://www.eesc.europa.eu/en/news-media/press-releases/rarediseases-eu-action-plan-must-step-european-national-cooperation

I had to comment on this. If one is looking for a pure pharmaceutical company that already has commercial-stage products, as well as pipeline assets, in such a way that one can still get significant exposure to the upside/risk of development-stage assets, there don’t seem to be many quite similar ones besides Pharming. I tried screening those on Benzinga. Especially if incipient profitability is also set as a criterion. IOVANCE is valued at roughly the same level and they have 2 commercial products, but they are heavily unprofitable. In the Medtech sector, there are several companies in the same ballpark in terms of revenue and valuation.

But then again, it depends on what kind of target one is looking for. If one hates binary outcomes, here one can still get significant exposure to pipeline development, but the existing commercial side provides a backstop. The dynamic naturally changes as one moves to larger biotechs. With Big Pharma, the failure of one asset in one indication usually no longer moves the stock price more than normal fluctuations.

That publication in Cell journal and thereby the significance of re-evaluating VUS cases is indeed tricky. A basic scientist like me cannot quickly form an opinion on that, and I’m not at all surprised why the market didn’t react. The market is efficient at interpreting numbers. But with qualitative information, it stumbles randomly. Here, perhaps, alpha is available for the diligent investor.

8 Likes

Now that the stock has risen nicely after the pitching and we are approaching the billion-dollar milestone, I wrote down the sum of the parts and why I believe 2 billion dollars will be broken, meaning at least a 100% increase will still occur in the next 12 months.

Ruconest: 500 MUSD
Let’s take very conservative expectations for Ruconest’s near-term sales, assuming sales will remain at 300 MUSD this year, the same 300 MUSD next year, and then an annual decline of -11% until 2035, when sales end. EBIT 50% and WACC 10%.

If sales prove to be more sustainable, the entire current valuation can be justified by Ruconest. On the other hand, if a strongly competing drug enters the market soon and sales plummet more sharply, we won’t even reach half a billion. So, I would start with 500 MUSD and adjust it according to future quarterly results. It is especially important to monitor Ekterlynn sales and its impact on Ruconest.

KL1333: 0 - 5300 MUSD

The lower end for KL1333 is easy to estimate as zero if it doesn’t pass through studies, but otherwise, it becomes quite a shot in the dark. If we assume a US launch in 2028 and the rest of the world in 2029, with peak sales of 3.1 billion dollars in 2033, we can reach a maximum valuation of 5.3 billion (WACC 10%, 50% EBIT). I assumed about 36 thousand patients would be found in Pharming’s markets, of which 16.5 thousand in America. There is enormous uncertainty regarding the price, but I guessed a net of 300 k$ / year for the US and a net of 150 k$ / year for the rest of the world (UK, EU, Canada, Australia). Royalties must be paid to Yungjin in high single-digit to low double-digit percentages, and sales are not possible in Japan or South Korea.

Of course, that upper limit will likely not be reached, but even if one were to assign unpleasant probabilities of failure in phase II and phase III trials, I find it difficult to credibly argue why the KL1333 valuation should be below half a billion dollars in a base scenario. If successful, it should quickly become a billion-dollar drug, unless a competitor’s Sonlicromanol (KH176) succeeds big and cuts into sales.

Joenja: 300 - 8600 MUSD

Joenja’s base scenario, under which the drug was originally launched, seems rather dull because APDS is such a rare disease that the drug’s value does not rise very high. If we assume 400 K$ / year from a US patient and 150 K$ / year from patients in the rest of the world, and only over half of patients end up in active treatment and as Joenja users, sales might remain at the 140 M$ level, and the drug’s value would be a pathetic 300 M$. Novartis receives double-digit percentage royalties.

The VUS → APDS news in the summer was significant in that, if Pharming’s own figures are used, it almost doubles the achievable patient number and thus the drug’s value. From Cell’s research, a huge potential can also be estimated if it is assumed that the prevalence of APDS is tens of times more common than previously thought, in which case, for example, an additional 12,000 patients can easily be obtained, and sales jump to 3.5 billion dollars and valuation to 7.65 billion dollars.

Since Pharming is now restarting additional studies on redefinition, it will likely end up somewhere between this immediate VUS → APDS sales potential increase and the extreme potential.

If the PID study is approved and it goes on sale in 2031, conservatively estimated, about 1500 patients would probably be obtained, leading to sales of 390 M$ per year and a valuation of 200 M$.

CVID would probably conservatively bring 8600 patients, and if sales start in 2032, with peak sales of 2100 M$, the present value for this success would be 750 M$.

Looking at the matter from these starting points, I believe the market underestimates the value of Joenja’s numerous different options, and I myself would give the drug about a billion valuation at this stage, which, however, relies heavily on the market not having internalized the full value of that summer’s VUS → APDS pipeline study. If you don’t immediately grasp the matter, then no small investor will understand a thing about it, so I would consider a market error very possible.

Summary:

Of course, there are still enormous uncertainties here, and imagination must be used in the assessment, taking a bold view despite the lack of precise information, as in all good investment cases requiring an assessment of future growth and profitability. I believe that the markets will digest the information over the next year, and as the news flow from KL1333 and Joenja studies begins to approach, investors’ expertise and understanding will grow accordingly, and the stock price will continue its positive movement above two. After that, execution will already be necessary if further steps are to be taken.

15 Likes

This was of course already known to those following the company more closely, but it seems the company decided to announce it. There has been fierce trading in the stock at times, and it probably won’t decrease because of this.

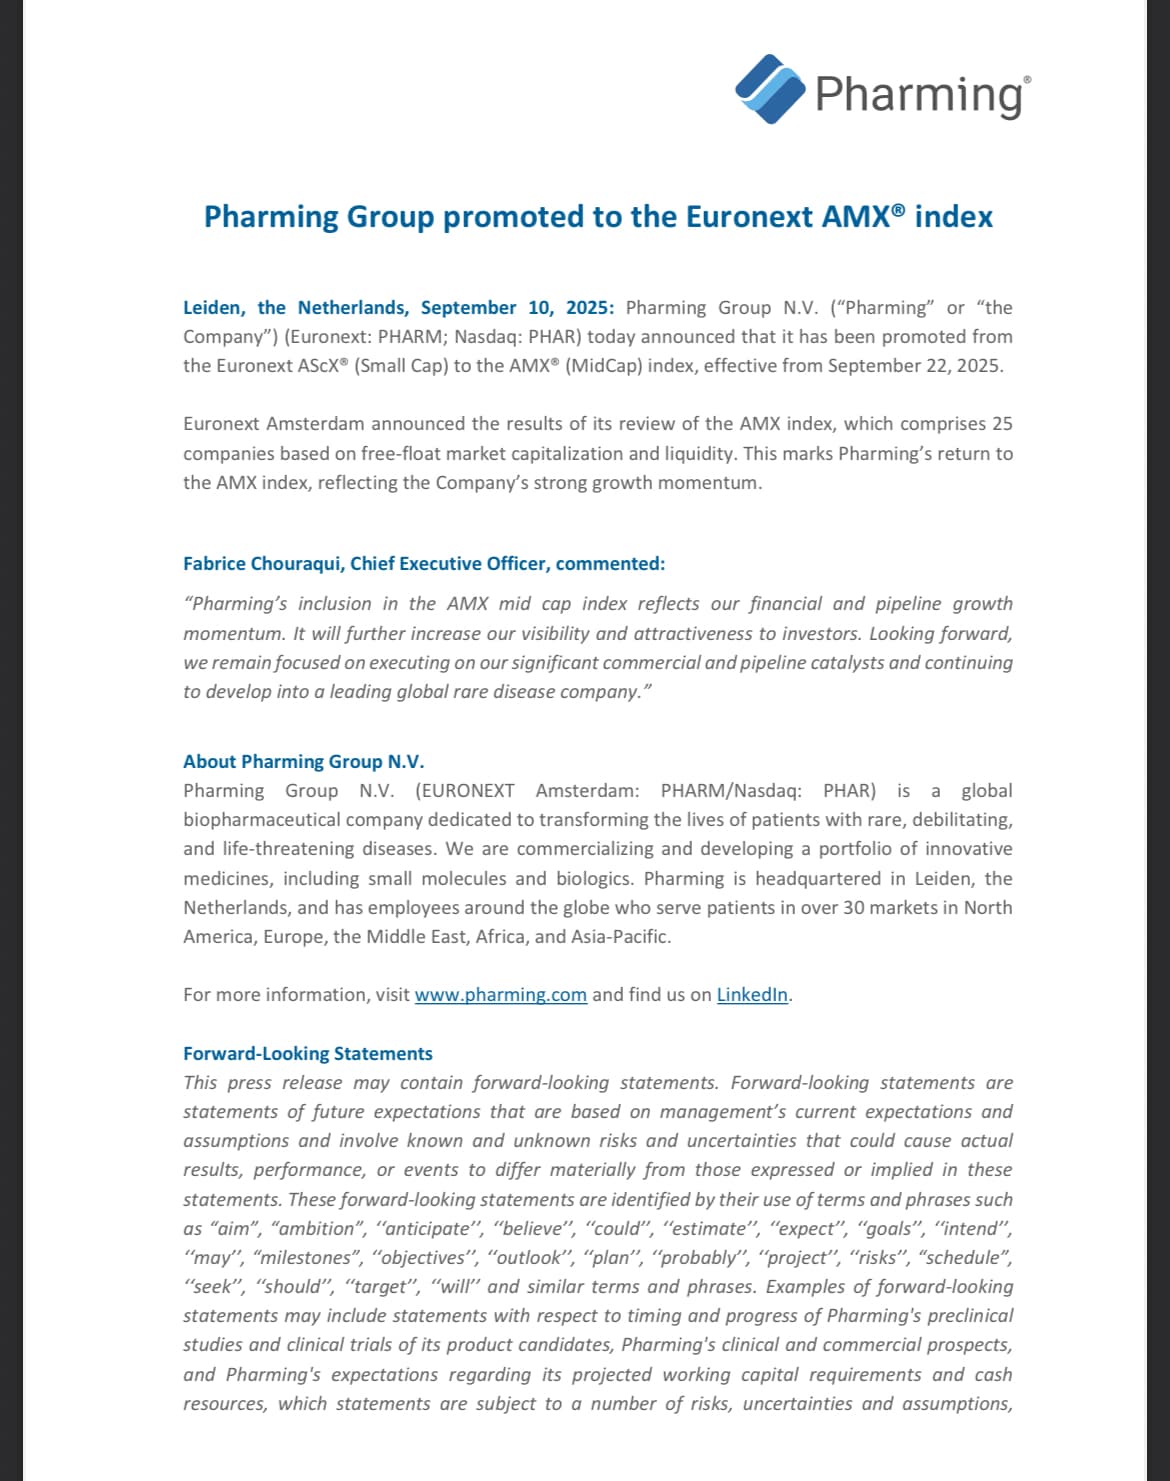
i.e., from small cap to mid cap index.

10 Likes

Apparently a pretty good start with Ekterly:

https://ir.kalvista.com/news-releases/news-release-details/kalvista-pharmaceuticals-provides-operational-update-and-7

“In just eight weeks following approval, we have received 460 patient start forms, representing almost five percent of the reported HAE patient population in the US. This early demand has exceeded our expectations, validating both the urgent unmet need that EKTERLY addresses and its potential to redefine management of HAE. Backed by a strong balance sheet and a world-class team, we are well positioned to maximize the global opportunity for EKTERLY to become the foundational therapy for people living with HAE.”

3 Likes

Donald Trump announces 100% tariff on branded pharmaceutical products

The stock reacted to the tariff news today. Does anyone else have information on how widely this will hinder sales of rare disease drugs, where alternative medications are scarce? Of course, this can be avoided by building a factory in the USA.

2 Likes

You never know about that orange weathervane, but I personally believe this: https://www.reuters.com/business/healthcare-pharmaceuticals/eu-japan-express-confidence-in-capped-us-tariffs-drugs-2025-09-26/

So, someone from the EU Commission commented that they believe the previously agreed 15% tariffs will hold.

…and I added to the dip.


(ABM FN-Dow Jones) Pharming gets 97 percent of its revenue from the United States, so it’s no wonder the share price was under pressure on Friday after US President Donald Trump announced he wanted a 100 percent import tariff on patented medicines. This was stated by analyst Lucy Codrington from investment bank Jefferies.

But whether the soup will ultimately be eaten that hot remains to be seen, according to the analyst. In her report, she wrote that European medicines fall under the trade agreement between the EU and the US, where the tariff cap is 15 percent.

According to Codrington, much ultimately depends on the implementation of the tariffs. And that is simply still unclear.

Moving Ruconest production to the United States is practically impossible, according to the analyst. Instead, she considers it possible that Pharming could quickly build up a large inventory in the US to withstand the “tariff storm” at least temporarily.

According to the bank, building up inventories in the US should also be successful for Joenjan. In this case, moving production would be possible in the longer term, Codrington estimates – possibly with the help of a CDMO (Contract Development and Manufacturing Organization), i.e., a manufacturer who could make the molecule on Pharming’s behalf.

Jefferies has a buy recommendation for Pharming with a target price of 1.40 euros. The share fell 12.7 percent to 1.11 euros on Friday.

Copyright: ABM Financial News / info@abmfn.nl

4 Likes

Pharming Group announces U.S. FDA acceptance and Priority Review of supplemental New Drug Application for leniolisib in children with APDS aged 4 to 11 years

the U.S. Food and Drug Administration (FDA) has accepted its supplemental New Drug Application (sNDA) seeking approval for leniolisib, an oral, selective phosphoinositide 3-kinase delta (PI3Kδ) inhibitor, as a treatment for children aged 4 to 11 years with activated phosphoinositide 3-kinase delta syndrome (APDS), a rare primary immunodeficiency. The application has been granted Priority Review and assigned a Prescription Drug User Fee Act (PDUFA) target action date of January 31, 2026.

5 Likes

Oh boy, Pharming’s Q3 tomorrow!!!

Will the series of good earnings continue or is disappointment in store?

Will EKTERLY destroy Ruconest as the king drug for HAE acute attacks already in the first few months?

Will Joenja’s user growth stop or will we see good development?

The stock price has unfortunately slipped from the wild rally after Q2. Is the rubber band stretched to its limit and tomorrow we’ll go to the moon, or will the string finally break and the whole company fly to the bottom of the gorge?

Junkbondking’s faith does not waver, I still expect this to be at least a wild multibagger by 2035! (Not an investment recommendation)

Why? Well, because Junkbondking expects the following catalysts (note the furious chat GBD prompting):

Year Event / Catalyst Estimated new revenue/year Estimated “bottom line”
H2 2025 :microscope: VUS patient reclassification (USA) +$30–50 M +$20–35 M
H1 2026 :baby: FDA approval for pediatric (4–11 y.o.) +$16–27 M +$11–19 M
2025–2026 :united_kingdom: UK: NICE recommendation & reimbursement +$10–13 M +$6–8 M
2026 :globe_showing_europe_africa: EU / Japan / Canada launches +$33–55 M +$20–35 M
2026+ :dna: Rare Immune Deficiencies (PID) +$70–135 M +$50–95 M
2026+ :brain: CVID with immune dysregulation +$210–500 M +$150–350 M
2027–2028 :high_voltage: KL1333 – mitochondrial diseases (research) TBD TBD

:bar_chart: Overall Picture (Joenja + Ruconest)

Timeline Revenue Net Profit
2025 (current state) ~$340 M ~$90 M
2026 (catalysts 1–4) ~$450 M ~$160 M
2028+ (all catalysts) ~$700–800 M ~$350 M+

So! To that 350 million, we throw in a 15 multiple (modest for an orphan drug company) and Pharming is indeed a over 5 billion company! And we are only in 2028, and KL1333333333 (a billion-dollar market for this too) hasn’t even broken through yet.

It always makes you rub your eyes, wondering what the heck, when you think about this company.

Most likely, all my assumptions are completely wrong and misunderstood?? POHJOLAN EKA come tell me!

P.S. Not many expectations for tomorrow’s earnings report. It would be nice if those spearheads grow a bit.

P.P.S. They published a 10 million savings program for administrative and other ‘fluff’ expenses a while ago. Hopefully they’ll throw that money into genetic tests or something.

8 Likes