This is indeed very surprising. Ovaro just raised additional debt and is now distributing large extraordinary dividends.
Why weren’t share buybacks continued?
Perhaps this is then a sensible way for owners to return/release capital?
This is indeed very surprising. Ovaro just raised additional debt and is now distributing large extraordinary dividends.
Why weren’t share buybacks continued?
Perhaps this is then a sensible way for owners to return/release capital?
The market clearly thought it was good news when the stock, which had been languishing for a long time, rose almost 7.5%, but… When the P/B ratio is as low as it is, buying back shares would have seemed to me a smarter way to distribute funds, if it was even necessary to distribute them at this stage instead of using them to pay down debt or keeping them as a reserve for new projects. This mainly reminds me of Investor House’s absurd stock surge based on dividend news in late summer, albeit on a smaller scale. Even though the stock I own to a moderate extent did rise now, I can’t really be happy when a) the company’s board made what I consider a foolish proposal and when b) the market reacted to it foolishly, in my opinion. Well, one could always lighten the ownership and buy, for example, Asuntosalkku or Kojamo instead… But perhaps I’ll still monitor the situation, as Ovaro isn’t expensive yet.
I estimate the same. I would have preferred share buybacks.
I assessed point b) the same way, so I reduced a reasonable portion from my modest position, even though I still consider Ovaro reasonably affordable.
Let’s see if I can get the shares back cheaper.
The distribution of dividends would somewhat indicate that the company has a good outlook on its financial situation.
Discussions have certainly taken place with financiers, and one would assume that new financings include some form of covenants based on solvency.
I would assume that sales negotiations for current properties might be underway.
If the company has an outlook that after events in the near future, it will have excess capital and no major new investment opportunities are in sight, then it is somewhat logical to distribute it to owners.
This would allow the company to achieve a more targeted balance sheet position, enabling higher returns on equity. The company has commented that the buy-develop-sell model is intended to be operated in a capital-efficient manner and to rotate the balance sheet. If successful, there are opportunities to achieve good returns on equity, in which case P/B ratios should also rise, provided evidence of this begins to emerge.
A share buyback would have been a good alternative, but it is quite slow.
Follow-up to previous: I did, however, end up selling my entire position. I couldn’t quite hold out until last week’s peak, but I still made about a 15% profit with about half a year of ownership. I will keep an eye on Ovaro and might buy the shares back if the price is attractive enough again.
Here are Frans’s comments on how Ovaro is implementing an extensive financing and real estate arrangement that improves, among other things, the company’s solvency, etc. 
Roininen, who has served as Chairman of the Board since 2017, is stepping down from the board next spring. He has certainly brought about a major transformation in the company during his tenure. Additionally, Jorma Nieminen is also stepping down. The proposed composition for the board is: Taina Ahvenjärvi, Juha-Pekka Eskola, Pekka Ollikainen, Aki Pyysing, and Tapani Rautiainen.
Roininen’s departure is certainly a negative in my book, without taking anything away from the continuing board. I’ve liked the man’s gritty style in various interviews, and he has undoubtedly played his part in the successes of both Ovaro and Investor’s House.
Everyone certainly defines success in their own way, but if the share price drops from 13 euros to three euros during a CEO’s tenure, then in my opinion, it doesn’t fit the definition of success.
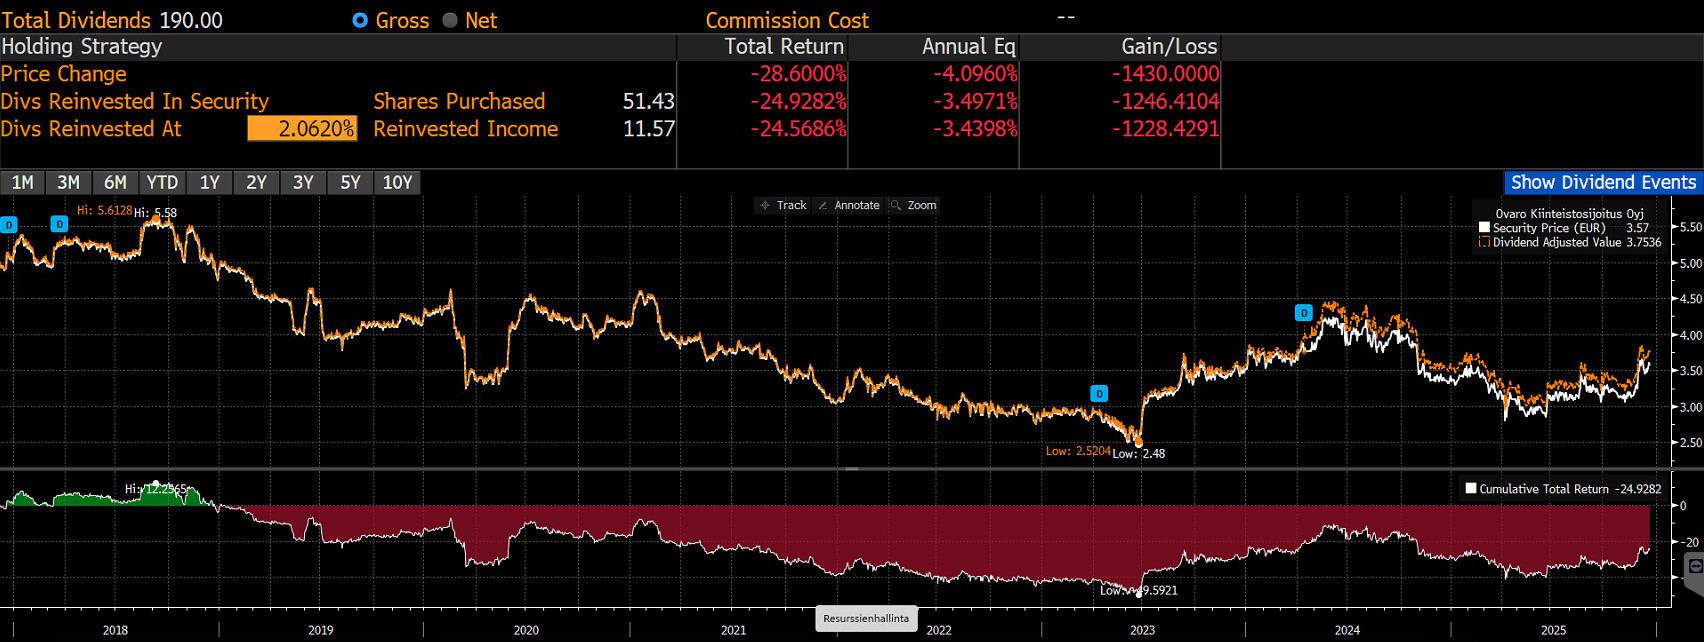
Looking at Bloomberg for Ovaro’s total return data, since December, when Roininen became Chairman of the Board, the total return has been -24.5%, which is certainly not a good performance. Considering the situation Ovaro was in when he arrived, the performance is not bad imo. I would personally view it as a positive, though of course, it depends a lot on how profitable the current investments eventually turn out to be. Without the moves made in the company during Roininen’s tenure, returns would likely be on the weaker side of -90%.
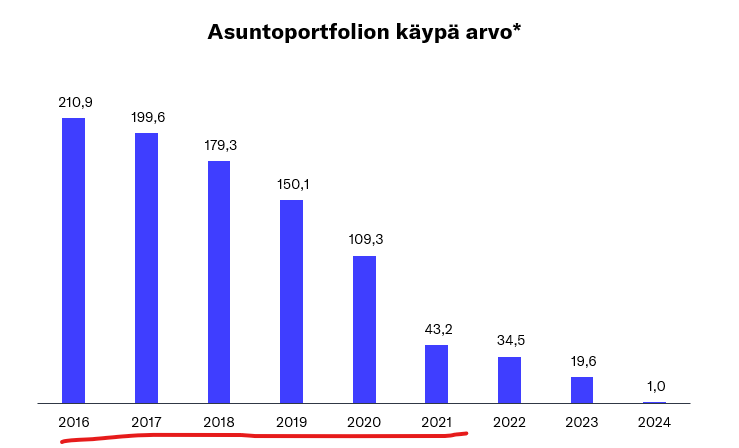
This article clearly shows how weak the company’s situation actually was. If the governance changes hadn’t been made and apartments hadn’t been sold, the company most likely would not have been financeable once interest rates rose. They would have had to raise capital at very low valuations or fire-sell properties at even significantly larger losses. The company also had good luck, considering how significant a portion of the portfolio was sold at a truly excellent time.
Here is a fresh company report on Ovaro from Frans.
Real estate development company Ovaro is implementing a significant real estate and financial arrangement in December, which releases capital, strengthens the company’s financial base, and lowered the risk level. Due to the positive fair value change resulting from the land acquisition, our 2025 earnings forecast rose, but the forecasts for the coming years fell as a result of the arrangement. Our dividend forecasts rose as a result of the balance sheet becoming more efficient. Overall, adjusted for dividends, our 2026 equity per share forecast rose slightly. Despite the rise in the share price, the low valuation (2026 P/B 0.66x) combined with a dividend yield of approximately 4%, a lowered risk level, and the potential of the project pipeline keeps the risk/reward ratio positive in our view. We reiterate our target price of EUR 3.70 (note the EUR 0.36 dividend detaching on Monday) and our Accumulate recommendation.
Ovaro is raising its guidance for its 2025 result (previous: better than EUR 586k; now: EUR 1.3–1.6m). Unfortunately, even the raised range falls short of Inderes’ forecast (EUR 2.0m). On the other hand, for a company of this type, the result for a single year fluctuates quite a lot anyway, so this news likely doesn’t carry much significance. The share price didn’t react more than typical daily volatility either.
Here are Frans’s comments regarding Ovaro’s specified guidance, among other things.
Ovaro Kiinteistösijoitus specified its 2025 earnings guidance on Tuesday. The company estimates that the result will be between 1.3–1.6 MEUR, which is a clear improvement from the comparison period (0.6 MEUR), but falls below our recently raised forecast (2.0 MEUR). The shortfall is most likely due to a decrease in the fair value of office property assets.
Here are Frans’s comments as Ovaro launches an 8 million euro apartment building project in Kerava.
Ovaro Kiinteistösijoitus announced on Monday that it has started construction work on an apartment building in the center of Kerava. The project has a pre-sale rate of approximately 50%, and in our view, the start of the project is a critical step forward for Ovaro’s property development business. It is a concrete step in the company’s strategy, where the focus is shifting heavily towards real estate development and construction. In the big picture, the implementation of the project is in line with our forecasts, but the completion scheduled for the end of 2026 brings revenue into our forecasts sooner than previously estimated.
The flow of cautiously promising news continues. As some of the all of three followers of this thread might recall, I cashed out my small Ovaro gains in early December at the price driven up by the dividend news. However, I bought them back with limit orders when the share price was at a low point earlier this month. Measured in euros, the benefit of this amateurish flipping was pretty much net zero. But especially these days, it feels good to be on board with a company like this, which is completely immune to Trump’s tariff shenanigans.
The stream of cautiously good news continues. A hotel property was sold slightly above book value. Since the P/B ratio is around 0.6, the deal sounds quite good from the outset. If the proceeds were used for share buybacks, we would essentially get a double benefit from the deal and the low book value.
Here are Frans’s comments as Ovaro sold its Jyväskylä hotel property for 3.05 million euros.
Here are Frans’s preview comments as Ovaro releases its Q4 results on Thursday, Feb 26.
We forecast the earnings level to rise to a fairly good level due to a positive fair value change of the land area in the Jyväskylä Kukkula project, although we expect a negative fair value change for the rest of the real estate portfolio. We anticipate the company will guide for stable earnings performance. In 2026, it is critical for the company to launch new projects from its pipeline and create the conditions for starting new construction in the Jyväskylä Kukkula project. We expect a dividend proposal of EUR 0.13.
Frans interviewed Ovaro CEO Marko Huttunen regarding Q4
Topics:
00:00 Introduction
00:16 Highlights of the end of the year and the full year 2025
01:57 Large one-off items in Q4
03:11 Acquisition of the Kukkula land area in Jyväskylä
04:07 Challenges in Hervanta
05:03 Dividend proposal
06:16 Market situation in terms of sales
07:18 Guidance
08:18 Key projects in 2026
09:14 The major Kukkula project in Jyväskylä
10:38 Residential project in Kerava
A question for management and the board: at these levels, wouldn’t it be better to initiate a share buyback program rather than paying out dividends? 