Repetition is the mother of learning…so the saying goes.
Above in the thread, there’s talk again about this big pharma topic… I wonder what this mystery company might be.
I don’t suppose there’s any ambiguity about this. This was revealed in connection with the Gitex Morocco event so clearly that it leaves no room for interpretation. Laura Piila revealed this in her post, and AstraZeneca also used the term partner for Optomed in its post.
Here is Piila’s post again. Also read the text in that one photo, which roughly translates to… “The Lumo CKD combination will be integrated into HHA units”.
I asked about this regarding the Inderes interview video, now when considering additional purchases this came back to my mind… does anyone have a clear interpretation of what Juho might have meant?
It can be found at the very beginning of the H2 interview, from the 2-minute mark onwards.
Of course, Optomed is not mentioned by name, but anyone following the case knows it’s about Optomed. What’s interesting here are the bullet points at the end:
Local solution deployed (camera + AI + cloud)
New markets and contracts generated
A recurring revenue-based business model has been built in China (new business model with recurring revenue in China)
But Optomed will come out with this when they see fit. Still binary. Clearly.
I was thinking that WISER Falcon could easily take this concept outside of China as well.
In other words, Optomed Camera, Chinese AI, and Huawei cloud services. This would be a direct competitor to, say, AstraZeneca in Africa, but we don’t mind that, as long as the camera comes from Optomed.
Optomec’s (Optomed) ownership stake in the joint venture is 20%, but the cameras are presumably leased to this company. Likewise, the screening and result processing are likely also localized Optomed software. The completion of the localization work was mentioned in some earlier interview. I couldn’t quickly find the source to verify.
I don’t expect a cash flow resulting from the ownership stake just yet, but based on current information, a small stream of revenue from those software and device leases should already be flowing directly to Optomed.
20% is a good share, considering the size of the potential market. It would just be appropriate to get some information directly from Optomed at some point. Until then, this is binary, and I am personally skeptical about the success of foreign companies’ ventures in China. If something seems to work, it gets copied and orchestrated locally, as soon as all possible assistance has been squeezed out of the operator. Of course, this is slightly supported by the fact that 80% is Chinese, meaning it might fly under the party’s economic safeguarding radar.
Focus on the US and the expansion of Aurora AEYE. Western companies should only go try their luck in China when they have large amounts of cash burning a hole in their pockets, and management doesn’t want to distribute it as dividends.
I was just browsing through Optomed’s communications out of curiosity.
6.11.2025we move from validation toward the early execution phase
10.2.2026: In China, the Company’s joint venture has progressed according to the plan, however, no revenue is expected during the next few quarters.\n* 6.5.2026The China joint venture continues to progress according to plan, although the opportunity remains binary and no substantial material revenue contribution is expected in the near term.\n\nAnd now that Wiser:\n\n* new markets and commercial deals created\n\nThis certainly looks like things are progressing. One could easily agree that Optomed could be more transparent in its communications. However, another perspective is that China is China, and nothing can be taken for granted until cash starts flowing into the account (as has already been seen!). Until then, the case may well remain “binary”, even though the probabilities might tilt towards success soon becoming more likely than failure. However, if things are foggy in the US regarding, among other things, the true size of the market, I honestly believe it is even foggier for Optomed in China.
If and when a share issue is not planned, I don’t see any significant benefit in hyping this up in a big way until recurring revenue is actually flowing into the account. Deals created doesn’t mean that yet – it can take a long time from an agreement to implementation and the realization of cash flows.
Anyway, this is positive all the same, and also the kind of Opto-option that is not yet priced into the share.
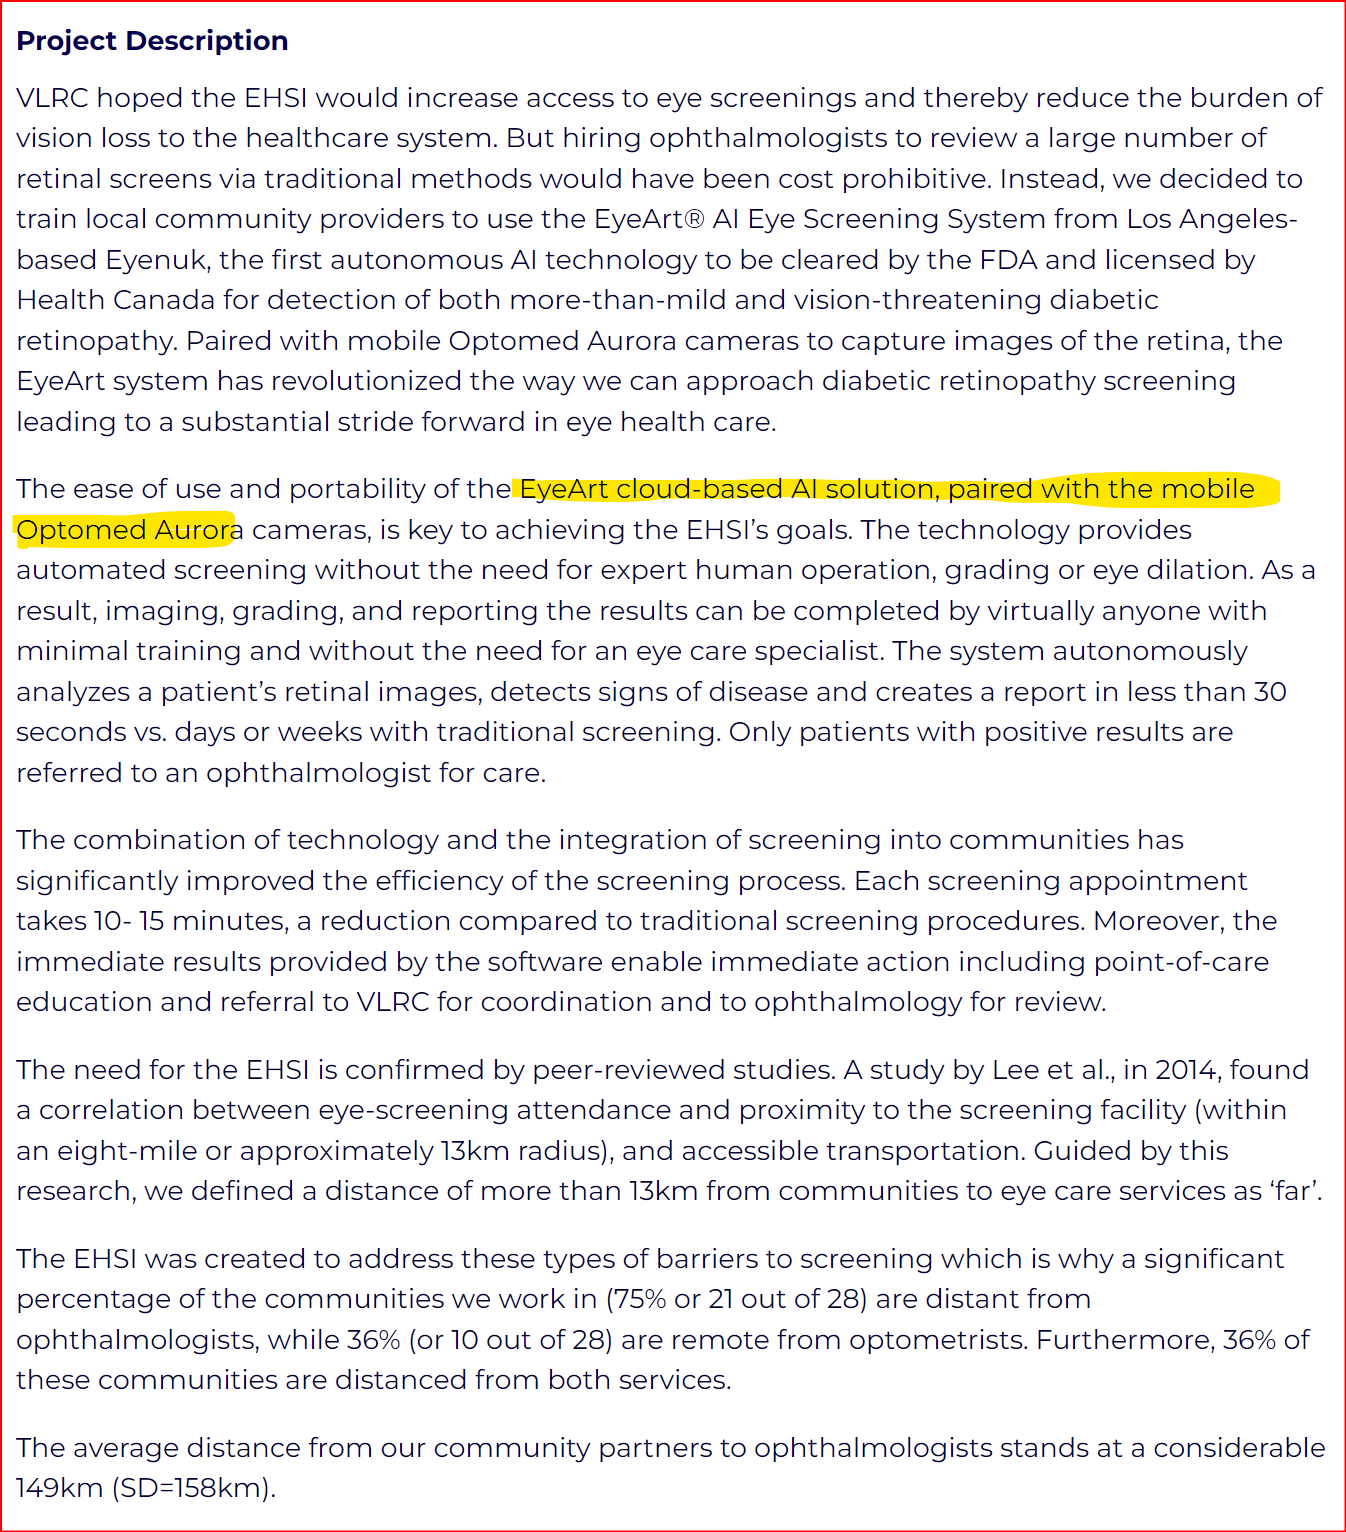
New information regarding the Vision Loss Rehabilitation Canada screening project. The results look promising, and at the same time, this article confirms that Optomed’s cameras are being used.
It states:
“The model also improves quality and efficiency by pairing technology with standardized practice. Upgrading to newer portable fundus cameras strengthened image quality and workflow, with some sites increasing screening volumes by sixty percent after replacing older equipment.”
The picture shows an Aurora, but could this also be referring to Lumo?
VLRC’s Optomed Aurora + Eyeart was indeed recognized at the HLTH ceremonies some time ago. Optomed Lumo received Health Canada approval over a year ago, meaning they might have already had time to test Lumo + Eyeart as well.
That’s a reference from Finland’s largest gambling operator. There are around 50 other license applicants, and in terms of credibility, this is a great win which makes it easier to start selling the service to other contenders.
I heard the name Ubetec for the first time last week, and it would certainly be nice if something trickled down to the bottom line. At some point, I’ve definitely been getting Tecnotree vibes, with expenses conveniently matching revenues. I just hope for transparent reporting and that something from the Optomed subsidiary is also distributed as profit.
Is it true that all of Optomed’s SW side is now under this subsidiary, or just the compliance side? Or do they even have any other software operations?
This Ubetec has certainly been under the radar for quite a few people. The truth is that it’s going to be the largest provider/operator of gaming compliance services for Finland’s opening betting market. The reasoning: it is strongly connected to the guiding/decision-making bodies. The software will take a big leap in 2027, and this explains why they changed their accounting practices a while ago…
Indeed. Gaming operators won’t be choosing their partner based on price here. Ubetec is likely the only player that thoroughly understands the regulation of the Finnish gambling market. This will also generate a nice amount of additional revenue if, say, 10 entrants choose Ubetec as their partner, resulting in high-margin billing of €0.5M/customer/year starting next year.
What I wonder most about here is how no corporate giant is throwing a lifebuoy to Optomed; this valuation is just so ridiculous. If AstraZeneca or some Topcon just wanted to, they could make this profitable in just a few weeks using their own contacts. I wouldn’t mind at all if the whole joint were sold for 100M. That 100M price tag would be something I’d be willing to part with my shares for, and leave a bit extra for new investments. Even though that 100M price is small change for these patents, FDA approvals, and other software. It’s been driven down so steeply that it would be a miracle if something didn’t pop up from somewhere in the world soon.
It’s unfortunate, but in my book, a €100M price tag would sting like Instrumentarium’s sale and I wouldn’t sell. I’d rather collect a €0.50 dividend in 5–10 years than put my name on a sales agreement next year at a €5 share price. There’s always time to sell later.
This Ubetec pattern has gone completely under my radar. What is the actual purpose of this subsidiary, which is completely outside Optomed’s core business? It doesn’t seem to be some passive side project. Ubetec has its own products and operational management, and now also its first significant commercial proof point. And then there’s the governance. The Chairman of the Board of Ubetec is Petri Salonen, Chairman of Optomed’s Board of Directors; a member is Laura Piila, a member of Optomed’s management team, head of the Devices segment, and head of the Chinese company; and the deputy member is Juho Himberg, CEO of Optomed. So Ubetec is quite directly under the guidance of Optomed’s top management.
At this point, I think it’s quite appropriate to ask about focus. Optomed’s history unfortunately includes a lot of raising new money from owners. At the same time, the company should now get Aurora AEYE flying commercially, utilize opportunities in China, and turn cash flow sustainably positive. Are management’s time and the company’s limited resources really in the best possible use while building a gambling industry technology company alongside them?
Ubetec may well turn out to be a good investment. The investor’s problem is that it cannot be evaluated with current information. We don’t know its revenue, earnings, capital invested in it, or what Optomed is ultimately aiming for with it.
I wouldn’t dismiss Ubetec, but I would like a pretty clear answer from management. What is the strategic purpose of Ubetec, how much money and management time is spent on it, and above all, how does this fit into Optomed’s focus and the creation of shareholder value?
As I understand it, this Ubetec came about after Optomed acquired Commit Oy in 2018, which is the current software branch. And Ubetec has now been spun off from that. It would certainly be sold if a buyer offering enough comes along.