The stock price continues to slide in the aftermath of the earnings report. Currently, it’s at -16% from the level of the day preceding the earnings report. Nothing new has been heard, but as an interesting detail, the company now has more cash than its market cap. Debt-free company, more cash than market cap, revenue 82.8 M
8 Likes
My interpretation is that there are a few things behind the cheap valuation:
- The company has a history of 1 quarter as a listed company
- OMSE is a truly micro-cap company
- Related to point 2, the company is both small and has a very small free float (the CEO owns almost 70% of the shares as a result of a management buyout).
- The company is currently very dependent on Saudi Aramco, even though they have long-term contracts and a clear plan to expand elsewhere.
- A large cash pile, and no other allocation decision than shy communication about growth ambitions (meaning M&A and increasing R&D budgets). This may signal to the market that the company does not have a clear plan for its cash.
- Why doesn’t the company start buying back its shares if management believes it’s undervalued? Well, one reason is, of course, that the float would decrease even further, and it’s possible that the main owners want to lighten their holdings a bit. They bought this out for a couple of million, and the market value is now over a hundred million.
For the value to be realized, what is now required is simply a solid history of being listed, a clear capital allocation plan, and perhaps even the initiation of profit distribution, which would also attract dividend investors.
16 Likes
I’d like to buy, but where can I see the offer levels? I wouldn’t be interested in raising it by 20% with my own purchase of such a low-volume stock.
On Yahoo!finance, prices are shown almost in real-time; just enter the OMCE ticker into the search field. I use that for these US stock market lottery tickets whose prices fluctuate wildly. I haven’t found actual bid/ask levels (cf. Nordnet) from this either, but it’s better than being blind.
2 Likes
New connector orders were received in late January, totaling $2.2 million:
Additionally, a $2.3 million additional tax assessment imposed on the company’s Saudi Arabian subsidiary by the Saudi tax authority (concerning the 2017 fiscal year), which OMSE paid in 2024 to avoid late interest charges, was overturned in December 2025 based on an appeal. The refund of the funds is currently awaited.
10 Likes
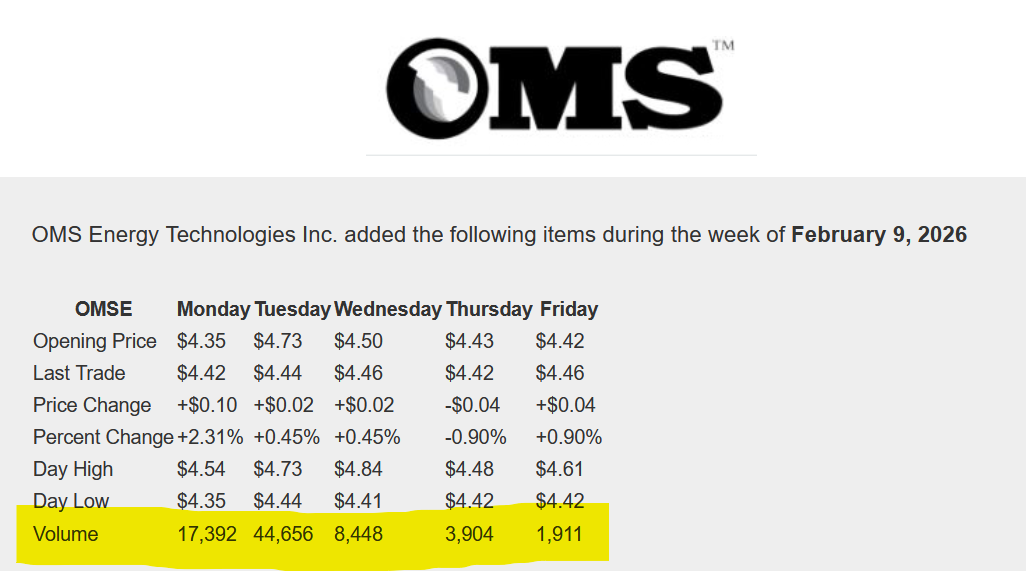
The stock price has been trading sideways for a while now. You can see from the volume that at least last week, the stock didn’t attract much interest.
4 Likes
Posting this here as well, as it relates quite significantly to OMS. Aramco’s production facilities are thus the target of an attack/attacks.
4 Likes
Saudi Aramco released last year’s results today, and their CapEx remains high. Aramco confirmed investments of $50–55 billion for 2026 vs. $52 billion spent in 2025.
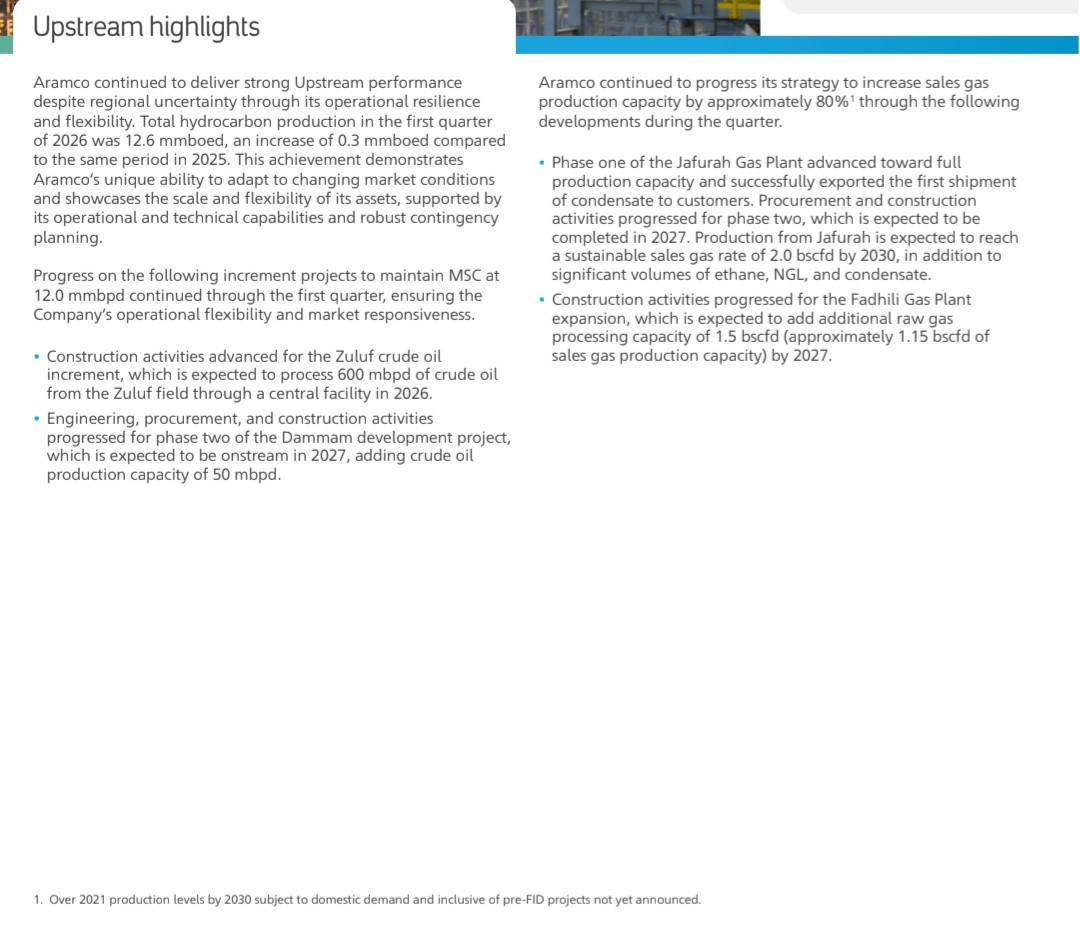
Additionally, Aramco’s gas strategy benefits Omse because their wellhead systems are high-margin products. Aramco’s goal is to increase gas production by 80% by 2030. This is also related to the API 6A certification granted to Omse in January 2026, which provides a ticket to participate in the most demanding tenders.
Aramco confirmed at the same time that its flagship program iktva (In-Kingdom Total Value Add) officially reached a 70% localization rate in procurement at the end of 2025. Simultaneously, it announced a new target of a 75% localization rate by 2030. Omse has a factory in Dammam, Saudi Arabia, and is a so-called local player.
9 Likes
Small orders from Oman, Pakistan and Indonesia, worth a total of $2.6 million.
6 Likes
Now something a bit bigger
5 Likes
One would think that rising oil prices and attacks on oil infrastructure would lift the stock price more. And now new contracts from new customers, which reduce customer risk, are of course bullish for OMS.
I own a small position and still see an excellent multibagger opportunity in prices below $5.
3 Likes
When the war started, I wondered if this would be a similar “one-off” investment wave that boosted the company’s profits in 2024? Gas and oil fields and refineries are being blown up in such a way that one would think there would be demand for pipes and fittings for years?
If orders start flowing in, then yes. Limited supply and a sharp demand spike will push margins through the roof. You can’t exactly get this company’s products at every grocery store, can you?
5 Likes
Omsille Saudeilta 11 miltsin tilaus:
The stock price reacted to this… by falling.
5 Likes
I must correct you on that; this order was already published about a week ago. I recall the share price rising slightly then, but of course, that’s little consolation now that the price has since fallen.
Well, well, the news has today’s timestamp and Google Finance pushed it as a new thing. I didn’t check the source this time.
3 Likes
An essential page for OMS from Saudi Aramco’s Q1/26 earnings report, “Upstream highlights.” Oil capacity maintenance projects and gas growth projects progressed during the quarter as follows:
3 Likes
Earlier this week, I dipped my toes into the stock, at least temporarily. I spotted the thread back in October, but I had to take some time to mull it over.
I don’t see a huge amount of downside potential in the stock, but on the other hand, I can’t quite explain why the oil mania regarding the Strait of Hormuz didn’t stick to OMS. I think OMS just needs to prove first that it’s capable of growing its earnings. A microcap + Asian company under large Asian ownership is certainly easy to dismiss as a potential scam.
OMS doesn’t sell oil directly, but given that Iran bombed places across the Middle East to smithereens, one would think that the repair investments alone would fall into OMS’s lap. At least Saudi Arabia, UAE, and Oman are already OMS customers in the region.
On top of that, presumably every oil-producing country using the Strait of Hormuz has woken up to the reality that oil export methods must be diversified. The high price of oil (and gas) should attract investment into pipelines. This is where Egypt and Pakistan, which are outside the conflict, also enter the picture, and OMS has operations in those countries as well.
The API 6A certification in Saudi Arabia in January 2026 should further strengthen OMS’s position with the major operators in the region. That came just in time before the USA/Israel/Iran threw existing plans into disarray.
Interest in OMS is practically zero. You’re lucky if 7,000 shares change hands on a daily basis. The main owner didn’t sell big in December. I couldn’t get the order through on Nordnet; it kept giving an error message, but through Danske, it worked out fine.
The next report is next Friday, May 22nd. If the results, or especially the outlook, don’t surprise positively, then my view has gone completely pear-shaped.
Edit: Well, apparently it’s not necessarily today. Nordnet changed the date to a week from now, and I can’t find information on their website. Investor relations are top-notch. 
4 Likes
Fiscal year 2026 results will be released on Thursday, June 25, after the US market close. The earnings call will take place early Friday morning, June 26, Finnish time. 
5 Likes
The report is out and the call is over. Cash flow is looking decent, margins are solid, and growth is modest. There is cash on hand and the business seems steady. This probably won’t become a growth rocket unless the US-Iran situation creates significant replacement demand. The company could start aggressively buying back its own shares so that shareholders get their cut.
After the earnings release, the stock rose in after-hours trading and crashed at the open. Since then, the price has been fluctuating within a few percentage points.
4 Likes
I suppose this stock is flying so much under the radar that a war won’t affect it at all, even though you’d think it would surge quite a bit. Hopefully, there is demand for the products despite the sluggish share price.
3 Likes