Here’s a substantial reading package to remind us why we own this: NoHo Partners Oyj:n vuosikertomus 2025 on julkaistu | Kauppalehti
7 Likes
Happy Friday! 
NoHo Partners’ Annual General Meeting will be held on April 15, 2026, at 5 PM in Tampere. The venue is the familiar Eventum at Nokia Arena.
The reception of registered attendees, distribution of voting slips, and pre-meeting coffee service will begin at 4 PM. After the Annual General Meeting, shareholders will be offered dinner, refreshments, and an opportunity to meet company representatives. So, real dividends are taken care of, this time too. 
 The evening event for shareholders will conclude by 8:30 PM at the latest.
Registration opens next Monday, March 23, at 9 AM. Welcome! More information about the meeting and detailed instructions can be found here.
19 Likes
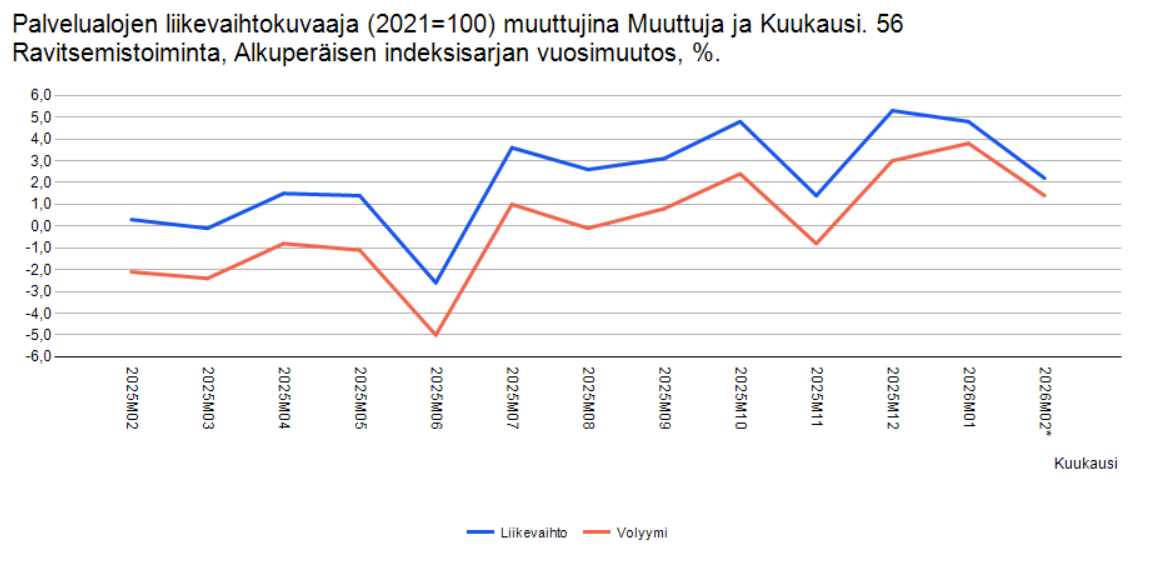
According to Statistics Finland, the restaurant services category achieved slight growth in February, both in euros (2.2%) and in volume (1.4%).
7 Likes
Good morning, when should NoHo Partners hold a general meeting in Helsinki, as that would also be a possible location in addition to Espoo and Vantaa, based on the articles of association? Tampere is a good location, but a bit too far for enjoying real dividends 
1 Like
Hopefully never. Helsinki already has plenty of general meetings, and NoHo is a Tampere-based company. Insider dinners have been held in Helsinki.
38 Likes
Uber Eats is apparently starting in Finland at the end of April. This is good because with Foodora withdrawing, Wolt’s monopoly would not be the best situation for Finnish restaurants:
Behind a paywall, but the most important part is above.
7 Likes
I agree, we in Pirkanmaa should also be given home-field advantage for local businesses! For me, it’s the only possible visit due to the distance, even though I have dozens of domestic companies in my portfolio. I’ve also talked to other participants from Pirkanmaa, and it’s an important issue for them too!
8 Likes
Hey! 
NoHo’s Q1 2026 interim report will be published on Tuesday, May 5th, at approximately 8:00 AM. You can follow the results webcast on the same day starting at 10:00 AM here. Questions are welcome!
More detailed information can be found, as usual, in the press release.
Some of you we might even see tomorrow in Tampere for the annual general meeting. See you there! 

12 Likes
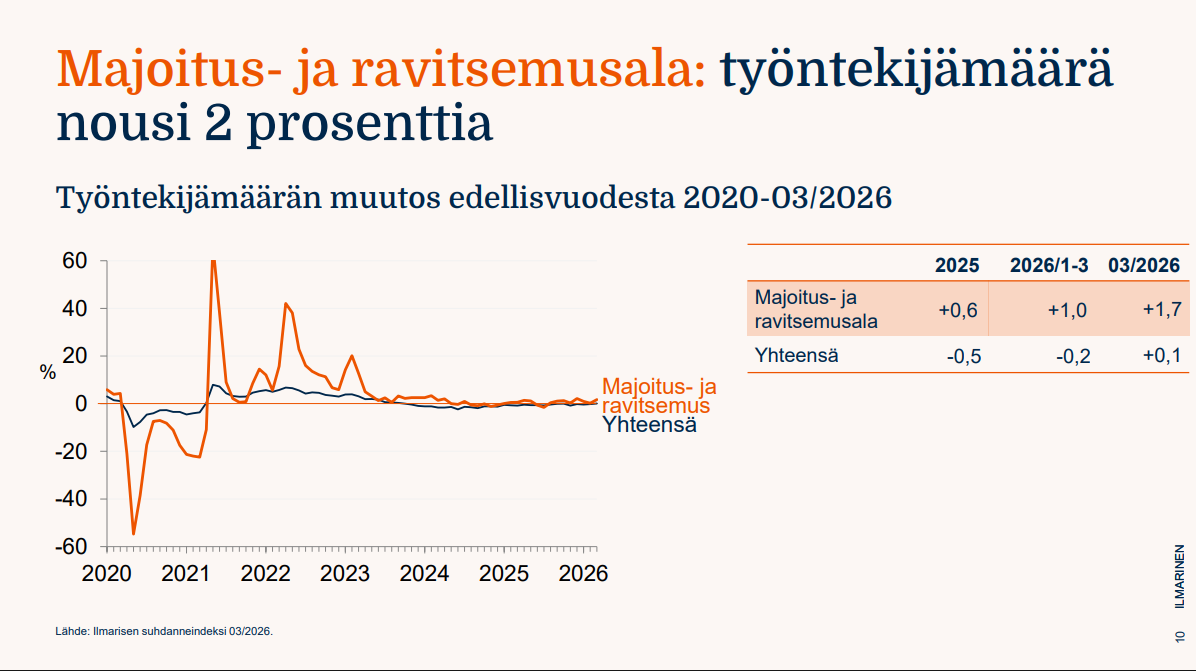
According to Ilmarinen’s business cycle index, there was quite good development in the accommodation and food services sector in March and the beginning of the year:
15 Likes
In my opinion, NoHo has been misunderstood. As a company, NoHo is a serial acquirer that should be compared to other serial acquirers in terms of valuation. As the CEO stated at the AGM – unlisted restaurants are bought at low valuation multiples, and once they are brought under the NoHo umbrella, their efficiency can be significantly increased in terms of both raw materials and personnel costs. In other words, typical serial acquirer business. However, in the restaurant industry, this scalability is likely much greater than is generally understood. That is why it’s truly excellent that they don’t just pay out all the profits, but instead grow the company using all available funds.
25 Likes
If anyone is interested in OP’s latest thoughts on NoHo in the form of an earnings preview, they can be found on this page.
Recovery in demand in Finland is likely still pending: In the main Finnish market, we estimate that the operating environment has remained challenging in Q1. Consumer confidence turned weaker again in January–March, after having gradually strengthened during the latter part of 2025.
We expect international revenue to have grown more significantly than in Finland during Q1, driven especially by organic growth in Denmark and the Halifax Burgers acquisition. For Norway, we expect revenue to be roughly in line with the comparison period. The progress of profitability turnaround measures in Norway is one of the report’s interesting points following the emerging signs of a turnaround in the previous quarter.
6 Likes
Picked from OP’s report:
Additionally, based on, for example, the January-February sales figures reported by Kesko,
demand in the HoReCa sector (which Kespro serves) has been slightly
negative in the early part of the year
Kesko’s March figures were released yesterday, and they showed good growth (+5.6) for Kespro; overall, January-March was down by only -0.3%. The January-February period mentioned in the OP report was still at -3.3%.
11 Likes
Oops. Went live too early 
As an addition to this message I wrote in the coffee room yesterday, I thought I’d comment with a few words on NoHo’s Annual General Meeting held on Wednesday, as no one else has taken on the task and on the train—surprise, surprise, to Tampere again—I have time to write.
The meeting venue was the familiar Eventum event restaurant at Nokia Arena in Tampere, as it has been for at least the past three years. What was new was the event moving from 10 AM to 5 PM in the afternoon. A good move in my opinion, though potentially slightly more expensive in terms of costs (referring to the generous drink service, and I suspect evening shift differentials apply to the kitchen and serving staff). However, the timing definitely suits working people better, and it was gratifying to see many young adults present; after all, they are NoHo’s core target group anyway when it comes to using restaurant services.
Both Chairman of the Board Timo Laine and CEO Jarno Suominen justified the dividend cut more extensively than usual; the idea is to bring the net debt-to-EBITDA (käyttökate) ratio to the desired and less risky 2x level from the current 3x, and of course, growth investments. There were indeed plenty of acquisitions last year, including the restaurant business of Wanha Satama, Jungle Juice Bar, and the acquisition of the 11-unit Halifax Burgers chain in Denmark; additionally, the core business in Finland was strengthened with selected deals, if I remember correctly, at least in Jyväskylä. So there’s plenty of work to do in realizing these synergy benefits. However, a dividend of 50% of the result was promised for the future as well. Whether the cycle of debt collection notices (trattakierre) at the end of last year played a part, I don’t know, but the CEO assured that the processes are now in order.
NoHo indeed has 294 restaurants in three countries, and the revenue is distributed such that Finland accounts for 264.8 million and others 93.2 million. BBS (Better Burger Society), which includes 34 Friends & Brgrs restaurants in Finland and
38 Likes
Here are Arttu and Sale’s early takes as NoHo releases its Q1 results on Tuesday, May 5, 2026
We expect the company’s revenue to have grown from the comparison period, supported by acquisitions, but organic development to have remained moderate due to the challenging market situation. We forecast that the company has defended its profitability well in domestic operations, but in our assessment, challenges in Norway will still weigh on the profitability of international business in Q1. We expect the company to reiterate its broad guidance. In our view, the key themes in the report are the progress of the turnaround in Norway and possible changes in consumer behavior as interest rates rise.
2 Likes
CEO’s review from last week’s Annual General Meeting!
7 Likes
Jarno’s review is very concise, in his typical style. A fairly good overview of NoHo and their operating model. It’s also clear from the comments that there wasn’t much satisfaction with 2025, as growth fell short. Problems in Norway were also discussed realistically, which is of course a good thing. Regarding BBS, the comments were typically positive, and high expectations have certainly been placed on this by NoHo.
19 Likes
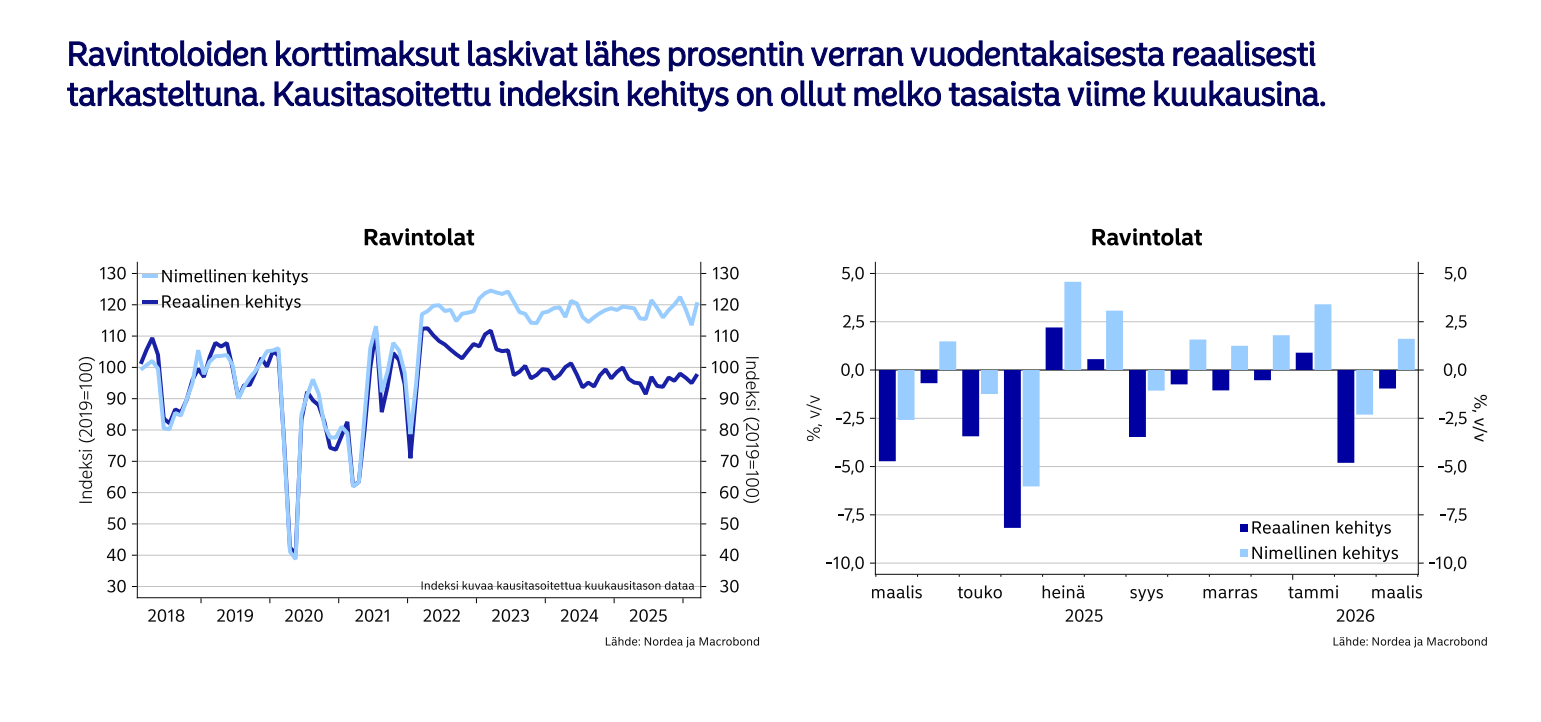
Nominally, card payments grew in restaurants in March, but in real terms, not so much:
Pirkanmaa and Uusimaa, which are key for NoHo, were quite strong on the services side:
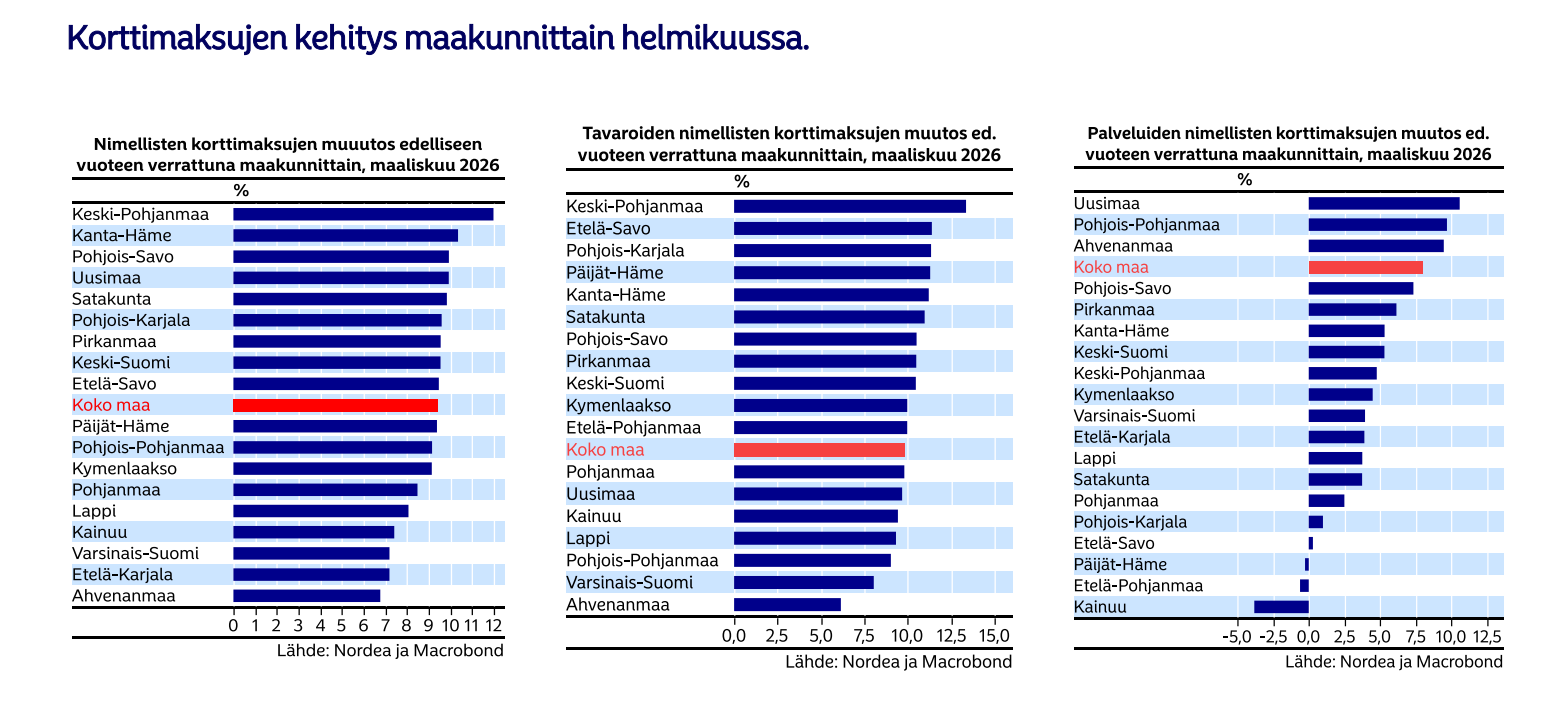
11 Likes
A follow-up to this reflection from late February. Since then, the war in Iran began, which has its own negative impact on consumers, though it apparently hasn’t shown up much in consumer behavior yet (card data). As a couple of positive micro-drivers, it should be noted that the weather was favorable in March/April (terrace seasons open) and Ilves and Tappara advanced to the semifinals. There is currently a local derby series underway at the Arena, and the house has been quite full, especially for Ilves’ games. I still believe that in H1 in Finland, NoHo has a good chance to perform more strongly than in the comparison period.
12 Likes
Tuore Nordean laatima Q1-ennakko, jossa laskevat ennusteita ja nostavat osakkeen käyvän arvon haarukkaa:
Ahead of NoHo’s Q1 2026 report, due on 5 May, we lower our estimates
slightly to reflect the ongoing sluggish market development and more
cautious consumer sentiment. While we still expect the operational
challenges in Norway to be resolved by H2 and the Finnish operations to
maintain a stable profitability level, we argue that any further deterioration in
demand may risk overall margin resilience. Yet we see upside from successful
M&A, new openings and the geographical expansion of Better Burger Society.
We derive a higher fair value range of EUR 9.4-12.0 (8.9-11.5) by equally
weighing our DCF- and multiples-based valuation methods.
Poimintana sieltä myös muiden maiden korttidata ravintoloiden osalta:
Based on Nordea card data, the restaurant market in the Nordics has continued to
grow in the early months of 2026, albeit at a slightly more moderate pace. In
Finland, nominal growth was 0.9% y/y on average in Q1 (Q4: 1.5%), while real
growth was -1.7% (Q4: -0.8%). In Denmark, nominal growth was 1.0% (Q4: 4.7%)
and real growth was -1.5% (Q4: 2.1%). In Norway, nominal card spending was up
by 5.2% y/y in Q1, on average. For Q1, we model NoHo’s sales rising 7.3% y/y, of
which 6.6% is from the impact of the Jungle Juice Bar and Halifax Burgers
acquisitions. We expect Denmark to continue on a solid track, while the
challenges in Norway and the sluggish market in Finland are weighing on nearterm development. For Q1, we pencil in an EBIT margin of 6.5%, down 40bp y/y.
Our estimates are 3% below post-Q4 Vara Research consensus on the top line
and 2% below on EBIT.
16 Likes