Joni has prepared a company report on Netum after Q3. 
We reiterate our Reduce recommendation for Netum’s stock and lower the target price to 1.25 euros (previously 1.4 €), reflecting changes in forecasts. Q3 was softer than our expectations. Unfortunately, there is no significant positive turnaround in sight in the market, which makes crucial new sales challenging. The continuous decline in revenue threatens to diminish the effectiveness of efficiency measures, and there is clear uncertainty regarding the timing and magnitude of the earnings turnaround. In our view, the stock is correctly priced (2025-26e EV/EBITA ~9.5x).
Since no other comments are seen or heard, I must state that Netum’s performance is quite regrettable. It is, of course, difficult for all IT service companies, but here it has come crashing down.
Hopefully, a turnaround can be achieved soon.
4 Likes
Here are Antti’s comments as Netum begins change negotiations.
Netum announced on Monday that it is initiating change negotiations in its subsidiary Netum Oy (Netum Solutions business area). The goal of the negotiations is to adjust personnel costs to match the current level of the 2026 order backlog, targeting savings of approximately EUR 1 million for 2026. The news did not come as a major surprise given the company’s previous comments on the market situation, but it reinforces our view of a challenging operating environment next year, especially in the public sector. We will review our forecasts for the company at the latest in connection with the publication of Netum’s Q4 report.
2 Likes
Joni has prepared a pre-earnings report on Netum, which will release its Q4 results on Tuesday, March 10.
The IT services market has remained difficult in Q4. We expect the company’s revenue decline to have continued strongly at the end of the year as a result of a decrease in the workload of large projects and cost-saving pressures in the public sector. We estimate that profitability remained at a low level, weighed down by weak utilization rates. The company conducted new change negotiations (muutosneuvottelut) at the beginning of the year, which reflects the fact that the market situation has remained challenging, and because of this, we have slightly lowered our forecasts. We estimate that the company will guide for revenue to continue declining in the current year, but there is uncertainty regarding profitability guidance, as well as the potential dividend. We are following signs of a potential earnings turnaround with interest. The valuation profile of the stock is relatively neutral considering the earnings potential and the uncertainty of a turnaround. We reiterate our Reduce recommendation and lower the target price to 1.1 euros (prev. €1.25).
1 Like
Here are Joni’s quick comments on Netum’s Q4 results.
Netum released its financial statement this morning, which was largely in line with our expectations. Revenue decreased significantly as predicted, driven by the completion of large projects. Profitability was weak, driven by the decline in revenue. The company carried out new change negotiations again early in the year, which reflects the difficulty of the situation and supports profitability this year. However, it was positive that sales picked up at the end of the year, which is important to see continue. The company’s guidance was also well in line with our estimates, so we do not see a major need for changes to our forecasts.
2 Likes
CEO Repe Harmanen was interviewed by Joni regarding Q4
Topics:
00:00 Introduction
00:11 ”Year of transformation”
01:30 Impact of completed projects
03:17 Sales outlook
05:34 Cost savings
07:53 Steps for the future
09:59 Guidance and key assumptions
1 Like
Joni has written a new company report on Netum following the Q4 release
We reiterate our Reduce recommendation and EUR 1.1 target price for the share. Overall, the Q4 report was well in line with our expectations. Revenue is weighed down by large completed projects that have not yet been replaced despite good sales. Last year, Netum implemented several changes to adjust its structure and lay the foundation for profitable growth. However, there is still uncertainty regarding the timing and trajectory of the earnings turnaround, although the sales situation appears more positive. Thus, the risk-reward ratio of the share does not quite encourage jumping on board just yet (2026-27e EV/EBITA and P/E are ~11-9x).
Quote from the report:
Netum commented that sales went well at the end of the year and in early 2026. In Q4, the company won more contracts than in H1’25 combined, which is naturally positive. However, based on our understanding, this will not be enough to turn things back to growth as early as H1’26. Thus, it remains critical for the company to continue succeeding in sales to break the revenue decline and get back on a growth path. The company commented that its pricing and ability to win deals improved significantly towards the end of the year. This is because the company has adapted to the market situation and compromised on its previously high margin levels, which has then facilitated the pick-up in sales.
3 Likes
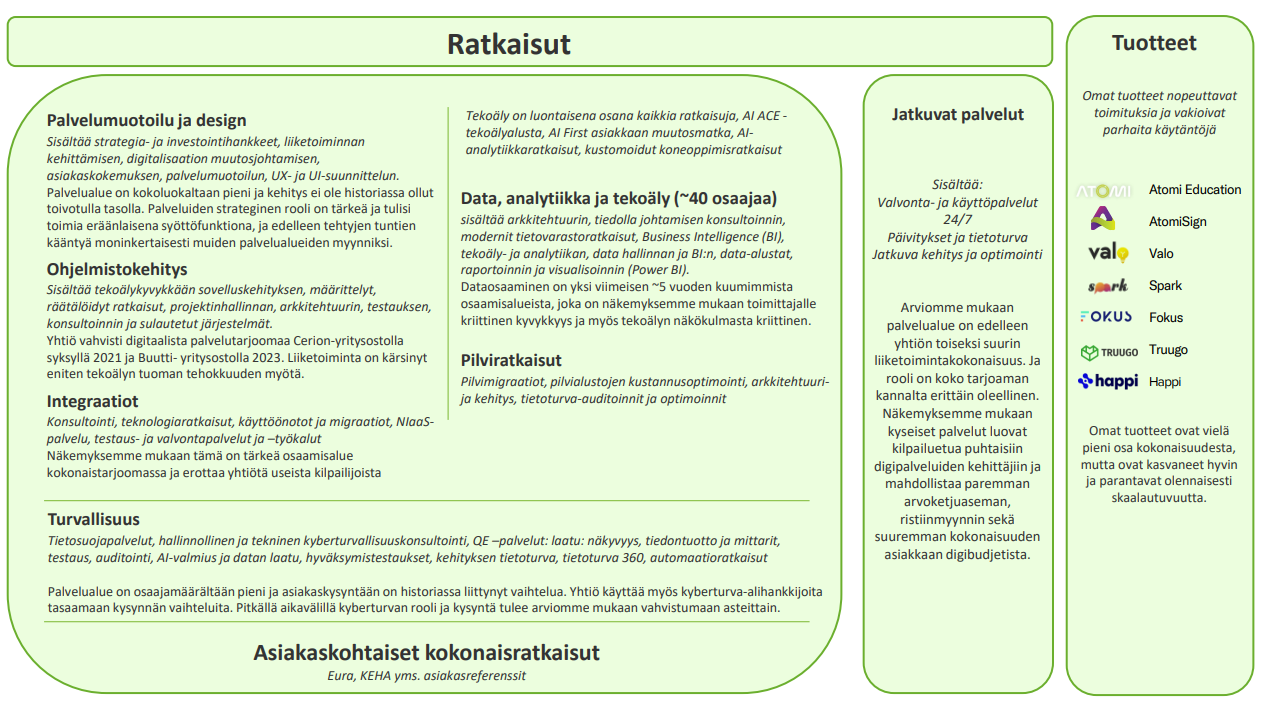
Joni has been working diligently and has prepared a comprehensive report on Netum. Like other extensive reports, this one is freely accessible to everyone. This report also includes a good industry overview, so even if you’re not specifically interested in Netum, it’s worth a look for the industry overview alone.
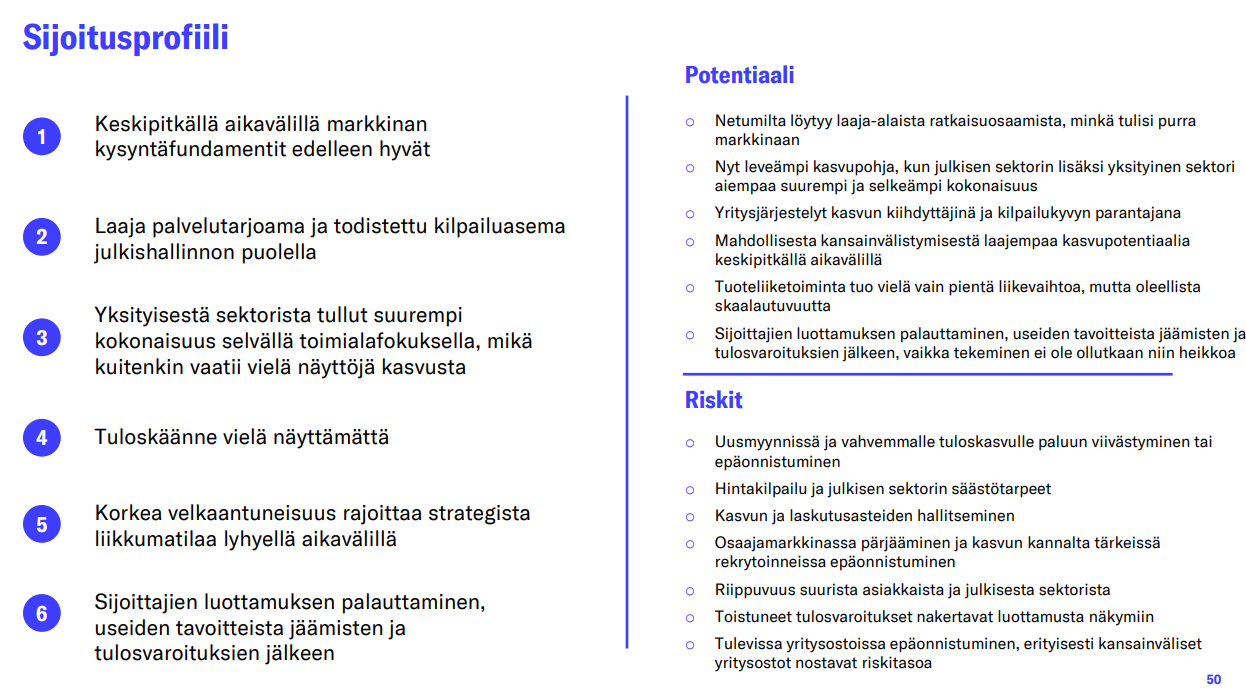
Netum is an IT service company focused on the domestic market with a broad service offering. Historically, Netum’s organic growth and profitability were sector-leading, but recent years have been challenging, albeit better than the sector average. Last year, Netum implemented several changes to adapt its structure and lay the groundwork for a return to profitable growth. This year, we expect the company to lag behind the sector, but to return to that level in the coming years. There is still uncertainty regarding the timing and slope of the earnings turnaround, even though the sales situation appears more positive. Thus, the stock’s risk-reward ratio does not yet quite encourage jumping in (2026-27e EV/EBITA and P/E are ~11-9x). We reiterate our Reduce recommendation and a target price of 1.1 euros.
Quoted from the report:
In our view, the short-term valuation of the stock is driven by organic revenue development and profitability improvement, which are currently on a weak trend. In the long term, value is more strongly driven by organic growth, but a return to historical profitability levels is unlikely due to changes in market conditions.
2 Likes
@Joni_Gronqvist and @Iikka_Numminen discussed Netum based on the recent comprehensive report
Topics:
00:00 Introduction
00:18 Why the share has fallen over 80%
00:59 Netum is smaller than its peers
02:30 Current earnings performance
03:46 Acquisitions
06:00 Forecasts
09:02 Ample debt
10:14 Recommendation
3 Likes
CEO’s review from last week’s Annual General Meeting! 
4 Likes
Here are Joni’s comments on Netum’s recent acquisition
Netum announced on Tuesday that it is acquiring the small cybersecurity company Cyberwatch Oy. We consider the acquisition a strategically logical step that strengthens Netum’s offering in the growing cybersecurity market and brings new specialized expertise to the group. The deal has a slight positive impact on our forecasts, but it does not significantly change the big picture of the company or its challenging market situation. The company did not fully disclose the purchase price, which makes it difficult for us to comment on the final valuation of the deal.
1 Like
Here are Joni’s pre-result comments as Netum reports its Q1 results on Tuesday, April 28th
In our view, there were positive signals in the IT services market in Q4 for the first time in a while, and Netum’s sales have also progressed well in the early part of the year. However, we expect the company’s revenue to have decreased significantly from the comparison period as a result of the decrease in the workload of large projects. We estimate that profitability remained at a low level due to weak utilization rates, although the efficiency measures implemented in the early part of the year are gradually beginning to support the cost structure. We are following comments on sales and the state of the IT services market. In March, we published an extensive report on the company, which remains very timely and can be read here.
Netum’s results from this morning
2 Likes
Joni interviewed Netum’s CEO Repe Harmanen after the Q1 results release
Topics:
00:00 Intro
00:26 Development in the early part of the year
03:32 Sales development and project timing
07:05 Pricing
10:33 Acquisition of Cyberwatch Oy
13:53 Increased demand for cybersecurity
17:12 Strategy work
2 Likes
Here is the company report on Netum from Joni right after Q1
We reiterate our Reduce rating for the stock and lower our target price to EUR 1.05 (prev. EUR 1.10). In the big picture, the Q1 report was slightly softer than our expectations, although profitability was a good defensive victory. Looking ahead, the direction is correct, driven by sales, but there is still clear uncertainty regarding the timing of sales and its impact on revenue and profitability. Furthermore, the valuation is stretched and does not yet encourage jumping on board (2026-27e EV/EBITA and P/E are ~13-11x).
1 Like
Netum’s Repe Harmanen was at the IT Services Night to talk about the company as an investment.

Topics:
(00:00) Introduction (00:27) Netum in brief (04:14) Q1’26 (06:45) Cyberwatch becomes part of Netum (08:36) Strategic focus areas (09:54) Strategy work (10:50) Internationalization perspectives (11:55) AI built into operations (14:20) Q&A
1 Like
Profit warning incoming
Previous outlook for 2026
Netum estimated that revenue would decrease from the previous year’s level (2025: EUR 37.8 million) and that comparable EBITA would remain at the previous year’s level (2025: 5.5%).
New outlook for 2026
Netum estimates that revenue will decrease significantly (2025: EUR 37.8 million) and that the comparable EBITA margin will fall below the previous year’s level (2025: 5.5%).
5 Likes
Here are Joni’s comments on Netum’s profit warning.
Netum published a profit warning on Wednesday, where the company lowered its 2026 guidance regarding both revenue and profitability. The warning did not come as a complete surprise to us, as we had already highlighted a clear risk of a downward revision in profitability guidance in connection with the Q1 report, due to the challenging market situation and intense price competition. The profit warning confirms our view that there is no rush to buy the stock yet. The release creates slight downward pressure on our forecasts, and we will update the figures at the latest in our results preview.
2 Likes
Netum has won the City of Järvenpää’s tender for the delivery of integration services. The object of the procurement is an expert team for the City of Järvenpää’s centralized integration platform. The expert team will provide development, support, and maintenance services.
The request for proposal was based on the dynamic purchasing system (DPS) “IT Consulting 2023–2028” established by Hansel Ltd. The contract period is five (5) years, in addition to which the procurement includes an option for one extension of up to three (3) years. The total value of the procurement is approximately EUR 1.6 million. The contract becomes legally binding after it has been signed.
3 Likes
Here is the pre-earnings report from Joni for when Netum reports its Q2 results next Tuesday.
The company issued a profit warning in June, which confirmed that the second quarter was as difficult as expected. We expect revenue to have fallen significantly compared to the comparison period, as large projects ended and new projects started up slowly. We estimate that profitability remained reasonable relative to the decline in revenue, thanks to previous efficiency measures, but it still reflects the demanding market situation. The main focus of the report will be on the outlook for the rest of the year, the development of the sales pipeline, and when the decline in revenue will finally be reversed. We are lowering the target price to 1.00 euro (prev. 1.05 €), reflecting forecast changes, and reiterate our “reduce” recommendation for the stock.
3 Likes