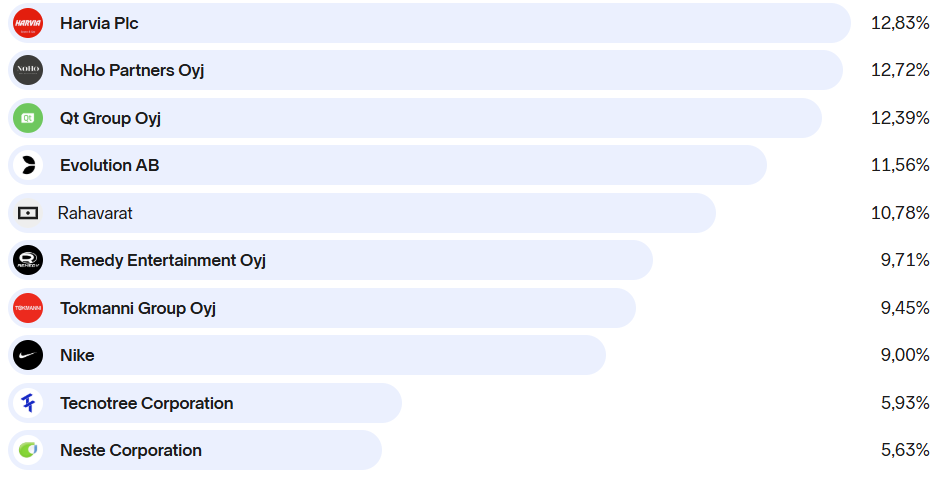
What do you have in your portfolio?

For my part, this is the first broader portfolio opening. Currently, a new investment plan-based asset allocation is actively underway, which has caused significant changes to the portfolio’s content recently. I have read all the messages in this thread over the years, so I thought it might be time to open my own portfolio as well.

Mainly, I have been looking for stable performers, seasoning the ownership slightly with risk investments.

Holdings, real estate, and listed companies, owner-occupied housing not included:
Forestry property 10.85%
Pepsico Inc 7.32%
Nestle 5.88%
SJW Group 5.64%
Nokia Corp 5.33%
Fortum 4.61%
TietoEvry 4.43%
Elisa 2.59%
Glaxo Smith Kline 2.46%
Nokian renkaat 2.45%
LyondellBasell Industries 2.45%
Lockheed Martin Corp 2.06%
Canadian National Railway 1.88%
Campbell’s Co 1.74%
Bioretec 1.61%
Anora 1.49%
Deutsche Post 1.18%
Olvi 1.15%
Neste 1.10%
Sonoco Products Co 1.09%
Fiskars 0.96%
Intel Corp 0.68%
Cash 31.06%

The apartment still plays a significantly large part in where the money is tied up; hopefully, its share will decrease in the future. The apartment’s share currently exceeds the value of other invested assets, even when calculated conservatively in my own accounting.

20 Likes
Dividend Kings and Aristocrats: %
PepsiCo Inc 7.92 % Growing steady dividend. My first stock purchase! (+upm)
Aflac Inc 7.55 % Growing steady dividend.
Genuine Parts Co 4.14 % Growing steady dividend.
Coca-Cola Co 5.04 % Growing steady dividend.
McDonald’s Corp 4.77 % Growing steady dividend.
McCormick & Co Inc Registered Shs Non… 3.58 % Growing steady dividend.
American Water Works Co Inc 0.35 % Purchases on hold at least temporarily. Not really an aristocrat yet.
Dividends: %
Omega Healthcare Investors Inc 16.68 % High dividend! Overweight.
Main Street Capital Corp 15.94 % Monthly dividend stream. Slightly overweight.
Horizon Technology Finance Corp 5.96 % Monthly dividend stream. Purchases temporarily on hold.
ALPS O’Shares US Quality Div ETF 3.62 % Monthly dividend stream, restrictions prevent replenishment.
Verizon communications ord shs 1.26 % Newest acquisition! Dividends for desired months.
Shell PLC 1.38 % Dividends and excellent future direction.
Miscellaneous / Finland %
UPM-Kymmene Oyj 6.61 % UPM products are used, good dividend. My first stock purchase! (+pepsi)
Kesko Oyj Class A 2.84 % Kesko products are used. Dividend multiple times a year.
Ålandsbanken ABP Class B 2.67 % Ålandsbanken’s services are used, good dividend.
Fiskars Oyj 1.93 % Fiskars products are used. Dividend multiple times a year.
Apetit Oyj 1.31 % I use Apetit’s products. Dividend is also good.
Futebol Clube do Porto - Futebol SAD 0.16 % I follow the team. No dividends and rare purchases.
Non-dividend paying funds: %
OP-Nordic Index A 1.57 % Small monthly savings + occasional purchases.
OP-World Index A 1.81 % Small monthly savings + occasional purchases.
iShares MSCI EM SRI ETF USD Acc EUR 1.17 % In my mind, diversification to the Middle East and elsewhere. Limited purchases after the 1% offer expired.
OP-Asia Index A 1.17 % Small monthly savings + occasional purchases.
OP-Europe Index A 0.43 % Small monthly savings + occasional purchases.
OP-High Yield A (D) 0.12 % Occasional purchases.

Additionally, I own one fan club outside of stocks and those S-Group cooperative shares.
If cash is considered, it accounts for approx. 0.5% of the portfolio value. A slight decrease in cash from the previous. The above percentages are relative to others, excluding cash..
A couple of potential dividend aristocrats and one unlikely IPO are being monitored. I might participate in the IPO if it happens. I don’t know about the monitored ones yet. For now, I’ll just continue buying the current ones. This is starting to be the maximum amount I can keep track of.
Overweight positions are not sold but balanced with other purchases in the long term.

23 Likes

The new year turned quite a while ago already, and I’ve had to battle my inner “personal trainer” just to churn out some kind of scribble on how the 13.5 months since my last portfolio update have gone. I’ve tried to stick to my dividend strategy, seasoned with swinging partial positions. That has actually been surprisingly easy: even though I’ve occasionally grit my teeth and sold very cheaply, pretty much without exception I’ve been able to buy the same shares back into the portfolio a little later even cheaper—the atmosphere has felt like Tokmanni’s bargain days :slight_smile: I’ve tried to dodge falling knives, though not always with success. On the other hand, I’ve mostly picked knives where I believe there is upside once the cycle turns, meaning the FIFO principle works beautifully and the cheapest purchases remain in the portfolio. Naturally, my default stance is not to sell anything, but hopefully having learned from the crazy year of 2021, defining some sort of fundamental-detachment-exit-target-price (what a compound word, language police feel free to check the validity :slight_smile: ) for the holdings is probably wise going forward. Running a 100% Finland portfolio here, with no real desire for geographic diversification, although someone might argue there’s a need for it :slight_smile: . The percentage weights of the holdings reflect yesterday’s situation, 14.2.25. Once again, I’ll save the returns for the very end of the rhyme, so if someone manages to read that far, they’ll notice that the last three years have been quite a trek through the wilderness for me as well; returns have been hard to come by. My apologies in advance if some of my company-specific comments feel slapped together; I set myself a deadline to get this done so I could go enjoy the fresh outdoor air :slight_smile:

TietoEvry 11.36%, the eternal crawler has stealthily (just yesterday) taken the top spot as the largest holding in my portfolio. We shouldn’t have to wait long now to get rid of the unprofitable and ill-fitting Tech Services business—that is, if the company itself is to be believed, the end of March should be the deadline. They tried to sell the Banking business too, but luckily market conditions were not favorable for a deal; in my opinion, it’s a real sweet spot, and I never understood why they tried to sell it in the first place. Constant adjustments and non-recurring items make evaluating the big picture tricky, but that’s why we have analysts—my own capacity isn’t enough for that. However, the dividend history speaks for itself; the trajectory has been upward, barring the difficult COVID year of 2020. Cash flow is being generated, and for an owner, that is what matters most.

Anora 10.92%, I call this a counter-cyclical stock among my circle of friends, referring mostly to my eight years of sobriety :slight_smile: . These so-called sin stocks don’t get much attention from the financial media, nor has any celebrity investor admitted to owning it—except, rather unsurprisingly, Heikki Savolainen (Weststar Oy), who made his fortune in payday loans. Alcohol consumption is declining globally, which is of course a good thing. In my view, however, the decline in consumption doesn’t have the same slope as the downward slide of Anora’s share price. The failed Globus Wine acquisition carried out during Tennilä’s tenure has eaten into earnings and weakened competitive positioning; perhaps some sort of business insurance compensation will eventually come through. Still, the market prices the stock as if better times will never be in sight. At the latest, the end of the war in Ukraine will open the taps and consumer confidence will strengthen, leading to rising volumes for Anora’s products as well. Owning this requires nothing more than patience, which some investors simply do not possess. I don’t expect this to return to the €10 levels of yesteryear, and the IPO price of €7.60 will be an uphill battle, but if the board pulls off a successful CEO recruitment, the prerequisites for improvement are there. Price increases have been pushed through, and barley prices are no longer through the roof either; of course, this is a volume business after all.

Nordea 10.49%, This has been a joy to own during Frank Vang-Jensen’s tenure as CEO. The company has been trimmed into fantastic shape, and capital distribution to shareholders via dividends and share buybacks is flowing copiously. The best bank in the Nordics, and perhaps in all of Europe. Net interest income is naturally declining, but at the same time the economic cycle is potentially turning, and lending activities as well as investment returns are picking up. The share price won’t rise much anymore, of course, because suspicion towards the entire banking sector remains permanently elevated—and not without reason: the news coming out of the major eurozone countries hasn’t been particularly positive, and banks will definitely take a hit if Eurocrisis 2.0 materializes.

Tokmanni 9.93%, no longer even makes the podium in terms of position size, whereas it once accounted for up to 40% of my portfolio. I had to face reality and take matters into my own hands, realizing that my entire portfolio was bouncing around like a jack-in-the-box along with the discount retailer’s share price. What is inherently a defensive stock has in recent years been heavily at the mercy of the market, with the price swinging from manic heights to deep depression. One wonders if management’s communication could use improvement; after all, earnings have chugged along quite steadily in recent years, and dividends have been generous. I eagerly await Dollarstore being tuned to its full potential in Sweden (Denmark), and I’m keeping an eye on the first steps of the Spar partnership in Finland. Tokmanni’s revenue has ballooned like yeast dough in recent years, but profitability has not yet followed suit. I believe this is only a matter of time, however, and my own valuation suggests the stock’s value will be over €20 then. @Arttu_Heikura might still get a chance to outbid Petri Kajaani, say with a Buy at €27.10 :slight_smile:

Fortum 8.84%, as a hedge against the electricity bill and a generous state-owned dividend payer, this holds a self-evident place in my portfolio. After the traumatic Uniper and Russian adventures, we are once again sailing in calmer waters, merely watching electricity price futures—suits me fine :slight_smile: . Massive data centers are making their way to Finland, and electricity consumption will increase before long. Could Fortum still get a chance to make an offer on the attractive Swedish hydro assets owned by Uniper? They would have the contractual right to do so, should those assets come up for sale at all!?

Lassila & Tikanoja 7.96%, my portfolio is full of stocks like this: strong domestic market exposure, and operations that don’t generate much buzz. Eero Hautaniemi & Band have now decided to spin off the real estate services business into its own company, presumably because it didn’t find a buyer. On the other hand, there’s no reason to sell for peanuts, though the Swedish facility management business in particular has certainly been a major headache—will it ever become profitable? Write-downs have already been made. My investment thesis remains intact, however; the whole company might eventually be bought out once the cycle improves. The dividend supports expected returns while waiting, and they have nicely returned to an upward dividend trajectory after cutting the oversized payout a few years ago. I’ve been waiting for a share buyback program here; I’ll have to remind the company about that again. I gladly own this and, for example, Anora, as they are covered by @Rauli_Juva ; that way, I can always pester him with more or less expert comments in the respective company threads. And no worries, if I don’t always have time to comment, there are other stubborn old-timers (+60) like me on the forum :slight_smile:

Nokian Tyres 6.50%, sometimes makes me wonder whether I ventured onto too big of a playground, a bit like with Neste. Through swinging, swinging, and more swinging, I’ve managed to lower my average cost to under €7, so the margin of safety has at least increased somewhat. Then, of course, Morgan Kane’s evil stepbrother J.P. Morgan comes along and slashes the target price to €5.50 :slight_smile: . Go figure; after the catastrophe in Russia, the company has nevertheless moved forward consistently, and production at the new Romanian factory is already ramping up. Subcontracting has ensured the product remains relevant in Central Europe at least. In the US, on the other hand, sales haven’t met expectations, so marketing investments need to be stepped up—and the factory will become invaluable thanks to the “crazy tariff man”. In the Nordics, Nokian has a solid position, but following hits to consumer purchasing power, the average motorist thinks twice about every euro and may temporarily settle for budget-tier tires.

Neste 5.57%, this falling knife is likely all too familiar to many forum members. I personally started buying around the €23 level; in hindsight, perhaps I should have listened to technical analysts. Then again, if you want to build a larger position, buying into declining prices is easier for me from a capital management standpoint. My allocation is usually 100% invested, meaning there is no actual cash reserve; something has to be sold or fresh capital added to the account if I want to go shopping. Besides, buying into rising prices over the past few years hasn’t been terribly rewarding—nor even possible for many stocks :slight_smile: . Admittedly, this is heavily at the mercy of regulation, and given Trump’s rise to power, the future in the US doesn’t look rosy either with domestic markets shamelessly favored. Well, Neste does have production and feedstock sourcing there too, so some cash should clink into the coffers from the States going forward. Even if climate change mitigation efforts suffer temporary setbacks and blending mandates are scaled back, I believe that eventually the momentum and will for change will be too strong; a few fossilized politicians won’t be able to prevent it in the long run. An entirely separate question is whether Neste has lost some of its competitive advantage. Unscheduled plant shutdowns add their own flavor to the soup; one almost gets paranoid wondering if Putin’s henchmen could be behind them!? Extremely difficult to evaluate, and the same goes for analysts, whose forecasts are scattered all over the place. It’s always worth remembering that many sharp price drops stem from overly optimistic analyst projections. It’s wise to draw your own conclusions when a share price trades tens of percent below consensus; the market usually understands the situation better, at least with large-cap stocks. Neste is by no means a screaming buy even at these levels, not until we see signs of improvement. I liked the company’s own London financial statement presentation; perhaps cynical realism is entirely the right approach in this situation, leaving room for positive surprises.

NoHo 4.81%, is slowly starting to deliver on its promises after the freeze of the COVID years. They’ve finally gotten rid of Eezy, which was messing up results, and interesting moves have been made abroad. Aartio’s Pimu Capital has practically completed its exit, so its selling will no longer hold back the share price. NoHo’s AGM in Tampere remains one of my favorites, complete with a tasty breakfast spread and topped off with a restaurant gift card.

Consti 4.43%, has been in my portfolio for a long time, and the price hasn’t moved much over the past four years. Return on capital is excellent, the company is practically debt-free, and dividends are already very generous. I also have strong trust in current management, but tailwinds from the market are needed too; after all, this building market freeze—which has lasted longer than the 1990s depression—is not a good thing even for a defensive renovation contractor, as new-build contractors compete for the same projects.

Raisio 4.03%, a pleasure to own. I consume Raisio’s products daily, and healthy food products have a bright future ahead. Marketing investments in Europe must be increased; perhaps Tokmanni’s Spar partnership could provide opportunities here. The financial statements release noted a recovery in the UK Benecol business after a tough period. Here, too, improving consumer confidence and purchasing power growth will play into the company’s hands, given that the products carry a slight price premium.

Elisa 3.83%, a great holding to have in the portfolio. Some call it a bond proxy, but the 5G business rocks and I believe they will benefit from AI as well. A point of discontinuity is the fresh CEO following Mattila’s long era, and the Chairman of the Board is also stepping down this spring. There’s a lot of talk about M&A, but hopefully they remain prudent and look before they leap.

Enento 3.69%, an extremely interesting company once consumer confidence rebounds and people start applying for loans again. The moat is strong; entering this sector isn’t easy. Rising interest rates were unexpectedly potent poison for Enento, but a declining yield curve will support the share price again, and it seems the bottom is being tested right now. This one could also become a takeover target in the future; keeping an eye on the moves of major owners Otava and Mandatum will be interesting.

Oriola 2.15%, with its current dividend yield, the pharmaceutical distributor is a fairly safe pick for a dividend portfolio—assuming one believes the business can be whipped into better shape and no massive additional write-downs will hit the Swedish pharmacy joint venture. It truly is an unbelievable underperformer, but hope springs eternal :slight_smile:

Remedy 1.85%, a lottery ticket. The fundamentals haven’t changed: the only pure-play game developer on the Helsinki exchange, and I have plenty of great experiences from Case Rovio. Tencent has cornered Remedy and other partnerships exist. I understand nothing about the gaming industry, and so far this investment has just been patronage of gaming art, but this too will (unfortunately) eventually be bought out as part of a larger entity. I don’t recall whether @Atte_Riikola 's current analysis includes a takeover option, but the market certainly disagrees with Atte’s €19 target price. If I recall correctly, Atte mentioned at some point that Remedy’s value could be anywhere between €15 and €40, but along the way that shifted to €6–€40; maybe my memory fails me, or perhaps reality has set in :slight_smile:

Lindex 1.27%, currently at quite a small weight, as I want to monitor developments in peace. I can fairly easily buy back shares I sold higher if the mood strikes. The key question, of course, is whether they can divest the department store division on reasonable terms and focus entirely on Lindex’s highly international core business. Just yesterday, the owner of the Åhléns department store emerged as a prospective buyer; naturally, such news should be taken with a heavy grain of salt, as it could also be a well-calculated publicity stunt to stir up shareholders. The Konstsamfundet and Cloppenburg coalition will undoubtedly have a say as well. As I write this, it’s actually looking increasingly likely that a buyer will be found for the department stores, and a bidding war might even be possible. The cycle will turn eventually, and if peace truly returns to Ukraine, I believe it’s only a matter of time before travel restrictions are lifted and tourists arrive from the east. In any case, the restructuring program continues, but I strongly suspect something is happening behind the scenes.

Spinnova 1.19%, firmly in the lottery ticket section. Here we are eagerly awaiting Suzano’s potential investment decision on a larger-scale production facility; if that fails to materialize—meaning the product cannot be made cost-effective—good advice will be hard to come by. Still, this is a fine Finnish innovation and definitely an investment worth the risk. I haven’t burned my fingers too badly here either; despite being involved for years, my average cost is around €1.20, whereas the IPO price was €7.60.

Almost forgot the cash balance: a regal 1.18%. That illustrates reality quite well: I play this stock game on an all-in basis, trusting that there is always something to sell in the portfolio if an irresistible buying opportunity presents itself in a stock I want. I don’t have the nerves of steel required for leverage.

In 2024, I executed 661 trades (thankfully not 666), slightly fewer than the year before—perhaps age is catching up with me :slight_smile: . I lost to the OMXHGI benchmark index by a couple of percentage points last year, around -2%. At worst, I think I was down -10% in November, largely thanks to Tokmanni’s extreme swings. The trailing 12-month return stands at +7.29%, 3-year return at +12.98%, and 5-year return at +89.21%, so I’m by no means throwing in the towel, even if last year was particularly tough. Spring dividends are simply far too tempting for me to even consider switching to index investing. As a silver lining on the cloud, 24.2 is approaching—marking the three-year anniversary of Russia’s invasion of Ukraine; I suspect that for many, the three-year return figures will shift considerably in a positive direction.

Interest rates continue their descent in Europe toward the magical two percent mark, which will bode well for consumer purchasing power. My worst fear in my portfolio report just over a year ago was Trump being elected president, and that came to pass. I do my best to filter out everything that spews from his mouth, letting it go in one ear and out the other. I am worried about US democracy; this Trump-Vance-Musk axis will certainly be quite a test for it. A narcissist and a (convicted) felon can certainly get a lot done in four years; the chickens will come home to roost when it’s time for the tariff man to step down four years from now.

As for geopolitics, there will in all likelihood be at least a ceasefire in Ukraine this year. I wait with concern to see on what terms, although peace is obviously the goal to strive for. Reconstruction will provide a boost to the European economy, and consumer confidence will also improve with potential peace. The situation in the Middle East remains explosive—well, it has been since long before I was born. China’s intentions regarding Taiwan have received little attention lately; hopefully that won’t become the world’s next flashpoint. All in all, even with the looming threats, I expect this to be a better investment year than its predecessors. Wishing all forum members a great continuation of the investing year :slight_smile:

95 Likes

Faron Pharmaceuticals ~50 %
Optomed ~25 %
Exel Composites ~15 %

And ~10% trading cash, which is currently tied up in Intel’s weekly push.

As Warren Buffett has said, why would you put money into your 30th best idea :grin:

Here we go with an all-or-nothing mentality. I’m still following Exel, but if/when Optomed’s sales start to take hold, I’ll increase that position at Exel’s expense.

And this portfolio is not investment advice :joy:

34 Likes

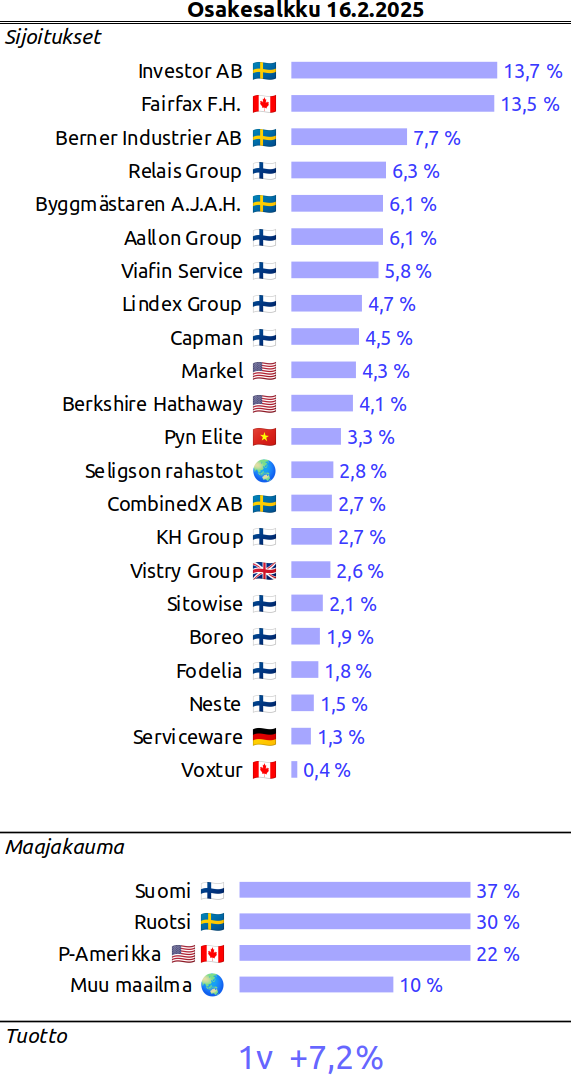
Portfolio Review 24H2: poor investment picks ate into the year’s returns, but a little light is also visible at the end of the tunnel

In the latter half of the year, I traded very little. The only transactions were the November sale of Embracer from the portfolio. With the money, I bought 8 more shares of Fairfax.

The stock portfolio’s 2024 return remained at -0.2%. The portfolio was particularly hit by Vistry Group’s profit warnings at the end of the year. Many other companies also reported soft figures in 24Q3, so the end of the year was truly subdued. Now that many companies have already reported their Q4 results, I am pleased with several better-than-expected reports. Aallon Group, Relais, CombinedX, Berner, and Capman all reported at least satisfactory results. Boreo clearly exceeded Inderes’ analyst expectations, which indicates that light may be starting to appear at the end of the tunnel. Of course, Neste and Sitowise still delivered disappointments. Not all portfolio companies have reported their Q4 yet, but so far, the earnings season has been at least hopeful overall.

Fairfax’s and Markel’s insurance businesses developed favorably for both in Q4. By the way, I found an interesting discussion forum that discusses Fairfax and Berkshire. The level of discussion seems, at least at first glance, high-quality and thorough. I need to examine it more closely over time. The link to the discussions is https://thecobf.com/forum/

No new stock picks are currently planned. Several picks from last year led to poor results when the company’s business risks materialized. I need to learn from that. Investment companies have developed well, so I intend to continue investing in them. Boredom and consistency are often good. I don’t sell shares very easily, even though it often would have been profitable when the business starts to falter for one reason or another. Perseverance is a good trait in many respects, but if an investment story starts to erode, it might be good to react quickly. This is one thing I need to ponder a bit in my own process.

The recovery of construction would help at least Boreo, Sitowise, and KH-Group. For these, I intend to stubbornly wait for the economy to improve. The waiting time is long, so we’ll see in which year such a thing will materialize.

The portfolio’s 1-year rolling return is +7.2%.
image

34 Likes

I have something similar, meaning high risk for big returns.

Nexstim 65%
Optomed 35%

8 Likes

My portfolio is currently heavily weighted towards dividends and Finland. Below are the holdings in descending order of size:

Sampo
Fortum
Nordea
Elisa
Relais Group
Kesko A
Outokumpu

In addition to these, I have forest investments and some cash. The portfolio hasn’t looked like this for a long time, but currently the investments seem promising and appear to be steadily rising day after day. Although many would probably recommend diversification into other countries as well, I have decided to first grow my OST account to the one hundred thousand euro limit and invest the funds in Finnish dividend stocks. Once the limit is met, I intend to start diversifying investments elsewhere as well.

31 Likes

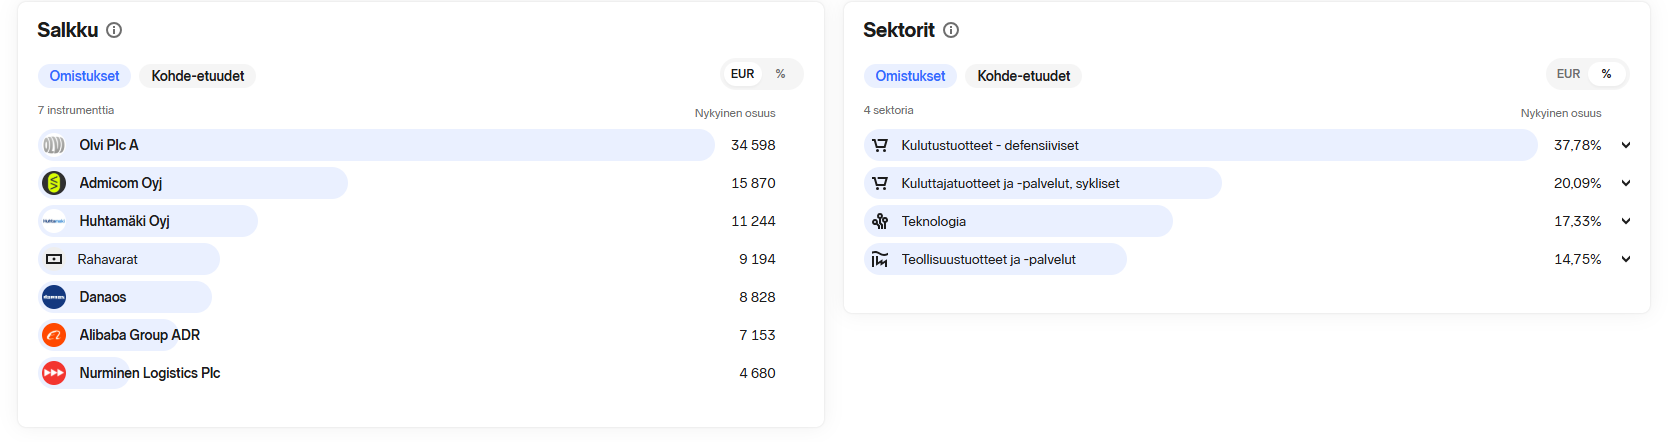
image
A small update to a post from almost a year ago.

Sprouts left the portfolio after a tremendous rise (the desire to own it again is great), and Gofore, which left the portfolio pretty much at +/- zero. Olvi has apparently been added more than others. About a month ago, BABA returned to the portfolio, which I already managed to trim a bit, and then Danaos is completely new in the portfolio.

In addition, during the year, some funds have been liquidated from the portfolio for kitchen and other renovations.

13 Likes

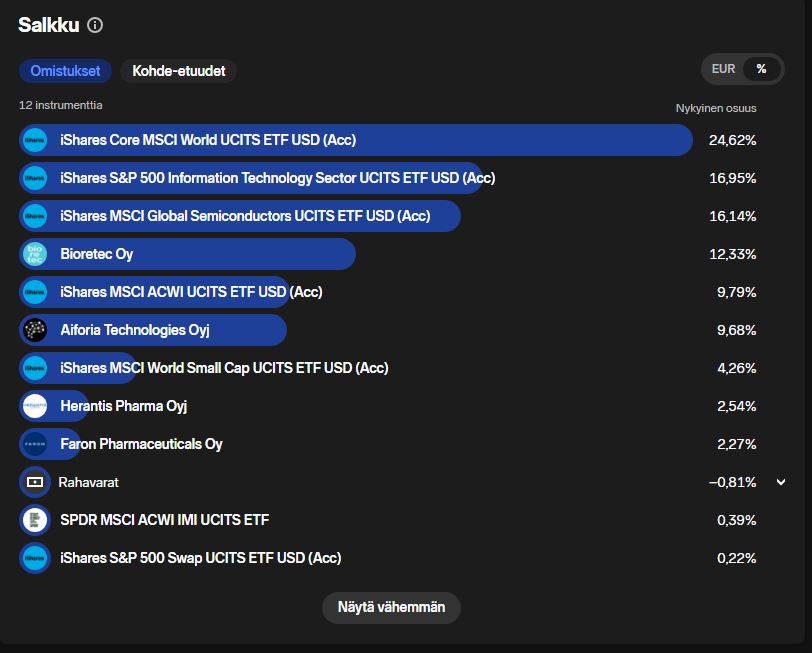
Let’s put my own portfolio on display.
Investing started in 2016, and in the early days, there were many purchases and sales of individual stocks. At the same time (fortunately), monthly savings into an index fund were running in the background. These stock picks did not result in significant monetary gains or losses.

The best success was buying large lump sums of iShares S&P 500 Information Technology Sector ETF in 2020. These are already up by about 130%. It’s a pity that at the time of purchase, I owned Visa and Mastercard, but they have since been moved to a different sector. They would have provided good diversification for the current situation.

Current Investment Plan:
Monthly savings into global ETF funds and tracking and holding selected stocks. No more additional purchases; sales only if the underlying story changes. The purpose of these is to increase the portfolio’s annual return in the coming years, which is why risky stocks have been selected. If the shit hits the fan and prices drop significantly, we’ll lick our wounds and continue monthly savings into the index.

Bioretec and Aiforia are the stocks that I believe have the potential to multiply their value. I have studied these and made purchases over the past couple of years. For both, 2025 and 2026 will be big years – either up or down.

Bioretec:
Bioretec’s screws have been proven functional and safe, and the CE marking, FDA approval, and patents have already significantly reduced the risk. The RemeOs product family has a significant moat and earnings potential for the coming years, if product development succeeds and sales permits are obtained for new products.

Aiforia:
Aiforia’s progress has been slow so far, but the hope is that hospitals will start getting their systems in order this year. Major clients have already been won in Europe, but it has been quiet in the United States after Mayo. The market is new, and the winners are not yet clear.

Herantis and Faron are purely lottery tickets. These have only been superficially examined.

omistukset

30 Likes

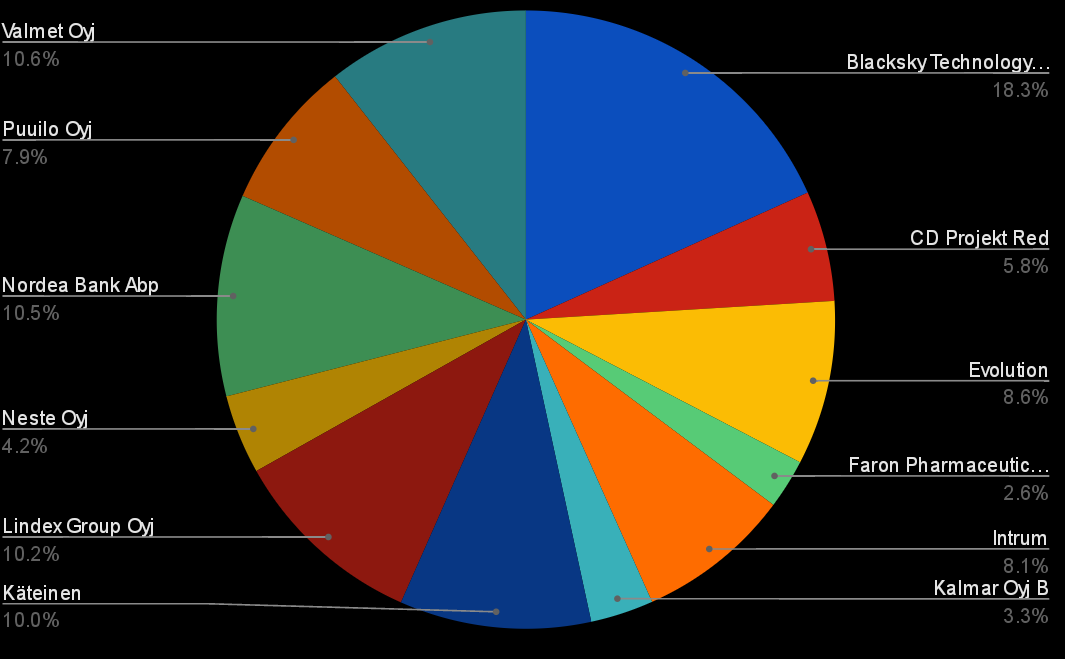
Here’s a fresh picture of the portfolio. The pie chart got a bit mixed up, but I’m losing my patience fiddling with it on my phone, so let it be.

Screenshot_20250219-120543

The weight is unfortunately largely in Finland. Luckily, the large Blacksky and growing EVO and Intrum positions balance things out a bit. I’ve promised to put new money into funds, but lately there hasn’t been any extra to invest. I now have more cash than usual from (loss-making) stock sales, but I think I’ll invest it in apartment renovations/ground/air-to-water heat pump.

17 Likes

IMG_8387

Today, the portfolio has been rebalanced a bit due to some recent ups and downs. Neste and Metso positions are now completely out of the portfolio. Good gains from Metso, but unfortunately Neste largely offsets that. Elisa, Raisio, and Remedy were added to the portfolio as new holdings. Also increased ETF weighting a bit to get some global diversification.

15 Likes

The portfolio has undergone quite a shake-up over the past three months, even though I was rambling about better consideration at some point, etc.

  • For AOT, where, in addition to ETFs, Investor and Realty Income are added steadily from salaries, and we try to keep it as a solid foundation.
  • For OST, risk has been added, and the portfolio, which mainly consisted of safe Finnish stocks, has been switched to riskier alternatives, but with fairly modest stakes and diversified around the globe.
Name %
VanEck Crypto and Blockchain Innovators UCITS ETF USD A 12 %
iShares Core MSCI World UCITS ETF USD (Acc) 12 %
Investor B 8 %
Amundi Nasdaq 100 II UCITS ETF Acc 7 %
iShares Core MSCI EM IMI UCITS ETF USD Acc 7 %
Hims & Hers Health Inc A 6 %
Realty Income Corp 6 %
Novo Nordisk B 5 %
Evolution 5 %
Nordea Bank Abp 4 %
VanEck Defense UCITS ETF USD A 4 %
Nu Holdings Ltd A 3 %
Sampo Oyj A 3 %
Aiforia Technologies Oyj 3 %
Zaptec 3 %
Mercadolibre Inc 3 %
Optomed Oyj 3 %
Faron Pharmaceuticals Oy 3 %
Alibaba Group Holding 3 %
27 Likes

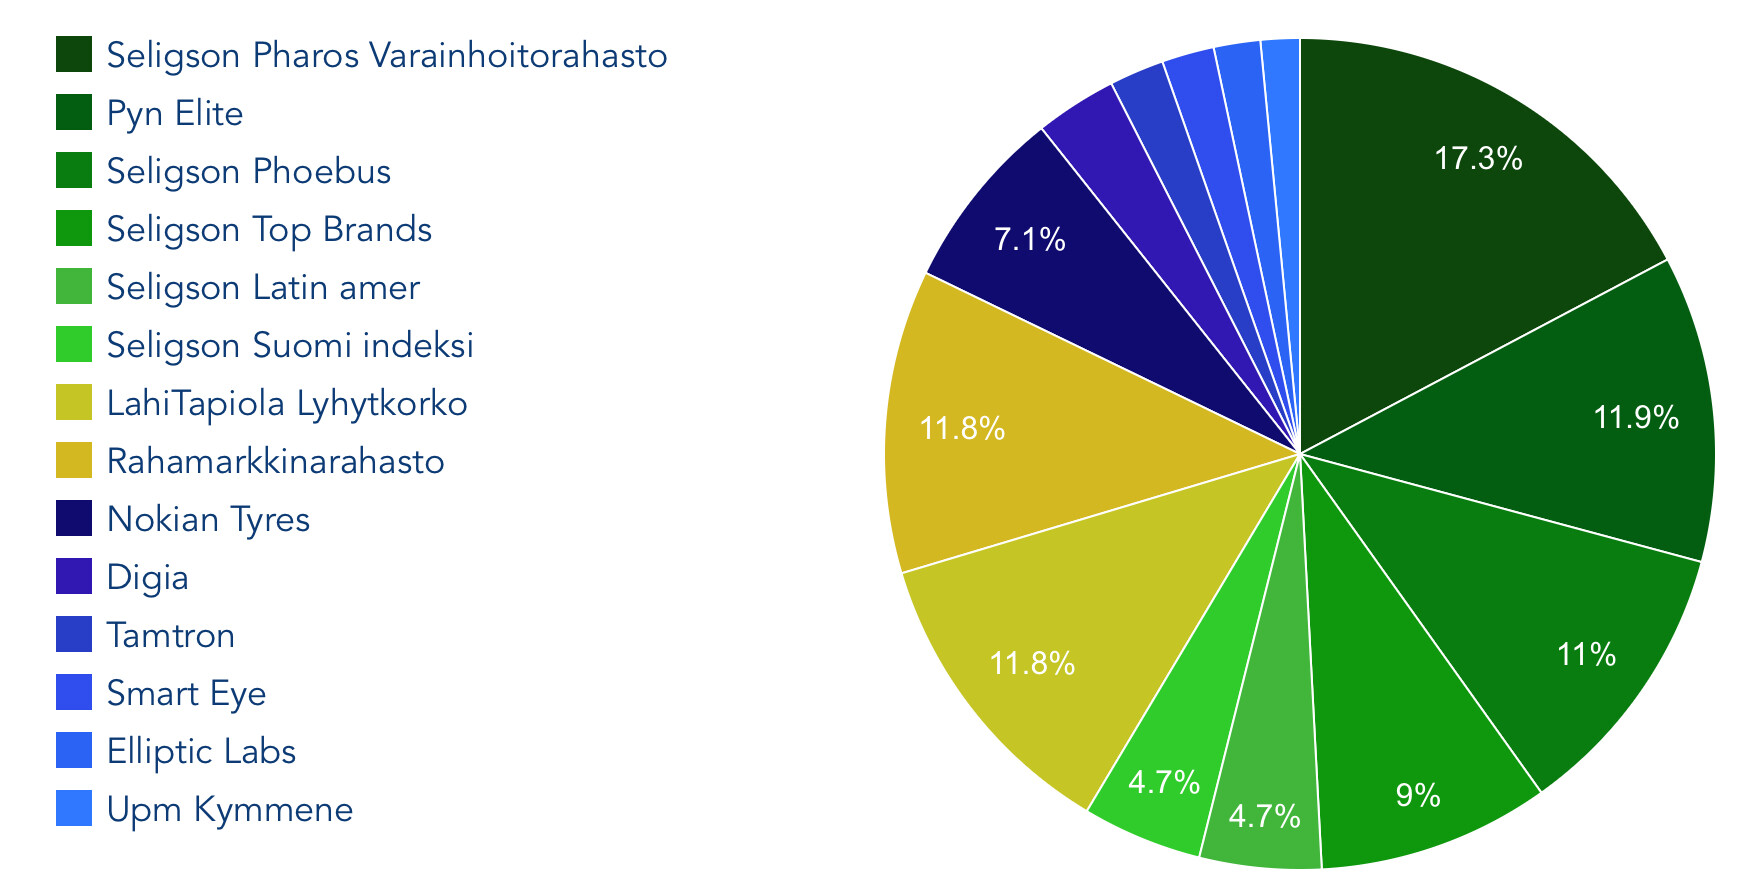
Each stock is just visiting the portfolio (bottom fishing practiced). Some of them are held for years, some for a shorter time. They are released when the investment idea is fulfilled. Then the released funds are transferred to a fund/ETF.

The 4 largest funds form the growing cornerstone of the portfolio (weight now 49%), which is and remains.
Cash-like interest-bearing investments are waiting for a time when there is a desire to invest them into funds or a new stock idea is found.

Funds in green
Stocks in blue

IMG_4376

I would like to own some stocks long-term, but I haven’t yet found an attractive enough entry point for them. Hermes, Investor, etc.
The price just needs to be attractive enough, so I’ll probably have to wait for a proper market crash before that wish comes true.

18 Likes

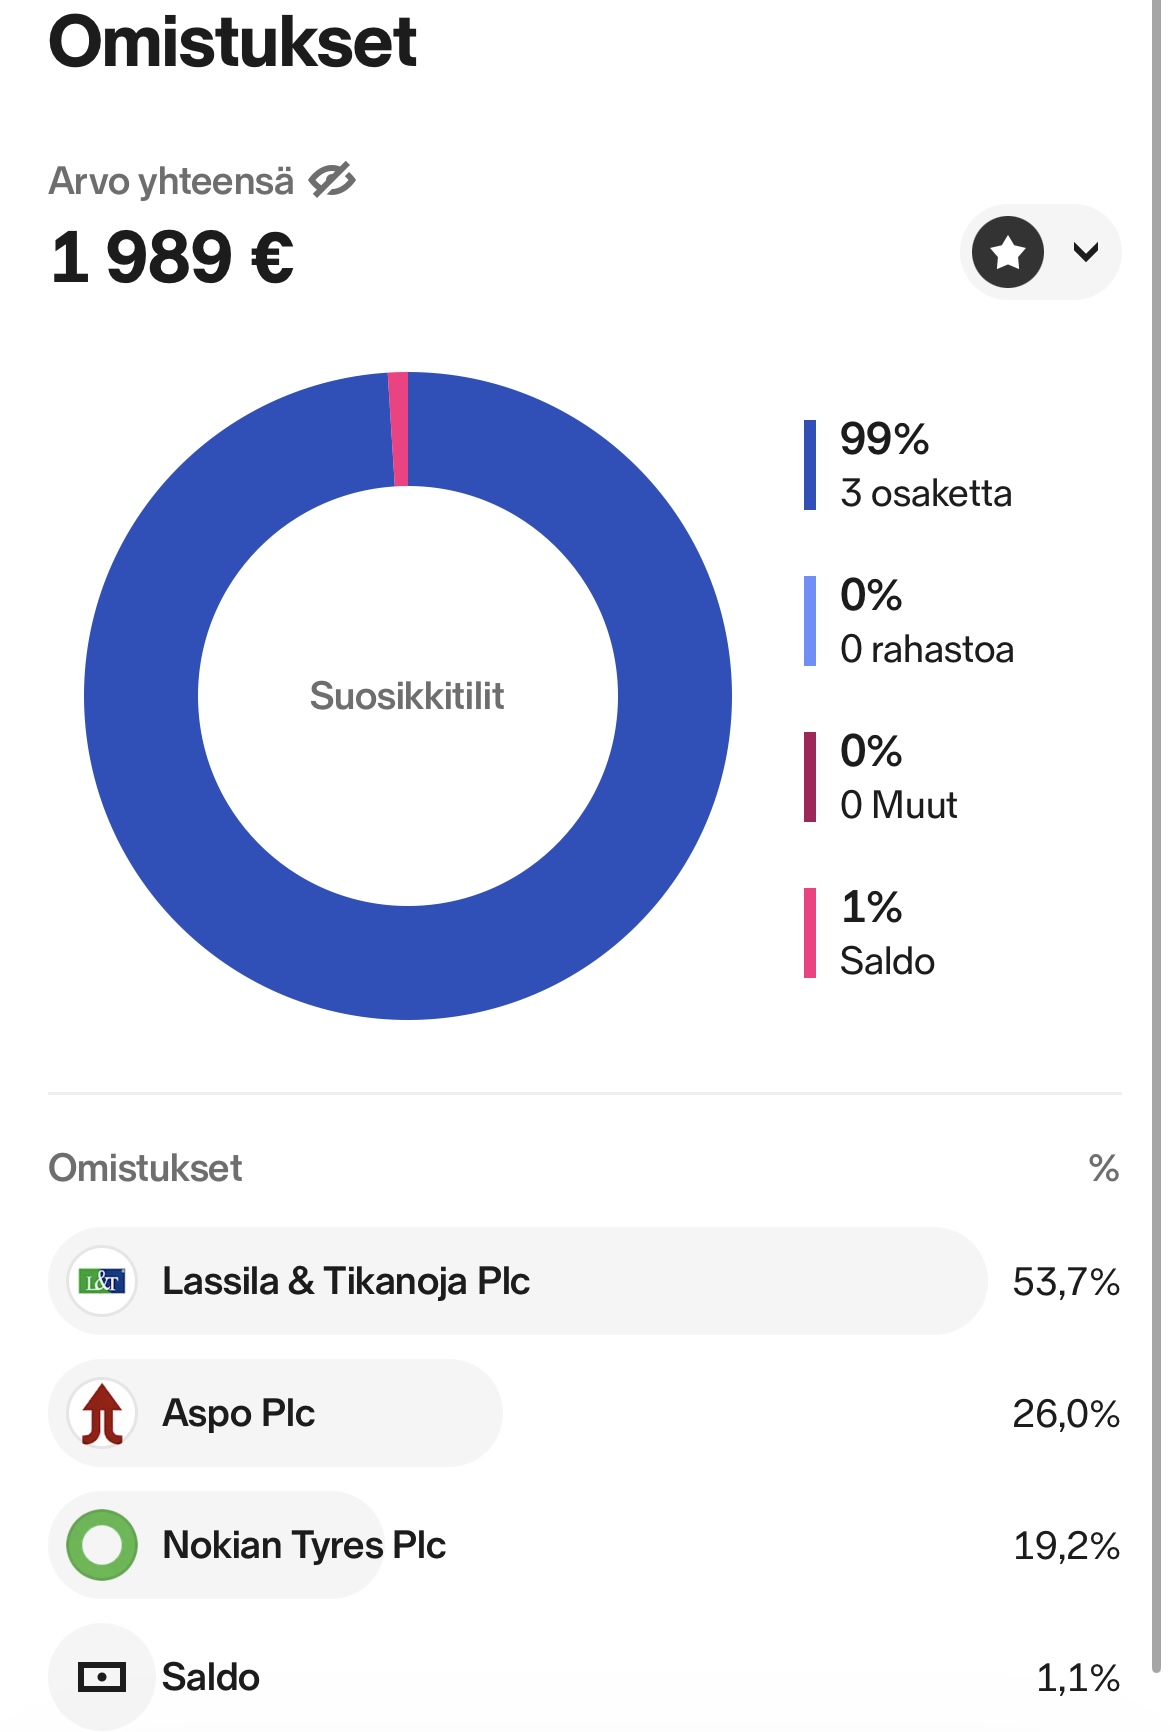
Nokian Tyres and L&T found their way into the portfolio of my Dividend Fisher blog, which I started at the beginning of the year. In the blog, I invest a sum of €1000 monthly, divided into two stocks, i.e., €500 into each. In the blog, I follow a value strategy that has been proven to outperform the index in the long run.

The portfolio content is currently, i.e., after two months of selections, as follows:
IMG_7577

You can read more on my blog, which can be found at the link below.

45 Likes

According to the calendar, it’s time to scratch together a portfolio review. A year has passed since the last update.

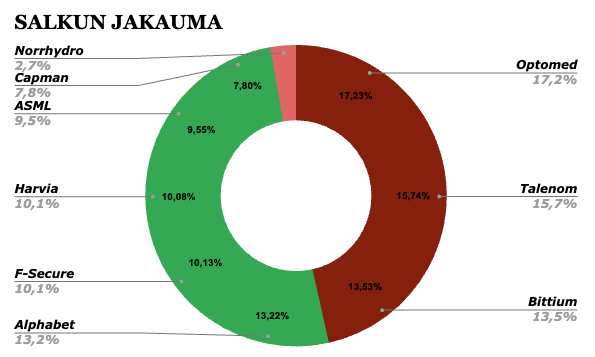
Portfolio Distribution and Movements Briefly:

Näyttökuva 2025-02-28 kello 22.49.50

  • Exited during the year: Spinnova and Hansa Biopharma
  • Reductions: Harvia
  • New additions: ASML and Norrhydro
  • Additions: Talenom, Optomed, F-Secure, Capman

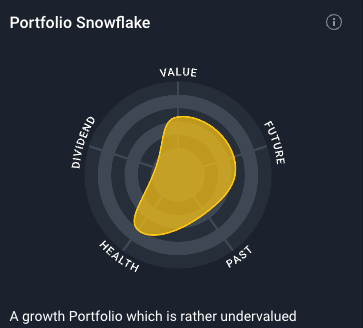
Portfolio Snowflake and a Bit of My Own Investment Jargon:

Näyttökuva 2025-02-28 kello 22.41.52
(Simply Wall Street)

  • I primarily invest for the long term and feel that a suitable diversification for me is around 8-12 companies. I can still follow these relatively actively.

  • I aim to keep the portfolio structure and risk level suitable for my taste. I would describe myself as a growth-oriented investor, but high-quality companies with a strong competitive advantage are an essential part of the portfolio.

  • Quite a few technology companies have ended up in the portfolio, and this hasn’t been entirely intentional. However, it indicates that I want to invest in companies whose business interests me. At the same time, I strive to understand the industry and make my own assessments of its development.

  • Once the above criteria are met, I evaluate the stock’s valuation. All of this limits the number of viable investment targets.

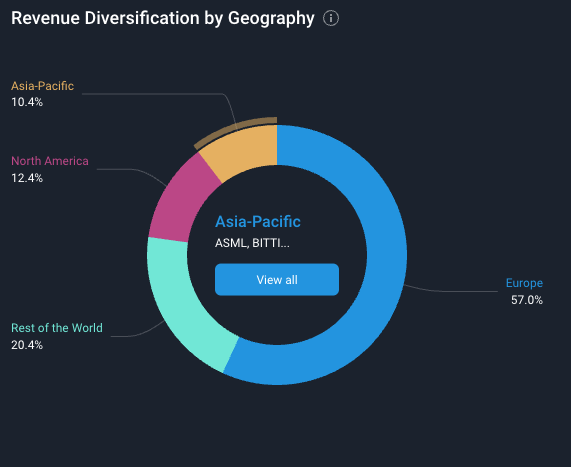
Geographical Distribution:

Näyttökuva 2025-02-28 kello 22.43.28
(Simply Wall Street)

  • I also invest in funds, through which I get geographical diversification. The portfolio’s geographical distribution is not as important and can be more concentrated in Europe.

Thoughts for This Year:

  • F-Secure is at an interesting stage, and I might add more of it to the portfolio. I must also commend CEO Timo Laaksonen for communicating his plans and goals very clearly.

  • Bittium’s situation needs to be re-evaluated during the year. I am currently disappointed that CEO Johan Westermack is not continuing in his role.

  • I wrote some thoughts on Talenom’s forum at the end of the year, but as a brief summary: I still have patience and faith in the company. However, the markets very strongly indicate that I am completely wrong again.

Finally, I could state that the CEO clearly has an impact on me as an investor and on how I see/experience the company’s future.

I might write the next update in a couple of years. A year passes too quickly in my opinion.

26 Likes

AOT

Mutual Funds
ISHR MSCI WrldA 18.08%
iShs Core EMMI D 6.89%
iShs Glb Water 10.32%
iShs MSCI EM USD 8.46%
Seligson OMXH 25 13.35%

Stocks

Kemira 4.61%
Nordea 11.91%
Saab 7.04%
Sampo 8.96%
Terveystalo 2.75%

OST

Atria 7.17%
Consti 10.94%
Fortum 13.38%
Huhtamäki 14.95%
Kesko 12.10%
Metso 6.77%
Nordea 15.79%
Terveystalo 10.49%
Wärtsilä 7.43%

S&P 500 ETF has been sold completely. Saab was bought, and holdings in existing mutual funds were increased. Saab proved to be a good purchase right from the start. Overall, investments are in positive territory.

12 Likes

Taavetti apparently goes with the flow, and additionally, Taavetti does not like entities that seem to support the eastern killing and looting mentality.

Approximately a quarter of Taavetti’s portfolio was allocated towards the US. It decreased by approximately 10 percentage points. The allocation towards the US in his wife’s portfolio was slightly smaller, and approximately 10 percentage points also left from there.

The following left the portfolios: Atkore, Bruker, FormFactor, Genuine Parts, Merck & co, Semler Scientific, T. Rowe Price, Trex, Zynex, and SPDR US Large Cap low vol ETF.

There will be some capital gains tax, but quite little, because some of the aforementioned were clearly at a loss. The majority of these are now back in euros, and soon Taavetti will start looking for things to buy from nearby regions. Feel free to give tips on growing, profitable, and reasonably priced targets.

The following remained in the portfolios: AbbVie, Napco sec tech, iShares S&P Small Cap ETF, CSW Industrials, LGL Group, MTron Ind., Oppenheimer, Verizon, and Western Alliance Bancorp.

Some of these might still be sold or reduced.

Taavetti has thought about Napco as follows. I am still holding onto it for “strategic reasons,” because it manufactures “things that improve internal security,” and Taavetti thus imagines there will soon be a lot of demand for all of that. Napco is currently at a loss in the portfolios, and the losses seem to be deepening further.

Justifications for others: God only knows…

Why had some of the previous ones appeared in the portfolio at some point? “God only knows,” and perhaps too much reading here and too little doing my own homework. I need to try harder with that homework in the future, especially if I put anything back into the US.

9 Likes

Screenshot 2025-03-13 114508

Here is my current Share Savings Account portfolio. The cash assets will probably turn into Incap, but the plan is to stick with these for at least this year, unless something significant happens. Lately, I’ve spent far too much time researching stocks and following their prices, which has also affected my personal life. Now it’s better to take some time to relax and avoid unnecessary trading, as my investment horizon is long anyway.

37 Likes

My portfolio is even more concentrated and narrower than before:

Harvia 42%
Seligson Phoebus 16%
Japan ETF 8%
Berkshire Hathaway 4%
Cash* 30%

  • Cash available for investments, emergency fund is not included here

As you can see, I have exited Vietnam and my USA weighting is quite small. Very strong conviction overall; I can’t bring myself to sell more Harvia, I have lightened my position in it quite a lot in recent years.

The plan is to expand diversification during spring/summer and buy new positions for the portfolio. However, finding new targets is quite laborious and difficult; so many companies I’ve researched have turned out to be quite a dud, that I have perhaps become overcautious.

Perhaps it’s more sensible to look for index funds whose content and idea I believe in. Well, good things come to those who wait; I need to get into the right mental mood, with enough energy for thinking. The time for concrete investment decisions will be later.

29 Likes

Well, I just noticed that the share of the defense industry in my portfolio is ~12%. It’s performing well now, but it could also drop sharply. I probably won’t take a larger position… Not with new money, at least. Well, maybe that new Europe ETF if something suitable for allocation comes up.

Defense holdings in the portfolio:
Kongsberg Gruppen about ½.
HanEtf Future of Defence about ¼
Wisdomtree Europe Defence etf about ¼

1 Like