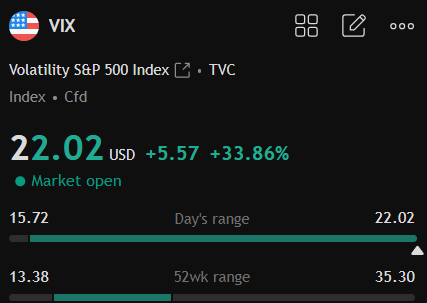
The beatings continue until morale improves
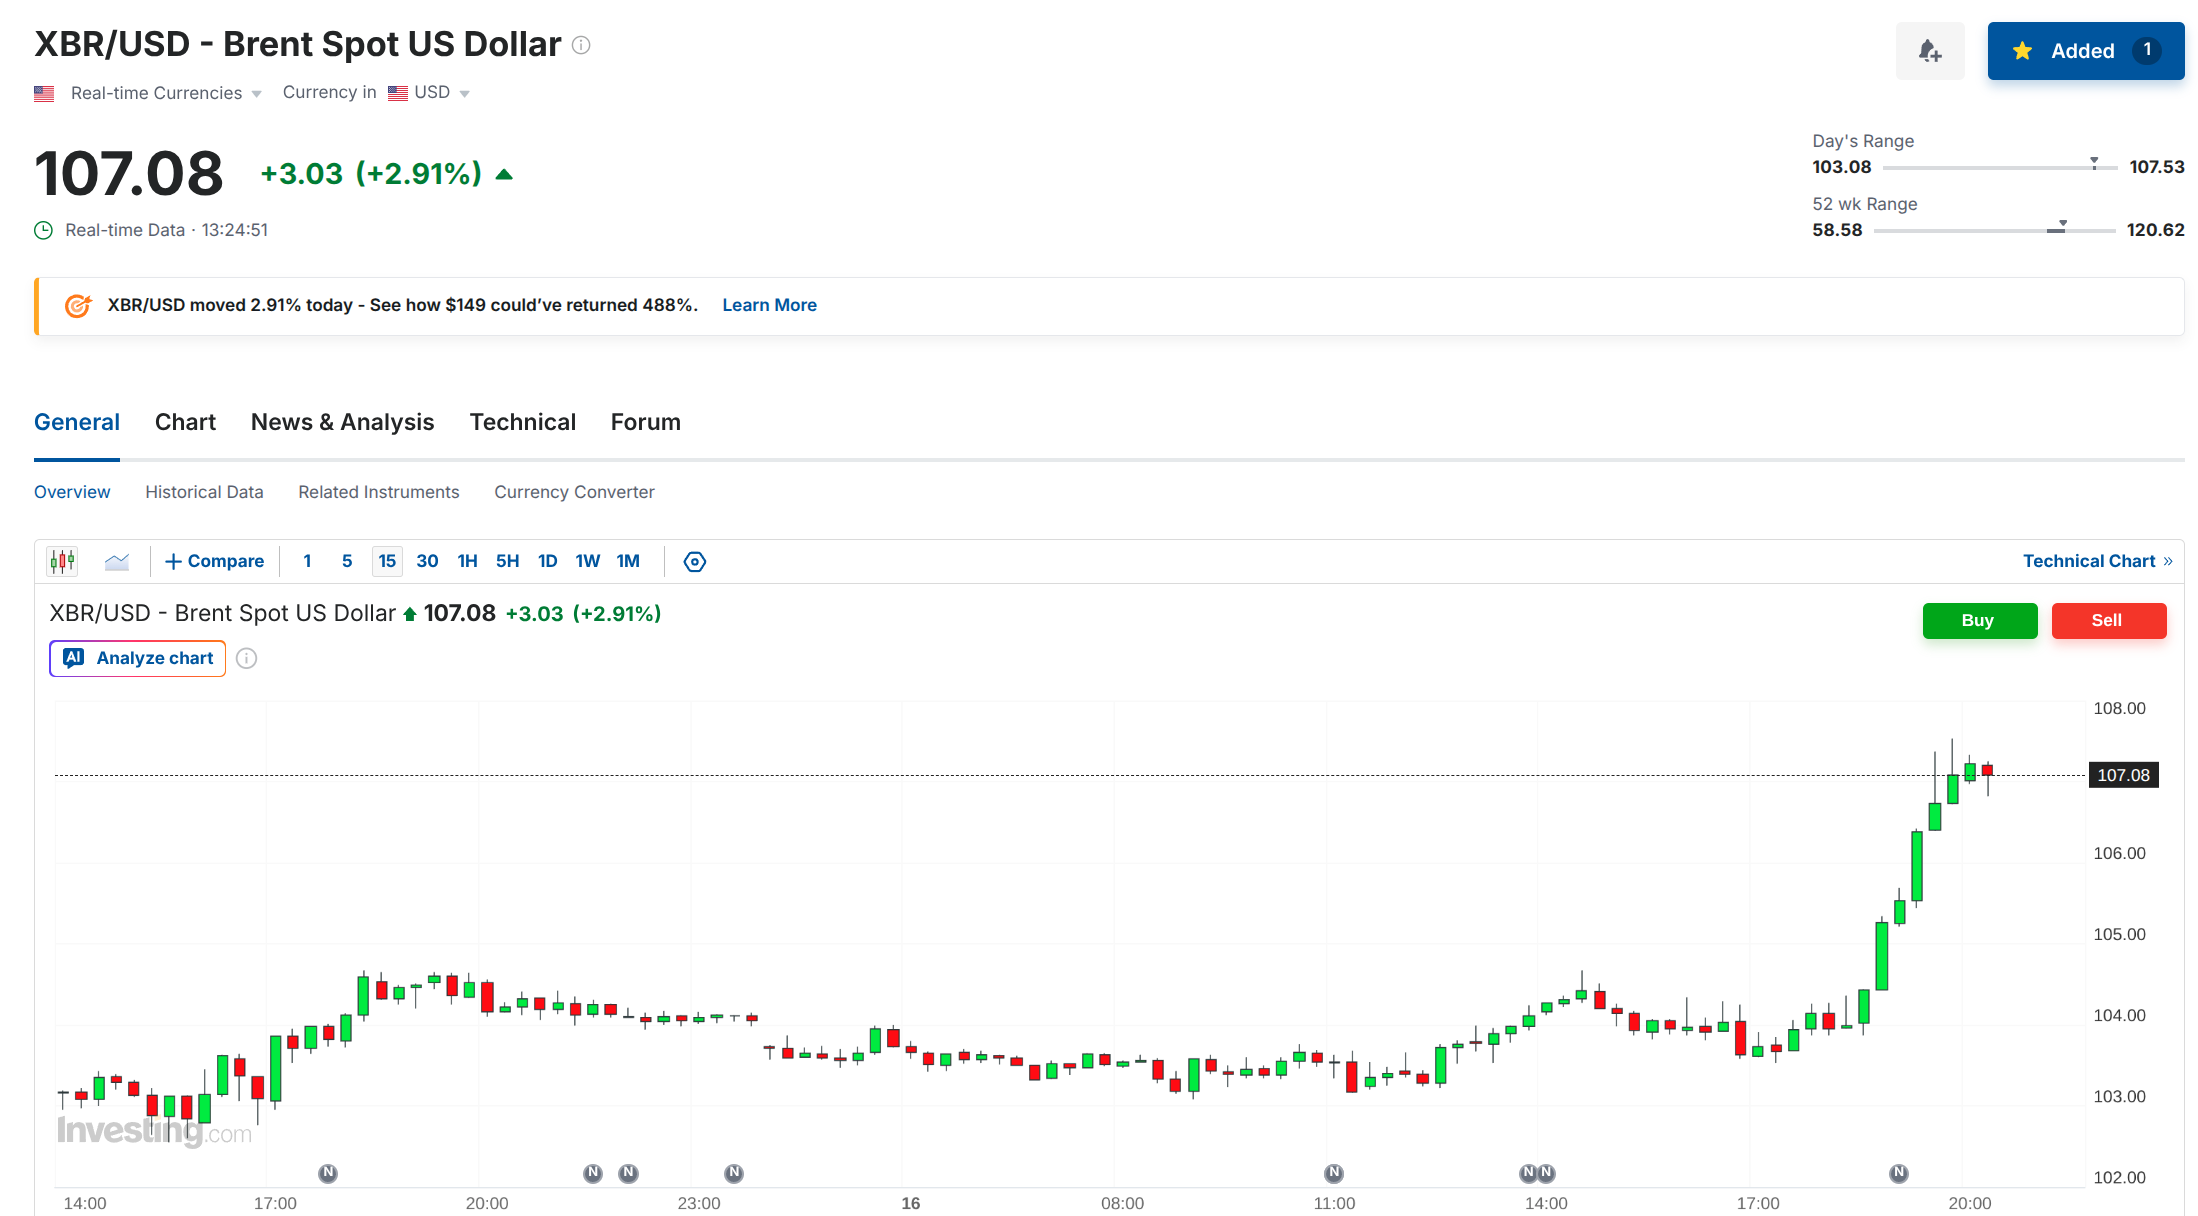
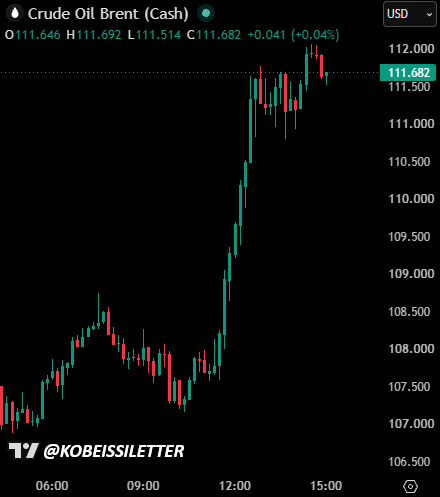
Wonder if something’s happening in the Middle East, since oil started printing a long green candle too.
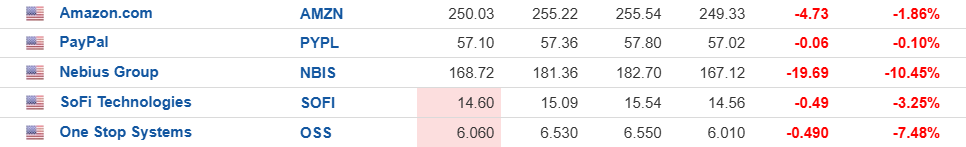
Looks like Nebius is down -12%. Getting cheaper and cheaper. Now it’s only something like EV/Sales 40 
There might still be a “bit of air” left to let out…
Even though it was probably a joke, this actually corrects to under twenty by the end of 2026 and under five in 2027. I can’t really say what the right price for the stock is, but maybe the market will tell us
Let’s at least hope Nebbe exists, and if it does, the valuation levels have definitely become much healthier. First North style. 
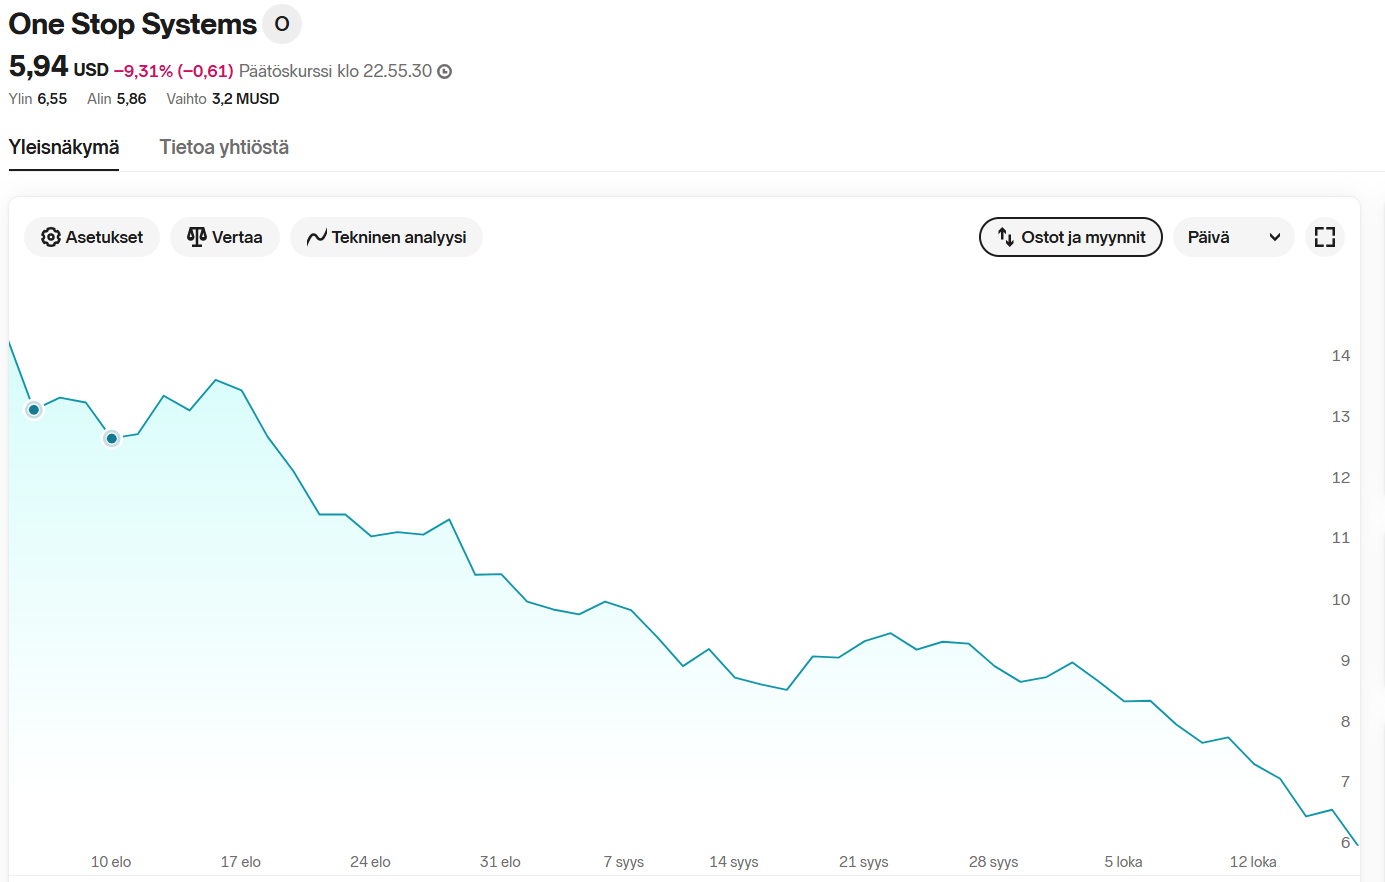
83 weeks’ worth of grocery money gone in Ossi, but if it does a 10,000x, then I’ll be almost rich 
They have indeed managed to grow revenue admirably and surely will continue to do so, so you’re probably roughly right about that. However, Nebius would need to improve its margins quite a bit from current levels just to break even. I can’t assess whether depreciation is done on a reasonable schedule, but I assume it is. If expensive equipment can actually be used longer, that’s a significant factor and will certainly provide clear support for profitability.
Still, an EV/S of 5 also sounds pretty high. It’s an extremely poor comparison, but companies like Kamux and Oriola also have plenty of revenue, yet the margins are so low that practically nothing is left on the bottom line. That’s why these are priced around EV/S 0.1–0.2. I assume Nebius faces plenty of competition. Maybe there aren’t any proper moats. Nvidia has pricing power. Margins might remain quite low. Maybe a few players will drop out, and only with a smaller group will it be possible to achieve somewhat higher margins sometime down the road. At this point, I personally can’t say what I’d be willing to pay for the stock. It would be something under $50 in any case, since I can’t assess the profitability any better. “Too hard” pile, but best of luck to the shareholders.
In the future, just set a stop-loss right after buying, say at around -7 to -10%.
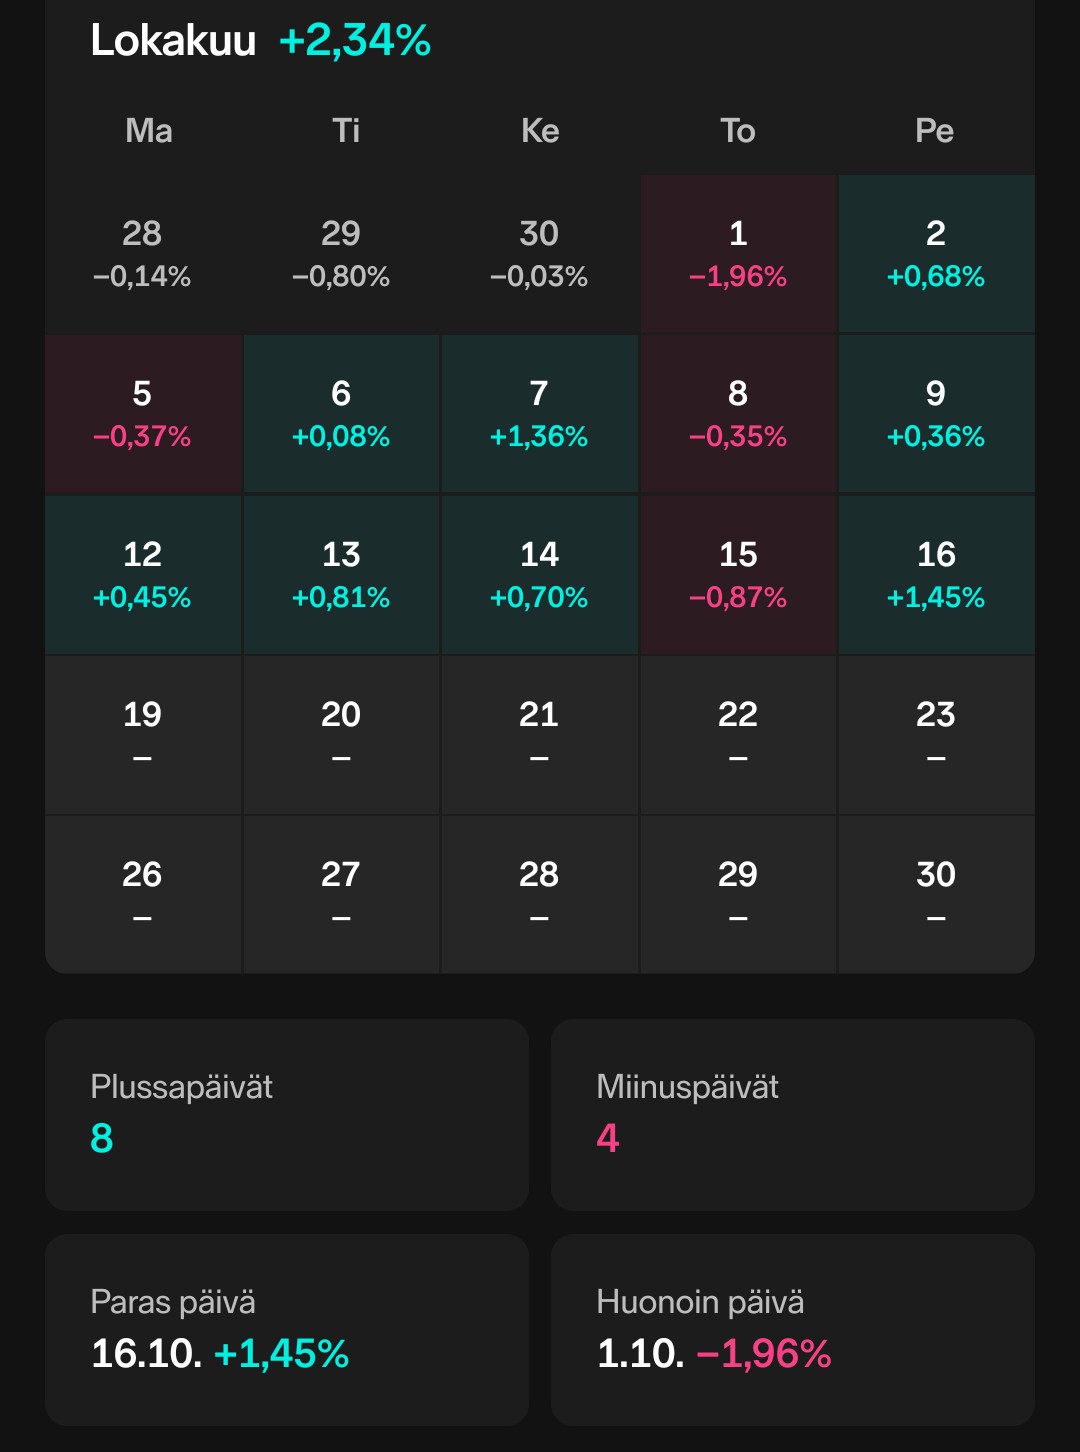
Such strange negativity on this forum these days. October has been pretty good through the eyes of a “Finland” investor 
After a rather sluggish September, my own portfolio is showing signs of picking up…
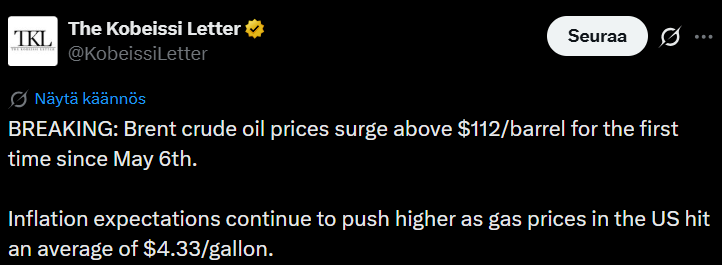
Brent crude has made a comeback to around the May highs
https://x.com/KobeissiLetter/status/2111172326549274909
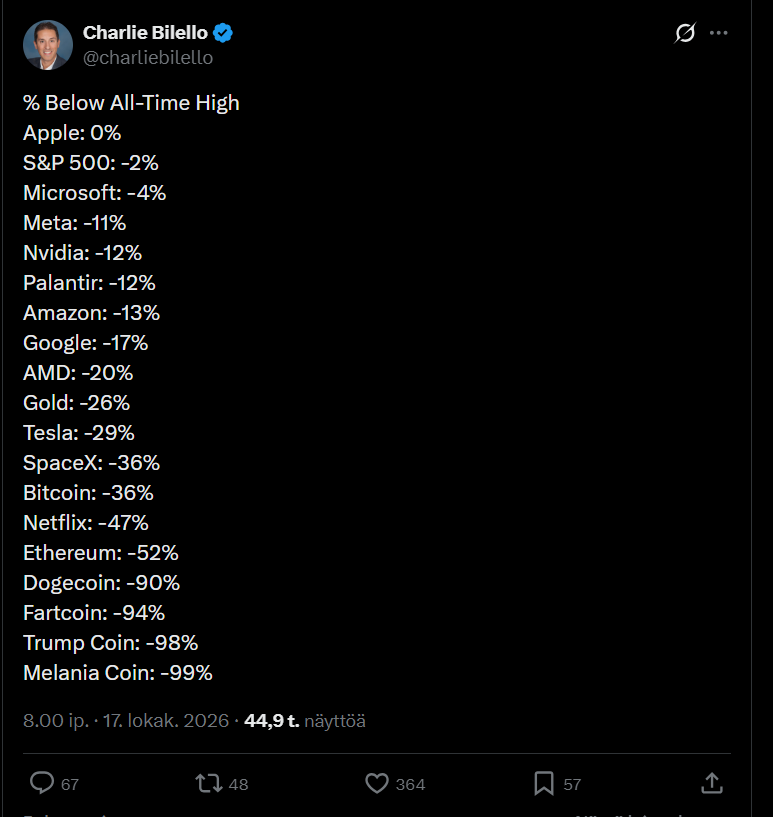
There are both winners and strugglers here on this “drawdowns from peaks” list
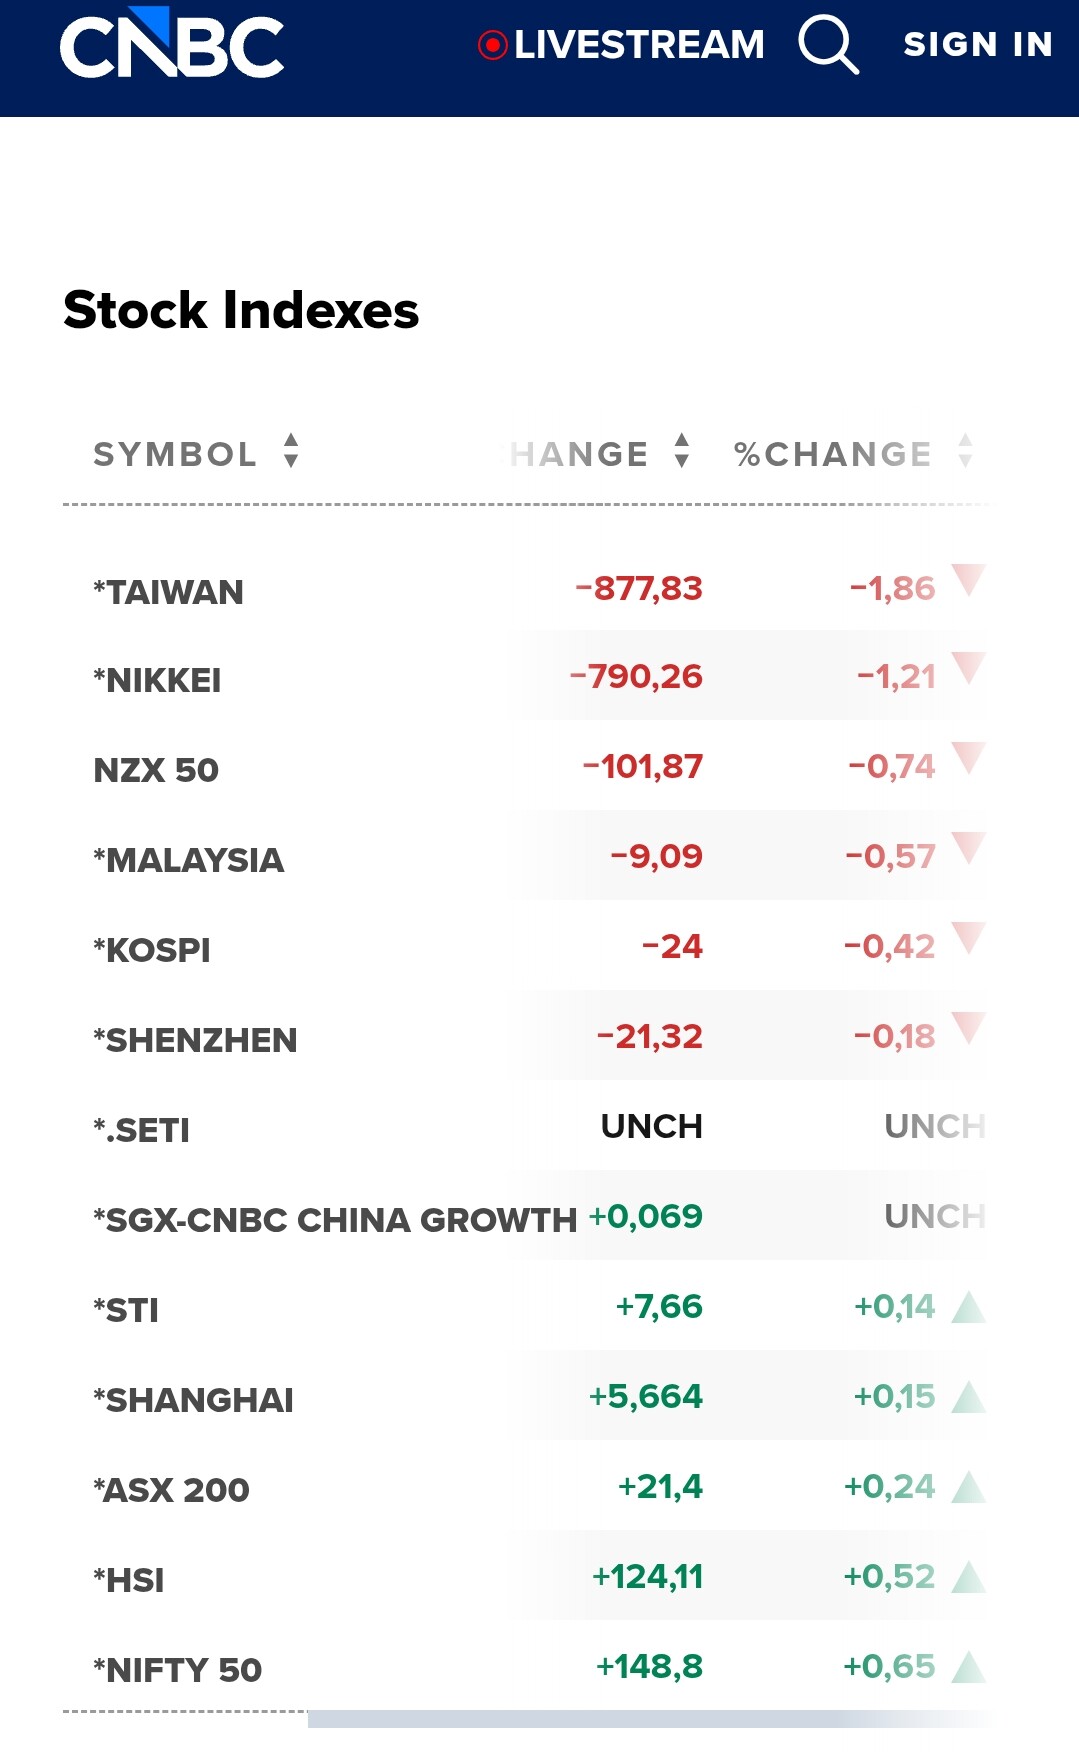
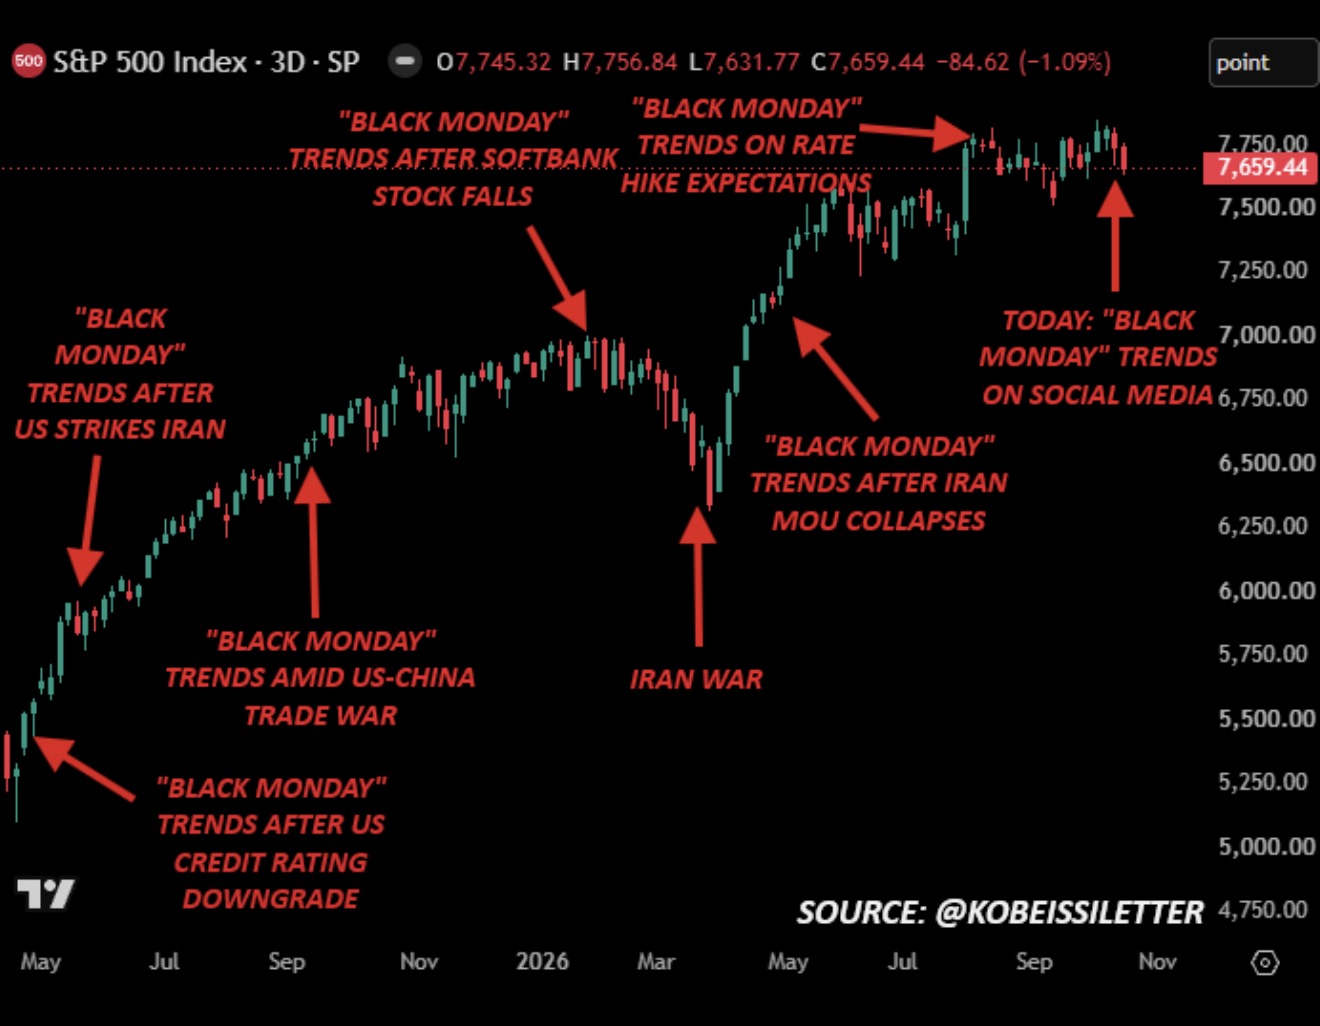
People on X were already crying out that Black Monday was coming, but here’s what this terrible crash actually looks like.
Which one tells the truth about the upcoming US open: futures or the Asian markets that have already opened?
These guys have all of Friday’s slide to make up for. Considering that, they don’t look bad. If they were crashing harder, it would definitely show in the futures as well.
That’s just how it is, and Black Monday trends every now and then anyway—and look at how that has turned out:
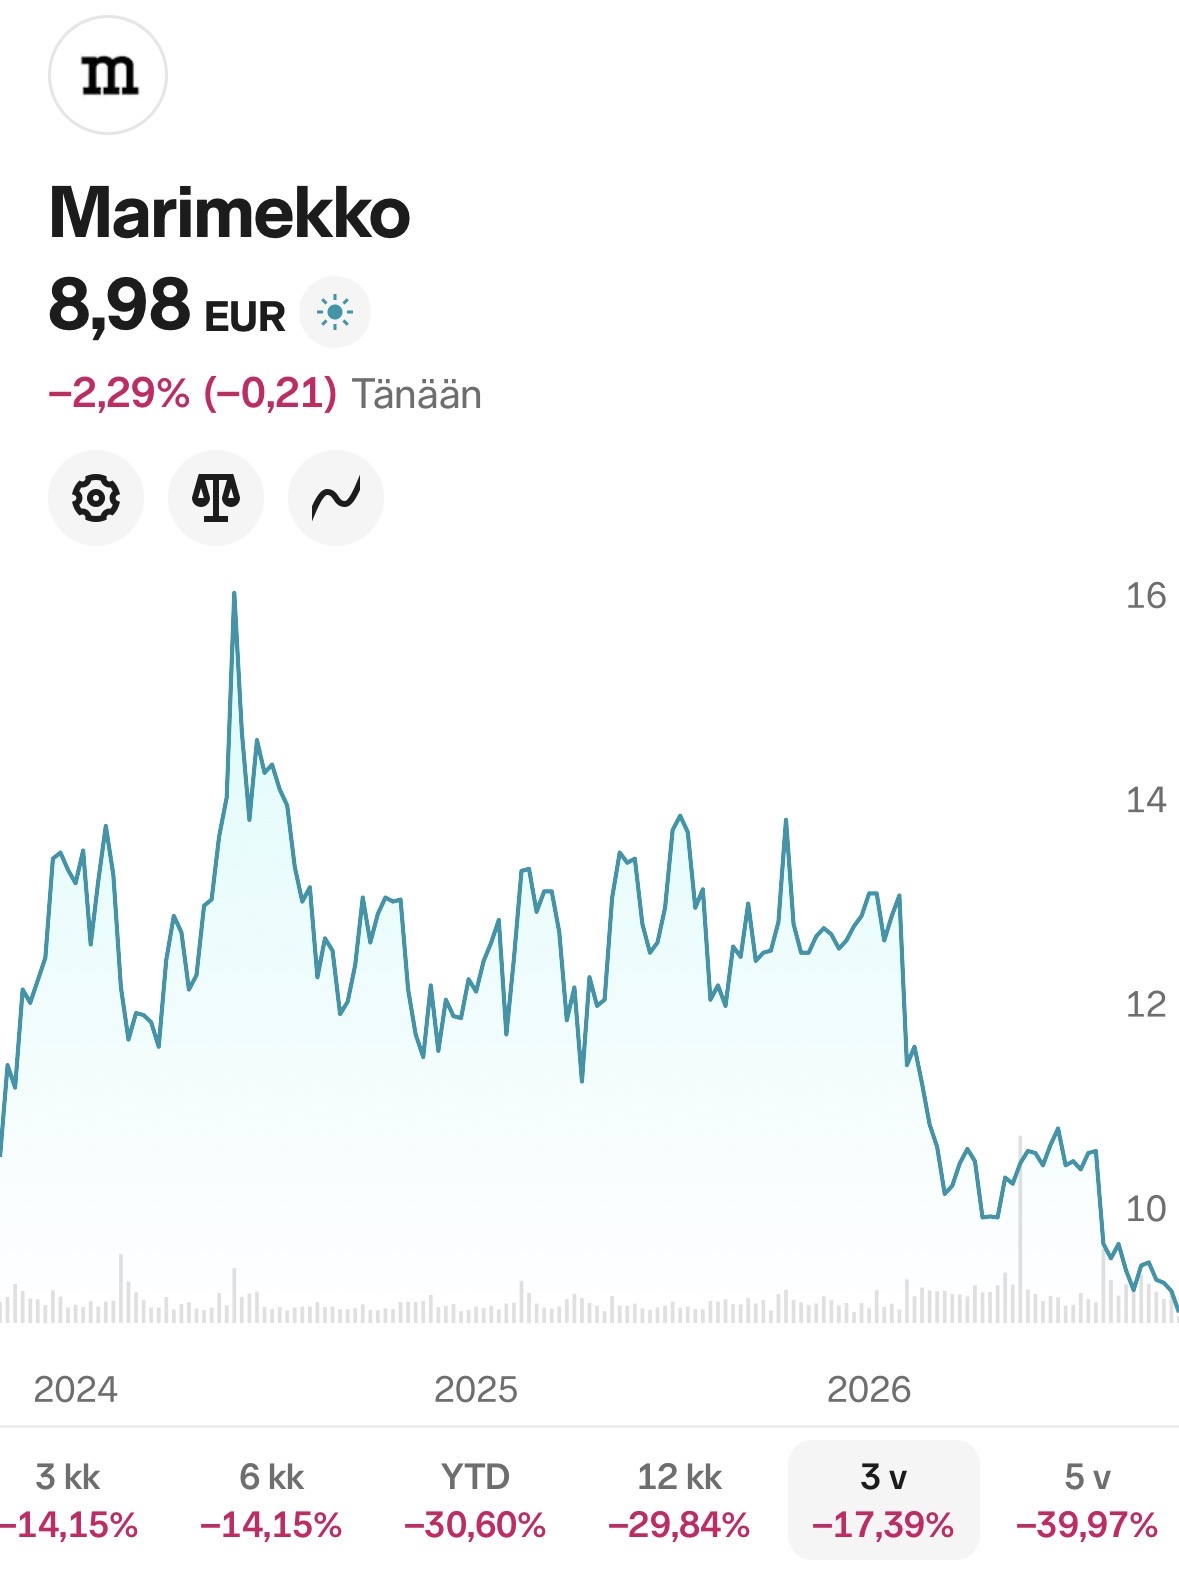
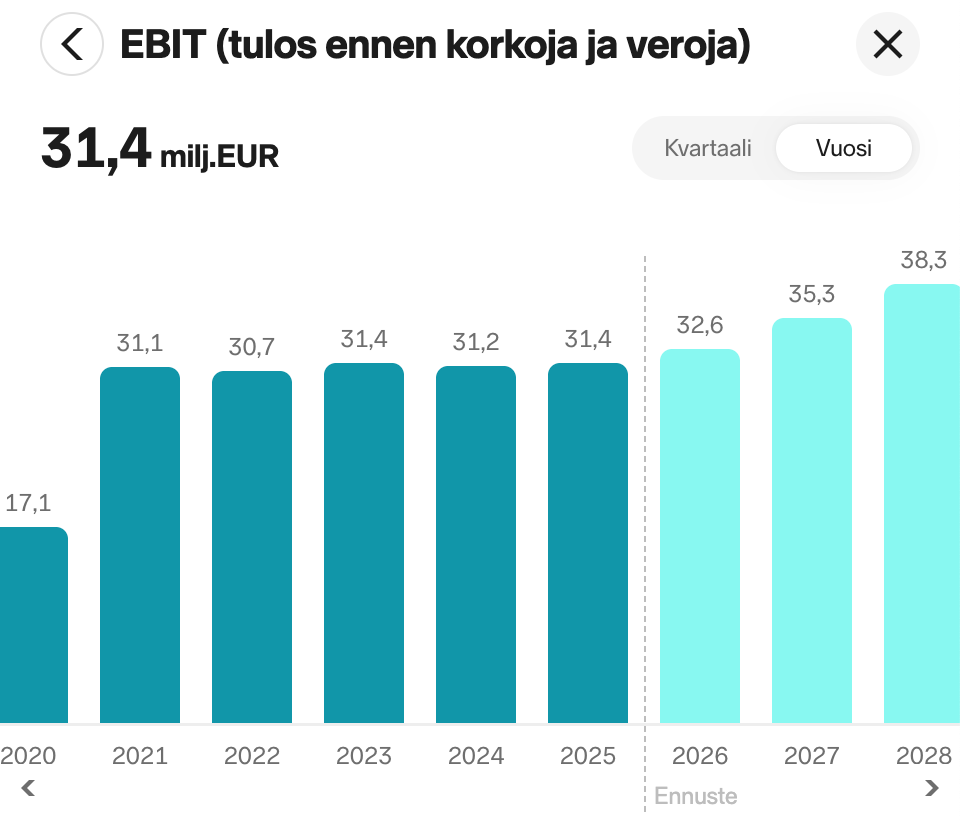
Rarely dreaded (let alone hyped), Marimekko dropped below nine euros and is at over three-year lows. YTD closer to -31%. It’s starting to look interesting, even if I don’t buy Inderes’ and others’ growth forecasts entirely as-is.
Edit: I’ll also link here user Almanakka’s post from August. The latter paragraph of the section considering the valuation has become more relevant.
Valuation: After the post-earnings drop, the stock is trading at around 13x the trailing 12-month comparable operating profit, and if the midpoint of the guidance hits, around 12x for the current year. The dividend yield is also well over four percent. This isn’t expensive, but not necessarily cheap either for a company that gets half of its revenue from a market where retail sales are dropping double digits, and whose growth target was just cut.
Somewhere between 8–9 euros, I could easily consider jumping in despite all the uncertainty. That would mean paying just over 10 times operating profit and getting a nearly five percent dividend yield from a debt-free company whose international retail sales are growing twenty percent (did you notice how I spun the narrative more bullish as soon as I started talking about buying). For now, I’m sitting on my hands.
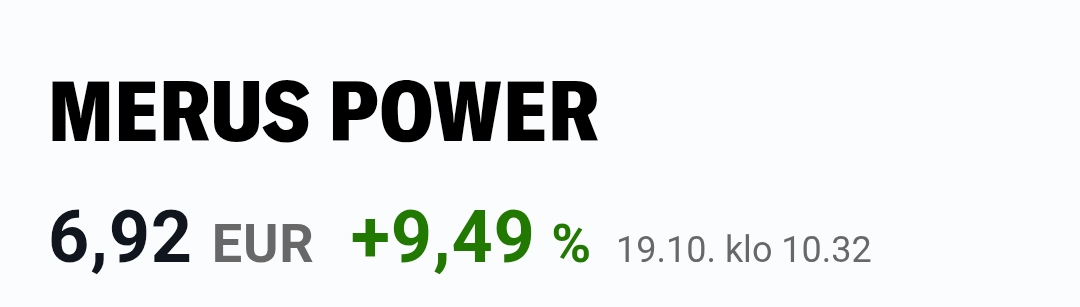
Quite a coincidence…
well… the volume was only 5.5k.
FTFY. (Fixed that for you.)