Kambi Group - Scalable B2B Sports Betting

Börsveckan näkee Kambin edelleen ostamisen arvoisena, tase hyvässä kunnossa ja markkinanäkymä edelleen hyvä

“Kambi has had a tough summer, the price has failed, only after the quarterly report and then the news that another large customer is lost, writes Börsveckan. On the other hand, the balance sheet is safe and Börsveckan believes that the market outlook for Kambi is still so good that the share is worth buying.”

11 Likes

“Kambi Group plc has acquired global esports specialists Abios in a deal which transforms Kambi into a leading provider of esports products and services as it seeks to capitalise on the emerging opportunities within this rapidly growing vertical. The agreement consists of an initial consideration of SEK150m, paid in cash, with up to SEK120m to be paid in earnouts related to product development and the future revenue performance of Abios.”

Now we can put the cash to good use.

19 Likes

Could this have prevented insider trading from buying their own shares? Or how do the rules work?

1 Like

An interesting acquisition; we’re getting a foot in the door regarding esports. Revenue in 2020 was 18 MSEK, which apparently doubled from 2019. I couldn’t find information on this year’s revenue figures.

https://twitter.com/john_larsa/status/1430225792806576131?s=19

News from April about Unibet and Abios:

"Within three years, Kristersson predicts esports to be one of the most important verticals for operators, leading to new innovative aspects of the experience, whether those are brand-new betting formats, widgets, or something different.

Today, Unibet prides itself to be one of the few sportsbooks that can reliably bring esports betting options to Swedish customers and other regulated markets, and no small part of this has been made possible by the company’s collaboration with Abios."

8 Likes

Kristian Nylen in an interview regarding the acquisition of Abios. A few excerpts;

“Abios has also developed its own proprietary technology and highly sophisticated data management methods, which will not only benefit our esports betting product, but also benefit us in other areas of the business.”

“Our primary objective is to ensure Abios has what it needs from us to continue on its growth path while we help them to build out their esports odds and trading capability. Once we’ve done that, we’ll of course look to incorporate the Abios esports betting and data offering into our modularised platform via our trading gateway, which essentially allows third parties to deliver content and odds to and through our core platform.”

“…the data management capabilities Abios has developed will benefit Kambi in other areas of the sportsbook. In addition to that, I also believe Abios has a range of products and services outside of the core sportsbook that will be of great interest to our partners, such as esports data and visualisations. So, in general, this acquisition will only be of benefit to our partners and improve the offering they can provide to their players.”

" Q: When should we expect the benefits to begin to materialise?

KN: We’ll get to work straight away but I’d expect to see momentum build throughout 2022 and beyond"

5 Likes

Insider shopping, already 31,905 shares

https://twitter.com/fininsyn/status/1430827312484868099?s=19

15 Likes

Pieni määrä, mutta jälleen sisäpiiriostoja
200 @ 234,60SEK

“On August 25, Cecilia de Leeuw bought 200 shares in the sports book supplier Kambi, where she is a board member. The shares were purchased at a price of SEK 234.60 per share, a deal of SEK 47,000. The deal was made at First North. This is apparent from transparency reporting to Malta’s Financial Supervision Authority”

7 Likes

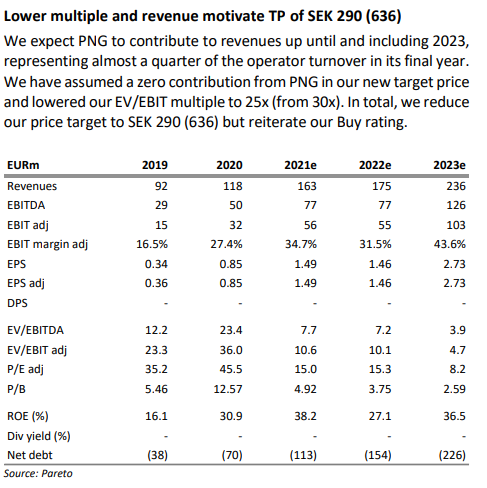
Pareto lowers target price to 290SEK (636SEK)
I will add the content of the analysis later if I can get my hands on it

EDIT:

19 Likes

https://seekingalpha.com/amp/article/4453934-kambi-can-bid-us-betting-farewell-or-can-it?

Bearish view on Kambi.
“”
starting from Q3 2021, we expect Kambi will lose 80% of its US business, which accounts for 58% of total revenues. Kambi will, thus, likely see its revenue drop by 45%.
“”

“”
However, we believe that

It will lose 45% of its revenue in the NTM
Its remaining 55% of revenue will grow much more slowly, at a rate around 20% - given it is coming to a large extent from Europe, where growth is slower given the market’s maturity
We, therefore, expect 106M USD revenue in the coming 12 months. This should translate to around 25M USD in EBIT. Indeed, in 2019, 116M USD revenue generated 32M USD EBIT.

Given the enterprise value of 652M USD, Kambi now trades at 26x forward EV/EBIT.

We believe this is actually quite expensive for a company that seems to have lost its moat and is set to lose another chunk of the American market in 2024.
“”

An interesting analysis of Kambi’s situation in the USA. The different size categories of operators are clearly highlighted, and it looks quite bleak if the numbers hold true (AND if the US were the only place in the world where sports betting takes place).
The author has not considered other regions besides Europe and the US, nor has Kambi’s expansion into esports been factored in. And, as far as I understand, it is still not clear whether the operators can get their own software to work well enough (?).

10 Likes

Interview with Kambin’s CEO (Behind a paywall). It’s interesting how different the views of the CEO and the analysts are.

Roughly, as I understand it:

Nylen sees Kambi as being in a very strong position.

  • Widest pipeline ever

  • Strong cash position

  • Thoughts that it’s not realistic to get Score’s sportsbook working in 24 months

  • Kambi will be operating in the US for at least another 5-10 years

12 Likes

Translate:

"The sports book supplier Kambi has seen its market value more than halved since the peak in April, but CEO Kristian Nylén is positive about the future. It appears from a Di interview with the Kambi manager where he highlights that the company’s pipeline is larger than ever.

Nylén says that Kambi performed well during the year, but that the customer Penn bought The Score was disappointing, but he does not understand the plot that the acquisition was made to get a customer platform and sports book in-house. Nylén believes that The Score has never communicated that they have a sports book, but that they should only have hired one person who will now start developing a sports book. Penn has communicated that they aim to make the sports book internally within 24 months, something that Nylén believes will be difficult.

Regarding the acquisition of Swedish Abios, which delivers data in e-sports, Nylén says that the market is still in its infancy. He thinks it may take a few years before it gets big but that it was the right timing to make the investment now.

Even after the acquisition, Kambi is sitting on a large cash register and Nylén replies that they are looking at a number of alternatives, including further acquisitions. But he also says that it is not impossible for them to start looking at dividends or share repurchases if they do not find other opportunities, even if it is a board issue."

EDIT

Lisää sisäpiiriostoja hallituksen jäseneltä

"Kambin hallituksen jäsen Patrick Clase osti tiistaina 4 381 osaketta 959 000 kruunun arvoon.

Kauppa tehtiin hintaan 219 kruunua.

Kaupan jälkeen Patrick Clase omistaa 42 000 yhtiön osaketta"

EDIT 2

https://www.avanza.se/placera/forum/trad.1595.3781489.html#8072074

Avanzan palstalla joku oli tuon koko haastattelun postannut foorumilla. Tuon pystyy chromen selaimella kääntää helposti suomeksi tai translatella (englanniksi tulee yleensä helpommin ymmärrettävä)

13 Likes

Kindred Group plc (Unibet)

5 Likes

Draftkings did not have a completely smooth first NFL Sunday. They have until February to get things working. Although, it would be great if the platform was already working before the season starts. :wink:

8 Likes

If Fanatics were to acquire RSI, it would definitely be a positive driver for Kambi, as it would be a natural progression to continue as a customer and gain greater muscle for growth. Acquiring Betsson, on the other hand, would be a slap in the face.

EDIT

https://www.actionnetwork.com/legal-online-sports-betting/fanatics-closes-in-on-acquiring-sports-betting-company/amp?__twitter_impression=true

"Fanatics, the $18 billion conglomerate that is the leader in sports merchandise, licensing and recently trading cards, is expected to soon close on a deal to buy a sportsbook operation.

Sources say meetings with Rush Street Interactive (RSI) and Swedish company Betsson have been productive and the company might buy one of them soon.

Rush Street makes a lot of sense. While they are in 10 states including Illinois, Pennsylvania and New Jersey and are top five in online gross sports betting revenues — they have the weakest of brands for a company of their size.

In other words, they can easily change names to an acquirer like Fanatics or even be rebranded ESPN Sportsbook.

Sources say RSI is in the lead for the rights to ESPN’s name in gambling, one of the reasons why Rush Street worked to win the third skin in Connecticut with the lottery after DraftKings and FanDuel partnered with the two Native American tribes. It was recently reported by the Wall Street Journal that ESPN was looking to sell a sports betting rights package for $3 billion.

Betsson would be more of a backend technology acquisition and a further leap for Fanatics. While it has an impressive iGaming product, it does not yet operate in the United States."

My gut feeling says that RSI would be a more logical choice precisely because of its US coverage. Even if Betsson’s sportsbook could be integrated, the leap directly to it would be quite significant, and I don’t see why Fanatics would want to focus on the non-US market at the moment, even if Betsson could be acquired more cheaply. The value for money at this point might not align with the strategy. However, someone on Twitter speculated that Fanatics might acquire both, but I don’t know how likely that would be…
6 Likes

Today, Betsson issued a statement that the company’s CEO is stepping down. This gives me the feeling that Betsson might be an acquisition target.
This would be bad news for Kambi, though. If Fanatics also acquires Rush Street, then the intention is probably to replace Kambi with Betsson’s technology.

6 Likes

This Kambi is such an interesting stock right now. It’s either very cheap, or… it’s not too expensive in any situation, why? Well, because the biggest risks have already materialized, i.e., Penn + DK left. There’s certainly a risk that a couple of other relatively large ones will leave, but the revenue and profit would remain in such a condition that it would still support the valuation at these prices. People are currently paying for companies where the valuation doesn’t make any god damn sense. Here you get a company that is already profitable, margins are :ok_hand: and there’s a lot of market left to conquer.

This is also an interesting situation in the sense that we don’t know what kind of fundamental change this market is going through? Will everyone switch to the Vertical Integration model? I don’t think everyone can do that, only the really big ones.

I decided to buy at the current price of SEK 211, because if you can’t sell it, then you have to buy it when the price drops every day :smiley: catch the falling knife.

10 Likes

Thoughts from Unibet founder Anders Ström to Affärsvärlden concerning outsourcing vs. in-house management of the sportsbook. This should, however, be read through glasses that consider Anders to be Kambi’s largest shareholder through Veralda.

"The interview also touched on the question of whether it is more advantageous for gaming operators to have a sports book in house or outsourced. According to Ström, the latter option is better because it is difficult to build your own sports book and refers to Kambi customer Penn National Gaming’s purchase of Score Media for that purpose.

“Penn has bought a company that does not have its own sports book, but a gaming platform. It remains to be seen how it develops. Building a full-fledged sports book in two years is a big challenge. I would say no to that job myself,” he said.

Anders Ström is through the investment company Veralda the largest owner in Kambi, where he also works with business development."

Regarding that, the chairman of the board is also stepping down from his position due to a crisis of confidence. DNB also does not believe there is much substance to the Fanatics acquisition rumors.

"It was on September 17 that Betsson’s board announced that a process to replace Pontus Lindwall had begun. Barely a week later, the news came that chairman Patrick Svensk was also leaving his role. The reason was stated to be that major owners no longer had confidence in Patrick Svensk with reference to how the CEO issue was handled.

The decision to find a new CEO increases the risk in the Betsson case, according to DNB. The gaming operator is facing opportunities such as re-regulation in the Netherlands and the B2B sports book in the United States. The fact that Patrick Svensk has also resigned raises further questions, the bank writes.

Furthermore, DNB does not attach much importance to the recent acquisition rumors.

“Of course, there may be different views on how shareholder value should be maximized related to potential consolidation opportunities. But at the moment, it seems unlikely that there is much substance behind the recent media reports about potential discussions with American Fanatics, we think."

3 Likes

"Kristian Nylén, CEO, Kambi, said: “Kambi is delighted to have been selected as the exclusive online sportsbook provider to BetCity.nl and provide the support for them to launch on day one of the market opening.

“The Netherlands will be extremely competitive but the combination of Kambi’s technology and sports betting know-how with BetEnt’s sports-first strategy leaves the BetCity.nl sportsbook well placed to succeed.”

Melvin Bostelaar, CEO, BetEnt, said: “We are proud to partner with a world-renowned company like Kambi which is widely regarded as one of the market’s best sportsbook providers.

“It is exciting to enter the regulated Dutch market with such a first-class partner who fully supports and has an unrivalled track record in our values of compliance and sports integrity.”

16 Likes

News from last week. This was discussed here in the summer when SGC was looking for divestment targets to pay off its enormous debts. The sports betting market is indeed quite widely interesting, I don’t think UFC has appeared in these discussions very often (or I’m reading the wrong sources, which wouldn’t surprise me much either).

3 Likes