Live footage of Remedy shares in my portfolio.

Live footage of Remedy shares in my portfolio.
I’m letting out pretty much the same kind of scream myself.
Isn’t this a buying opportunity when you need to have a bucket next to you while hovering over the buy button? 
(There’s risk on offer, but that’s what diversification is for. If a single outfit in your bag is so large that it going to zero ends your world, you don’t have enough diversification)
I decided to try a slightly different angle for the analyst interview. The entire 20-minute discussion is built around one core question. We won’t waste any time pondering quarterly results, but will focus simply on whether this is a good investment or a value trap.
Enjoy!
Well, a strike is interrupting train traffic in Finland again, but at the same time VR announces that it has bought MTR Express’s long-distance operations in Sweden.. If it gets cleared by the competition authorities..
The same VR, by the way, is fighting tooth and nail against competition being introduced to rail traffic in Finland.
I moved this to the coffee room because it doesn’t really relate to Neste anymore. This technical maneuvering regarding regular versus special dividends is quite amusing. Of course, it’s also quite funny how much companies are prisoners of their own dividends. They don’t dare cut the dividend in tough times for fear of the wrath of dividend-crazed shareholders, even when it would be sensible. And then during good times, they don’t pay everything out right away because it’s nicer to just grow the dividend bit by bit. After all, they would have to pay even more next year, so by raising it more moderately, they can sustain the growth for longer.
In the long run, a growing dividend generally requires earnings to improve as well, but year-to-year fluctuation would hardly be harmful in reality.
I’m not asking for investment advice, but what would you do in this situation? 
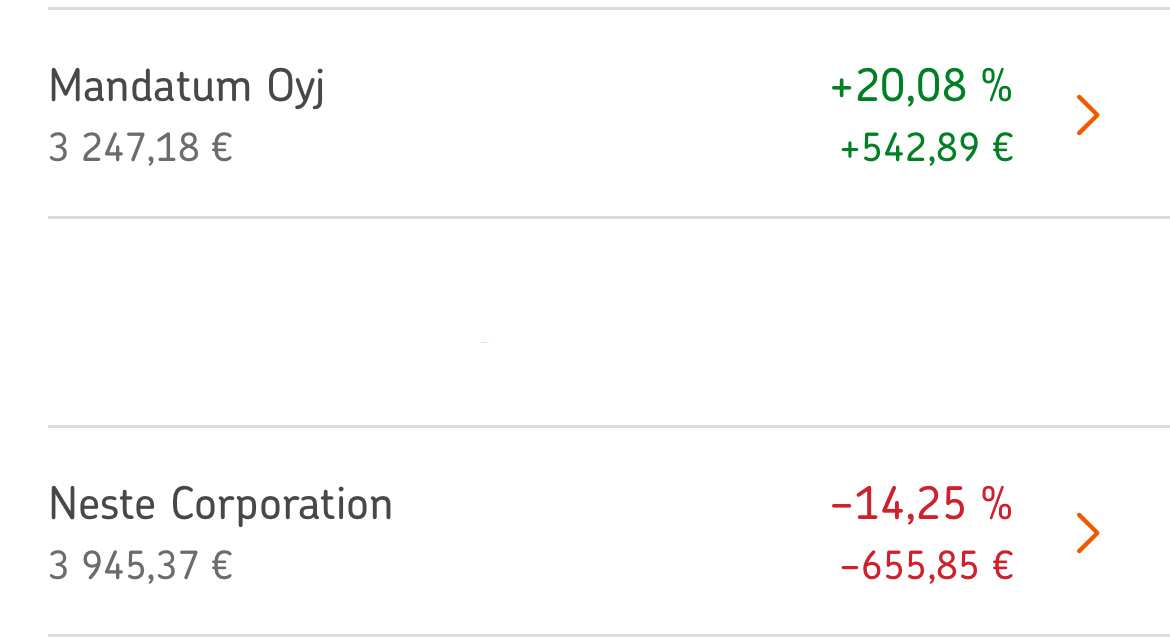
Would you reduce Manta at a profit and buy Neste on the dip? Or would you just let it be and let time do its work?
Manta 795 shares / avg price €3.40
Neste 143 shares / avg price €32.18
I agree. In my opinion, one could at least consider distributing such excess cash reserves through share buybacks. This is, of course, a delicate game of whether the company’s share is attractively priced.
One could say that last year Neste did not see its share as an attractive investment and therefore did not buy back its own shares; they were indeed right, and the extra dividend was the right move.
Welcome to the debt club with us; in the debt club, the investment strategy is: “Cut your profits and let your losses run.”
EDIT: if you don’t want to join the debt club, the basic rule is that if you don’t know what you should do, then you shouldn’t do anything. There’s no point in staring at stock prices every day. Judging by your enthusiasm, you still have many decades of investing years left, in which case fluctuations over weeks or months don’t matter at all. In the #rahapodi episode that came out a week ago, it was put well: to get the best return in the long run, you should take as much volatility risk as possible, but avoid the risk that can lead to a “game over.”
It’s wonderful to join the group  Are there any debt club gatherings planned for the near future?
@kimsku good addition, I always think this way about others’ rushing, but I’m guilty of the same hastiness when it happens to me 
Weighting is currently 55% in the stock portfolio and 45% in funds, so I’m well into the green thanks to funds and ETFs (so adding more weight there). And the learning continues. 
At this point, I can no longer do anything but admit that I’m in need of help.
I’m considering selling my S&P 500 Information Tech ETF (the only green line in my portfolio) to buy Valmet instead, because d i v i d e n d s.
The devil on my shoulder justifies this by saying that the Mag7 rally simply cannot continue, so now would be a very good time to sell.
Voice of reason, where are you?
Personally, I bet that in the long run, the S&P 500’s gains will beat your Valmet 100-0  (then again, I hear there’s room in the debt club)
Stonks only go up.
I would sell both and buy a Brazilian company specializing in educational technology.
Maybe that wasn’t the answer you were looking for
Right then.
Metsä Board just released its 2023 results and 2024 guidance.
“Everything went to ****** and it’ll be the same next year, but maybe less so”
“The Board proposes to the AGM that the entire cash pile be dumped into dividends”

Try finding similar conviction in the S&P 500 
Yep, maybe it’s best to just take a deep breath and stick to the plan; it might be a good idea to even close this forum sometimes  I’m clearly way too susceptible to influence.
I’ll come back in 10 years (who am I kidding, I’ll be back in 10 minutes) with my S&P 500 to see how the rest of you are doing.
Even trimming positions in the model portfolio doesn’t always hit the mark!
Of course, trimming Remedy was the right move, but not Harvia.
Rauli is a pessimist regarding Harvia; his annoyance was visible on his face today as well.
I often sell half of a position when I move my chips to a different stock. Selling half leaves room for some consolation, whether the move was right or wrong. Mandatum is a safe bet, but on the other hand, Neste performs better in the summer when more gas is being burned!
I don’t know if this will be of any help. But what really helps curb my own wavering is having pre-defined geographical limits for my investments. For example, I’m not currently adding any new capital to my Finnish portfolio (since other geographical regions are underrepresented). If I want to buy something there, I’ll first sell something else or wait for dividends. Getting its internal balance right is still a work in progress, but making rash moves and breaking previously set limits can worsen the situation in the bigger picture.
(As a side note and a wild idea regarding S&P 500 ETFs, personally, I’ve been considering an equal-weight version, where all five hundred companies have the same weighting. The idea is that the other 493 will follow in the wake and slipstream of the Mag7.)
With the US market growing for Harvia, it’s a really great thing and, in my opinion, almost the most important market. I mean, you’d think they’d notice it on the US side as well, so hopefully they’ll be buying like crazy.