Hi.
I’ve been following Corsair Gaming since its IPO and I see good potential in the gaming industry for the coming years. I’ve been considering adding the company to my portfolio and would like to hear if anyone else on the forum has been following the company and could offer some objective insights into my views. The stock has clearly already priced in growth (approx. 28 P/E), and it is valued higher than Pegatron and Gigabyte by P/E ratio. However, I believe Corsair’s skyrocketing valuation has largely calmed down since November 2020 and is starting to be in buying territory by my standards. Also, the growth and financial figures of recent years seem promising to me, and the growing trend of gaming among young people makes the stock a very attractive buy for a 5-10 year horizon.
If you have any thoughts on the pros/cons of the stock, I’d love to hear more.
Corsair has always had a pretty good reputation. First mainly with special DDR memory modules for overclocking, then later with power supplies, and nowadays even with peripherals like SSDs, keyboards (I’m typing this on a Corsair right now, and my PC has a Corsair PSU) and headphones, etc. The quality has remained good there too.
Revenue Growth
2018-2019 ~17%
2019-2020 ~65%
(Figures are approximate, calculated with a pocket calculator)
Did anything else happen in 2020 besides people staying home due to corona and more frequent hardware upgrades for gaming? Were market shares gained, new products launched, or was there other investment in growth?
Indeed, 2020 saw a nice growth spurt, which also brought the result into positive territory. What kind of growth can be expected in the future? Probably not that >60%, which would make a PE of 28 practically irrelevant.
This is an interesting opening; I wouldn’t have guessed Corsair’s valuation to be so reasonable. I haven’t (yet) delved deep into the valuation, but are there any grounds for it? Could the chip shortage drag the share price down, or are there company-level uncertainties? What other comparables are even available on the stock market?
Regarding @Torniojaws’ comment, I must say that for some reason, even around 2012, no one in my circle recommended Corsair power supplies  At least in Finland, they seemed to be among the cheapest and allegedly shortest-lived from Jimm’s selection, and in the worst cases, they would take other components with them when they failed. My own perception of the company has remained consistent with that, but in ten years, the quality has probably improved, and the product range and visibility certainly seem to have grown by leaps and bounds!
I had to look it up, my 620HX has been in use 24/7 since November 2007 until now  It wasn’t the cheapest back then, 143 €, but it was at least worth the price
 At one point I bought a bigger power supply, Seasonic’s “premium model” X-1050 in 2017, which sometimes wouldn’t even start, so I went back to my old familiar 620HX… Here’s a masterpiece from Seasonic in my second PC

As I understand it, the valuation is currently considered reasonable due to the very modest growth expectation given for next year. Considering the growing trend in gaming and the company’s current situation, I believe there is still potential compared to possible losses. Corsair’s product-specific profitabilities are at a very high level compared to other companies in the industry. I included it in my portfolio for the first time today, and it’s possible that if growth continues to be good and profitable in the future, I will never sell it.
The topic is interesting, both as a hobby and as an investment case. The last time I put together a computer, I ended up with Corsair fans, RGB lights, and other accessories. That then sucked me into the Corsair ecosystem, which will be difficult to escape from in the future because I’ve already “invested” in it, configured it to my liking, etc. … a bit like with Apple. Competitors are surely aiming for the same thing: Razer Chroma, Steelseries Engine, etc. Could it be that software is the key here too, even if the companies’ main product is hardware?
Here are Google trends for search volumes of the aforementioned software over the last 5 years:
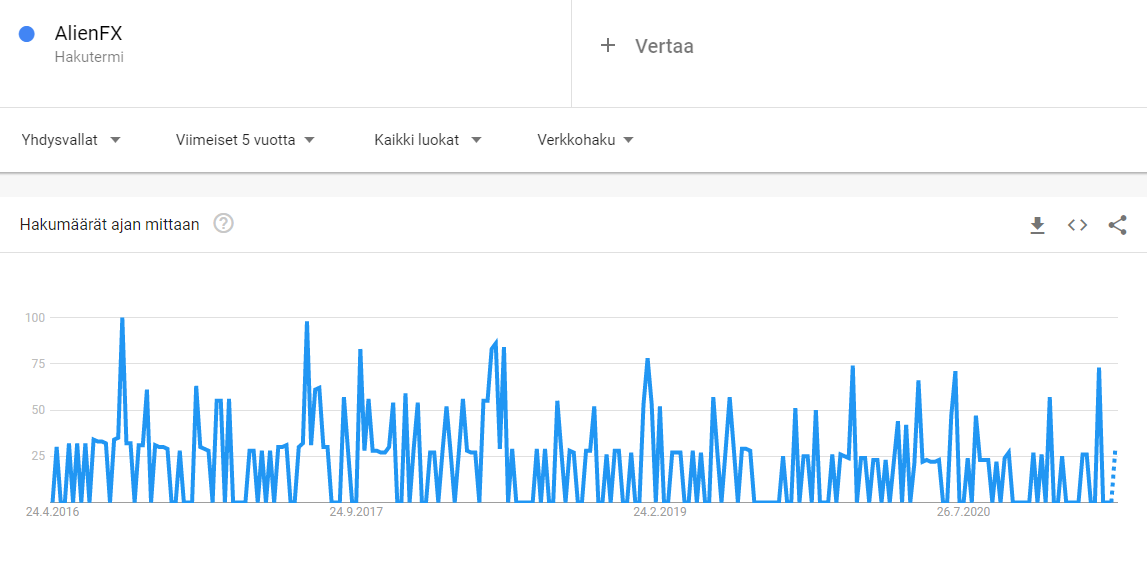
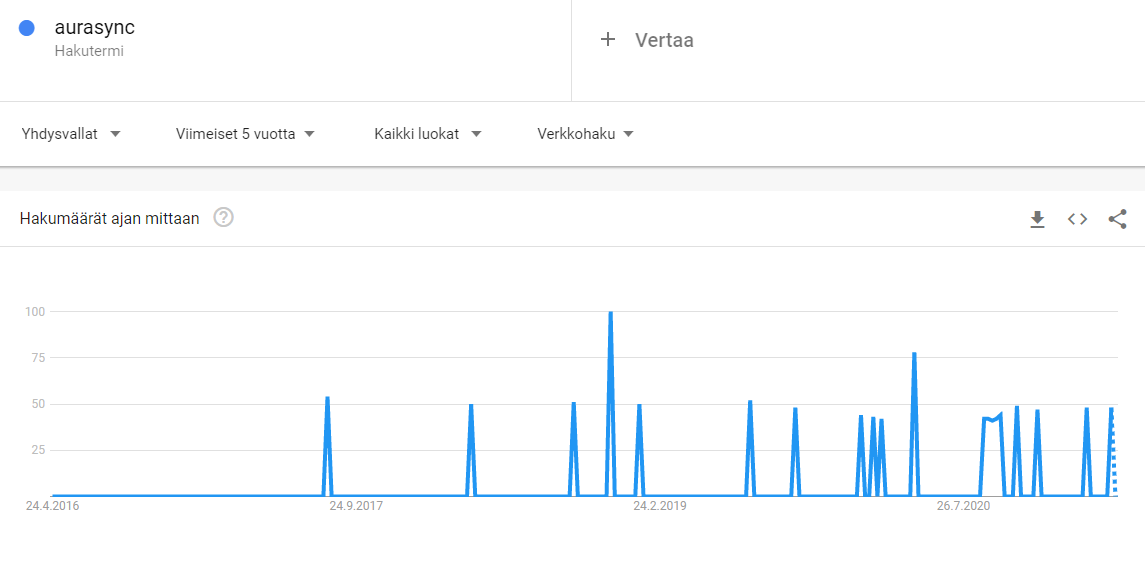

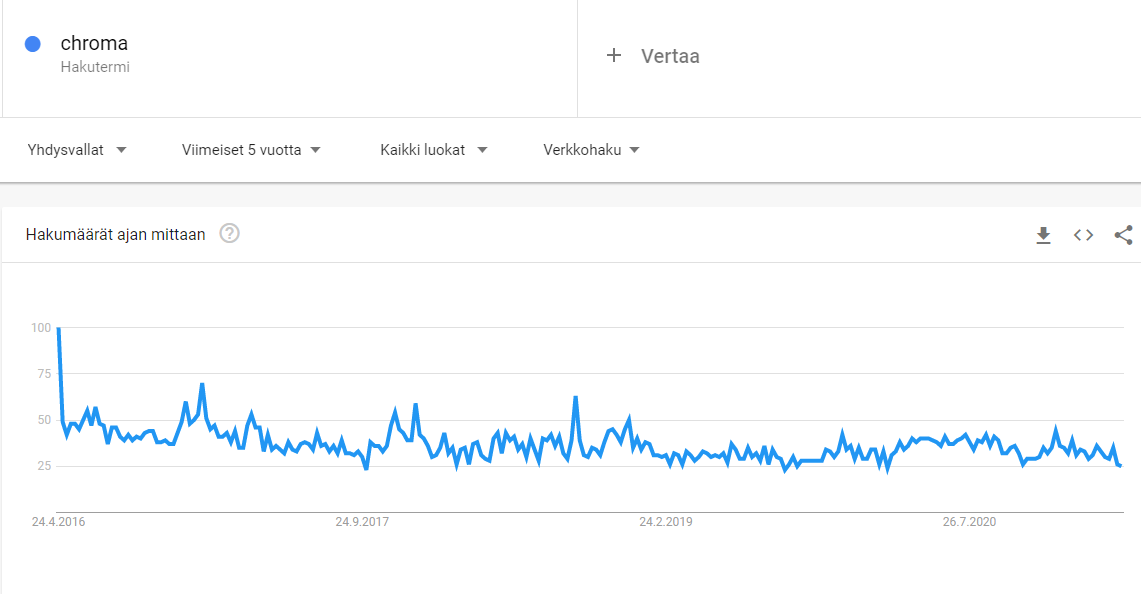
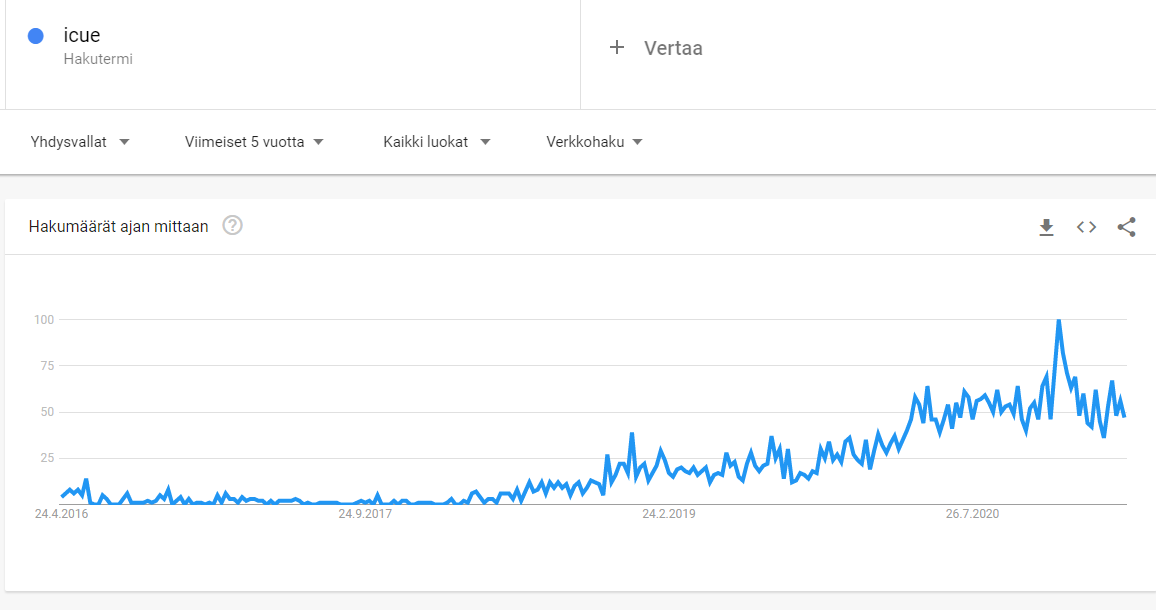
Corsair, with iCUE, is on an upward trend compared to its competitors. The general “consensus” on Reddit and elsewhere is also that iCUE is the best software. This, in turn, leads to a large number of users, which means that, for example, RGB profiles are most available for Corsair devices. This then becomes a selling point for new users, and the cycle continues.
Once you’ve bought those RGB fans, it’s worth buying a Corsair keyboard too, and headphones, etc.
This doesn’t mean, of course, that Corsair is the most popular manufacturer. Here are the subscriber counts for different manufacturers’ subreddits over time:
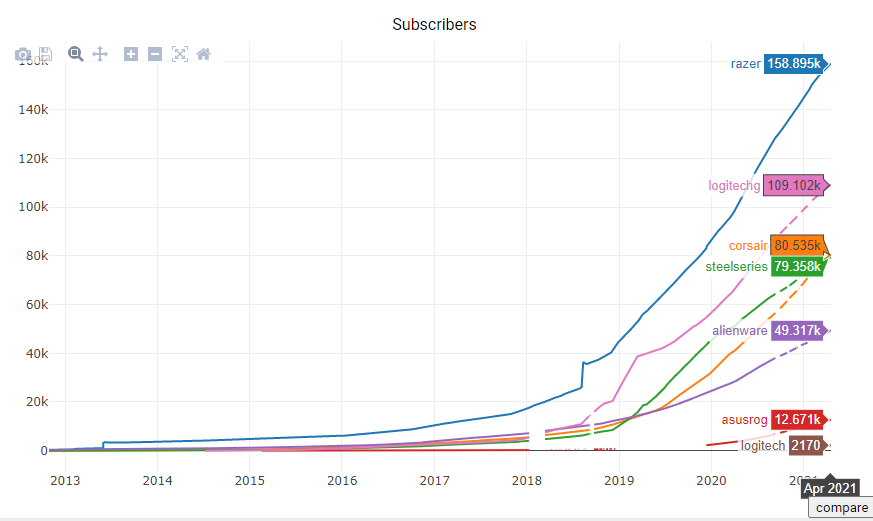
The popularity of all is growing rapidly.
Based on Google searches, annual growth (CAGR) of 6-7% is expected for Gaming Peripherals for 2021-2025, 5% for computer components, and 10.5% for the Gaming industry. So Corsair is in a relatively healthy growing industry. Component shortages may have a short-term impact.
In my opinion, finding a direct comparison for Corsair is somewhat challenging because competitors have different focuses that overlap to varying degrees. Asus is perhaps more on the hard-hardware side (motherboards, GPUs, etc.), while Logitech is a purer peripheral company, with most of its sales probably being non-gaming. Steelseries and Razer, on the other hand, don’t seem to sell memory, power supplies, etc. Razer, however, does sell pre-built computer packages.
I tried to compare the companies’ growth figures, profitability, gross margin, etc., but this is difficult because I don’t have a subscription to Bloomberg or similar. However, I did dig up the operating profit % for 2020 for a few comparisons (I do not take responsibility for the accuracy of the data):
Logitech 13.0%
Corsair 12.0%
Asus 6.05%, Gigabyte 5%
Razer -0.57% (became profitable in 2020)
Dell 11% (Owns Alienware)
It could be concluded with a quick Google search that it is clearly more profitable to make components for the outside of a computer than for the inside.
Digging up valuation multipliers was such a swamp that I won’t post them here. Let’s just say that Corsair was on the cheaper side in terms of realized results. However, there’s a big exclamation mark here when scrolling through Corsair’s Annual Report for 2020: “Net revenue was $1.7 billion, an increase of 55.2% year-over-year. Gamer and creator peripherals segment net revenue was $539.4 million, an increase of 83.4% year-over-year. Gaming components and systems segment net revenue was $1,163.0 million, an increase of 44.8% year-over-year.” Such growth figures, of course, cannot be permanent, and whether this enormous leap in revenue and profit is a permanent phenomenon or if many gamers and streamers updated their games and gear due to the pandemic, who knows.
An interesting company in any case. This is a bit of a stream of consciousness and my own thoughts. I’m not buying shares yet with this level of familiarity, especially since the cheap valuation is indeed backed by an insanely strong 2020. We’ll see…
A pretty good summary of Corsair from a few months ago:

It’s been in my portfolio for about 5 months now.
If you want to invest in this industry, I recommend checking out Turtle Beach Corporation (HEAR). It’s smaller and less known, but also cheaper and more profitable. It makes headphones and such, which were, of course, flying off the shelves last year, but it also owns the ROCCAT brand, which offers keyboards, mice, and more.
I have owned Turtle since the vaccine news in November. Of course, I should have sold during the spring peak, from which it has declined quite a bit. As a word of caution, this ended up in my portfolio based solely on a screener, and I haven’t even looked at the company very closely since. Someone was just looking for comparisons, so here’s one.
This indeed seems to be the case, the 2021 guidance given in conjunction with the Q4/2020 results is barely above the 2020 figures. I wonder how that was justified 
I skimmed through Corsair’s Q3/2020 and Q4/2020 presentations and the November Investor Presentation slides, all three have almost the same content, just Q4/20 probably contains everything essential on its own:
Q4/20, i.e., the latest earnings release (Feb 9, 2021)
Q3/20, i.e., Corsair’s first earnings as a listed company (Nov 10, 2020)
Investor Presentation (Nov 30, 2020)
And the company was listed on September 23, 2020
Market Cap ~3BUSD
From an investor’s perspective, Corsair’s main point seems to be its market leadership in the growing PC gaming and streaming market. If one believes in the continued growth of this market, the market leader is a logical investment for it.

I’ve picked the most interesting slides from the Q4 presentation for getting to know the company. The new public company is clearly still focusing on opening up its business to investors, as there’s plenty of space dedicated to it in the earnings release presentation. It’s worth a read, at least.
Basic information about the company and its offerings. Corsair’s products influence gaming, e-sports, and streaming:
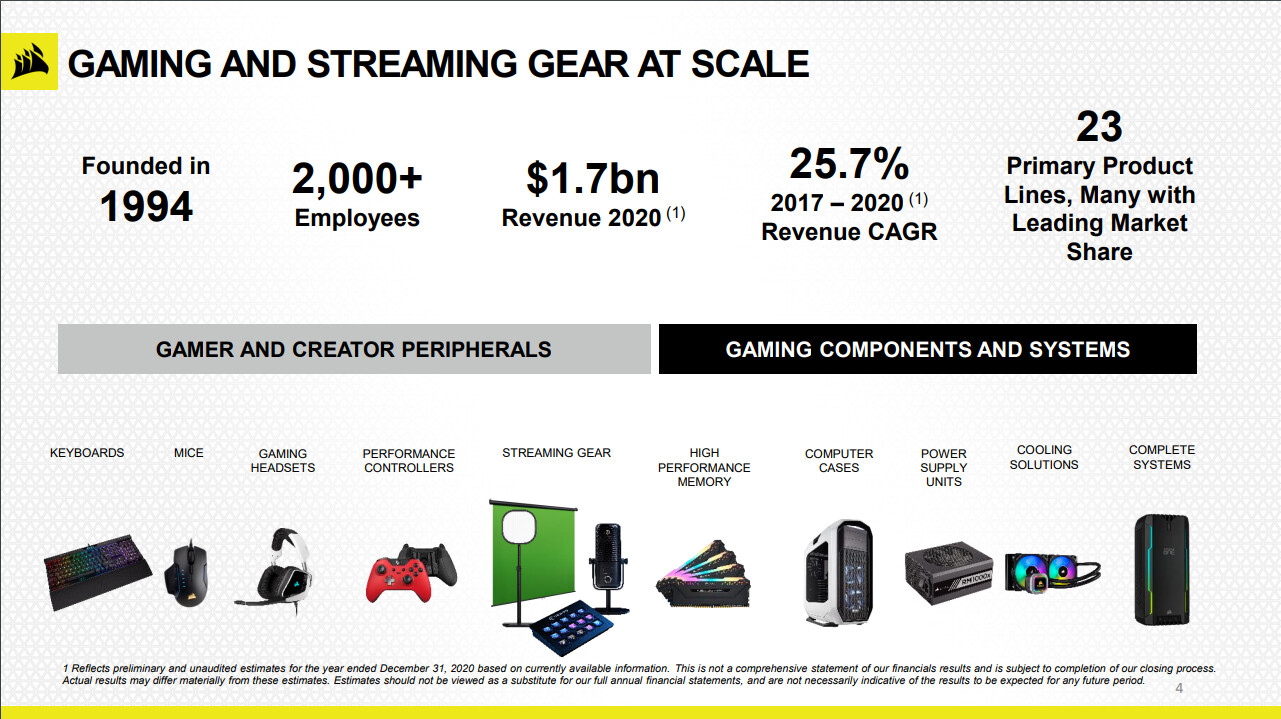
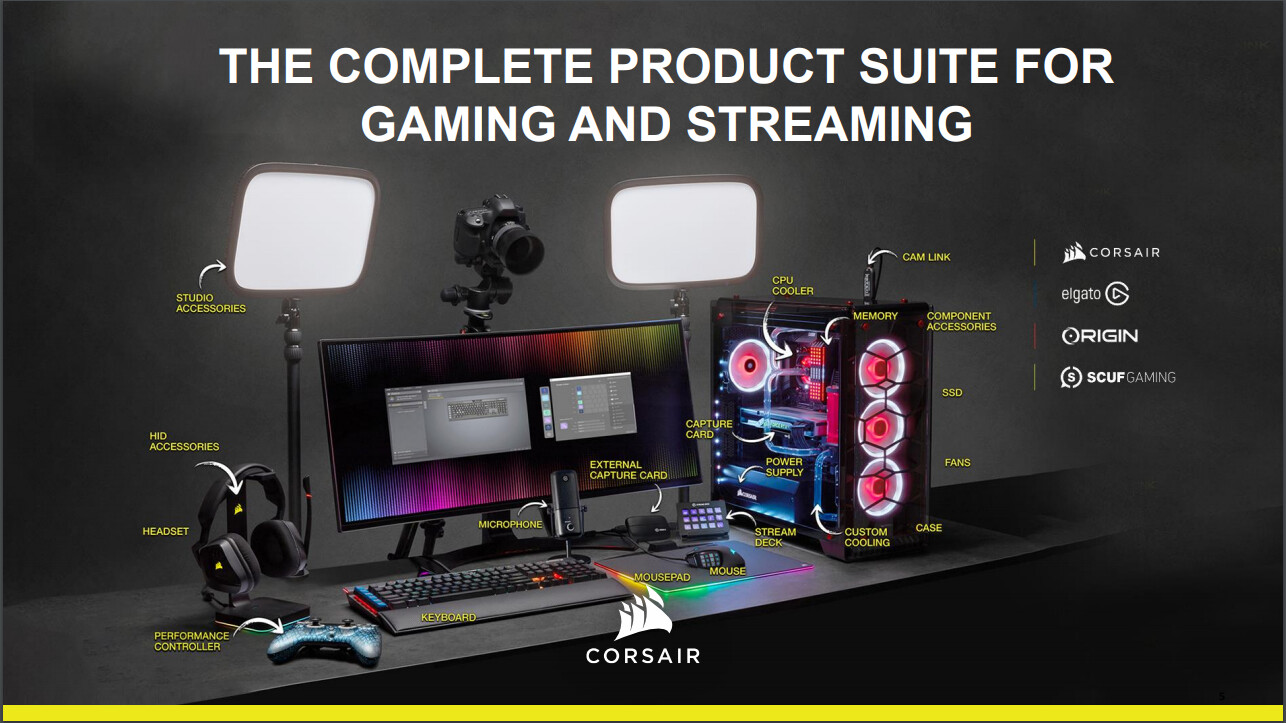
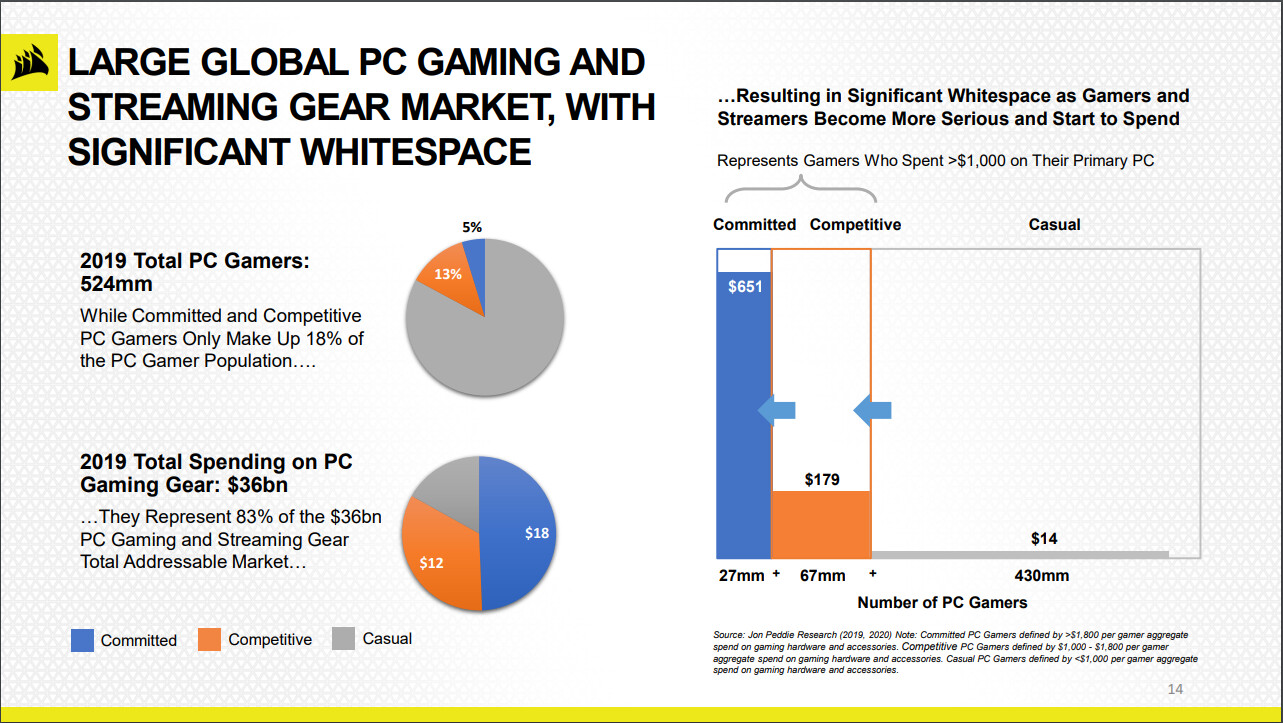
Regarding the customer base, I was surprised that 18% of PC gamers generate 83% of the PC gaming equipment market. Corsair understands this group to be its main customer base, in addition to streamers, vloggers, podcasters, remote workers…
A very convincing statement about product quality, though it’s hard to say how much value all the accolades truly hold:

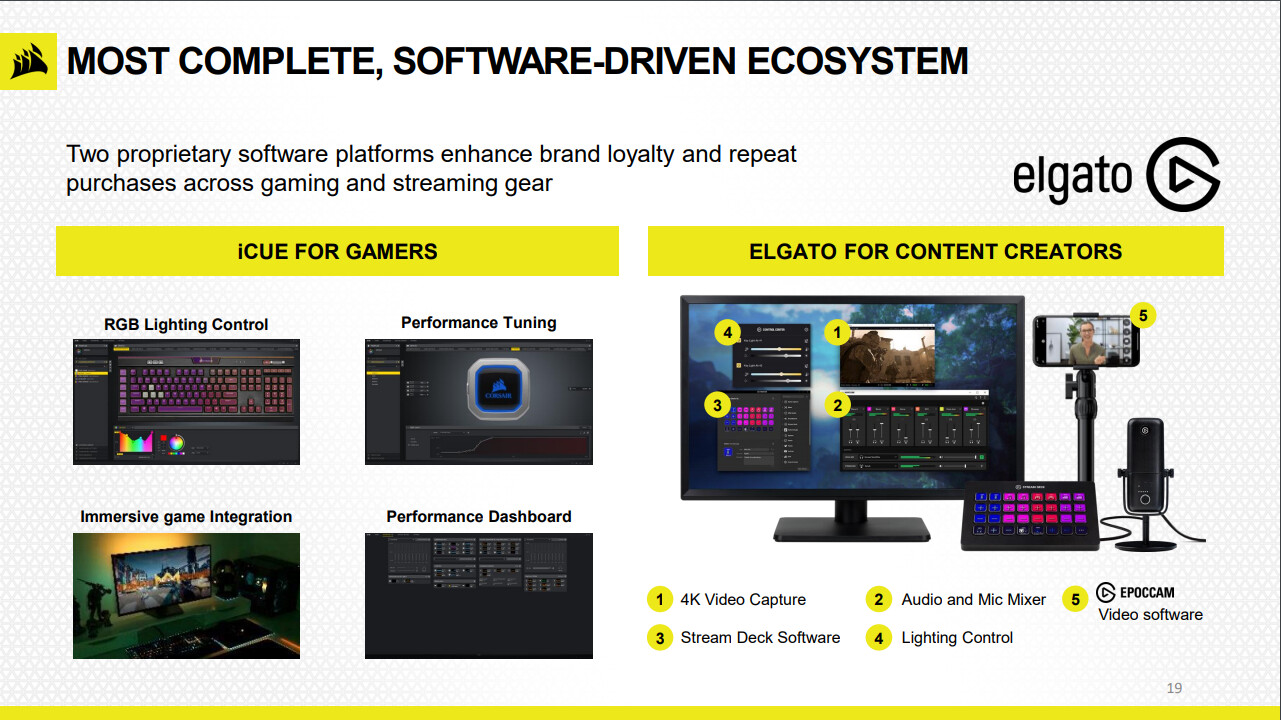
This is probably one of the magic words for investors: “Software-driven ecosystem.” Once a customer is drawn into the iCue ecosystem, as @jasso mentioned, it’s easy to retain them and sell more.
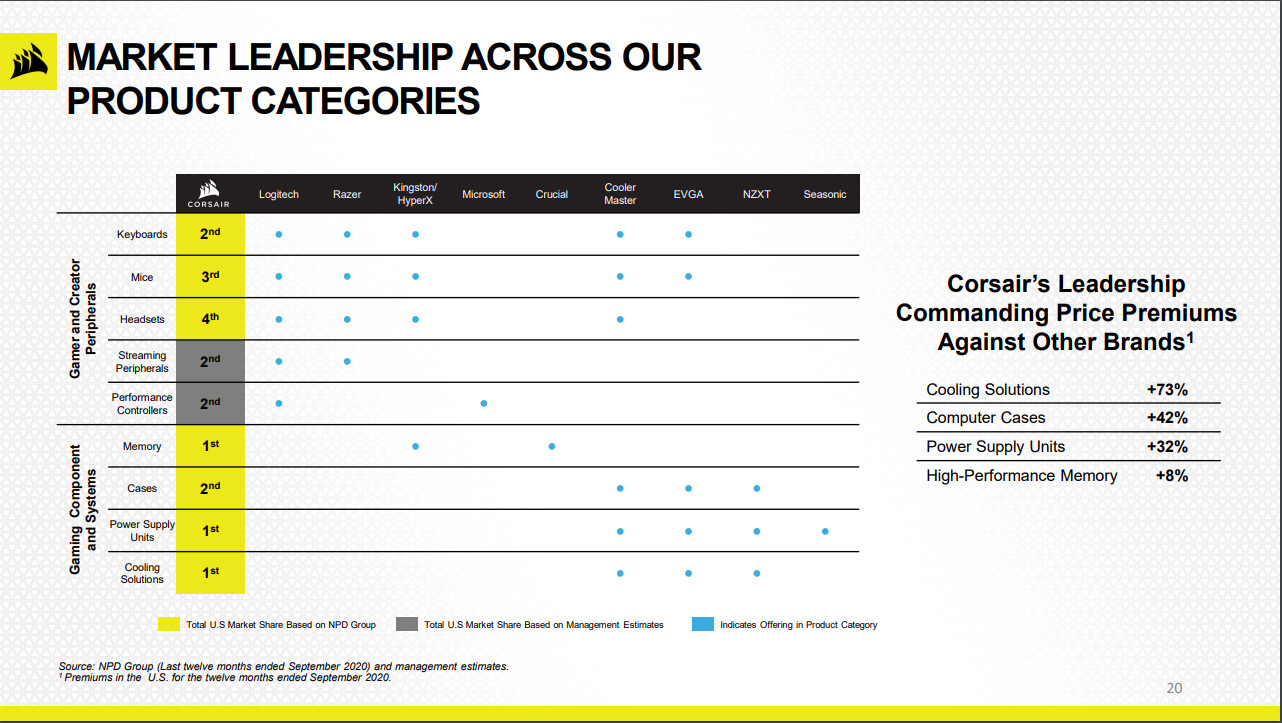
Presentation of market position and very impressive premiums for a few selected product categories:
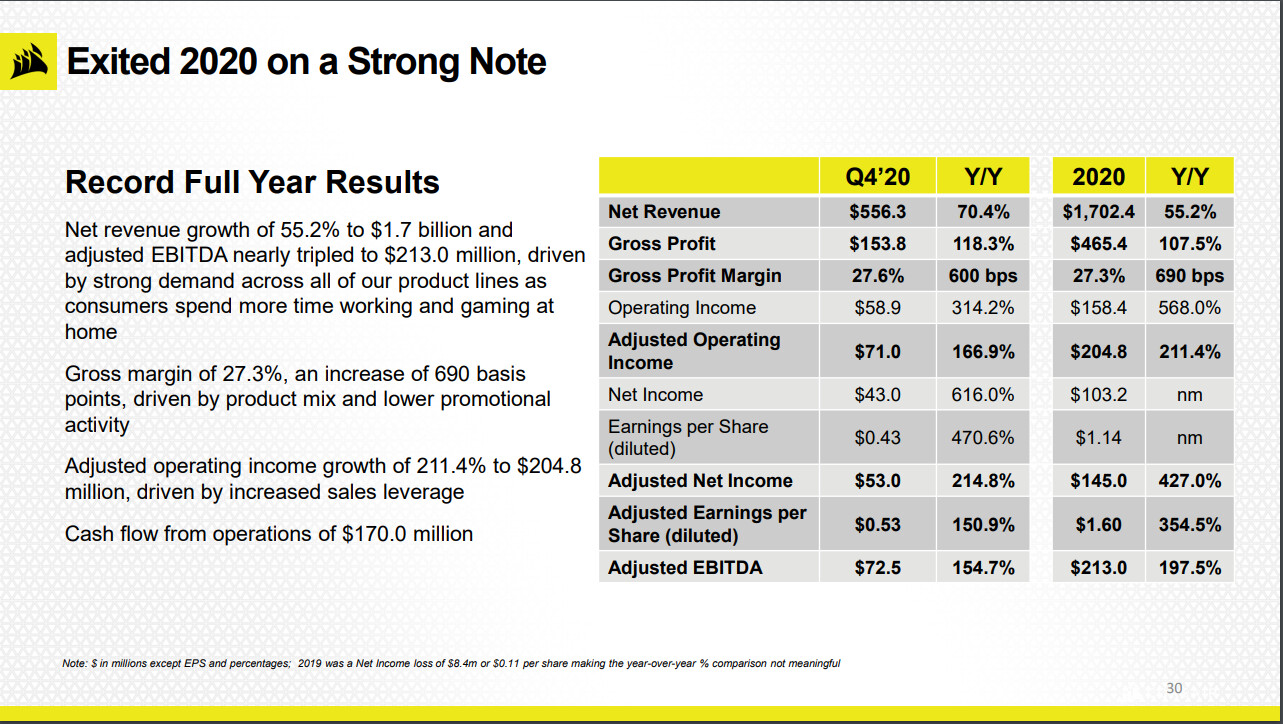
Then the numbers, all figures seem to have grown quite rapidly in Q4 and on an annual basis. The essential ones are in this picture; a more detailed explanation would be better viewed from the presentation than copied here  Visually pleasing slides, worth a look (link to presentation)
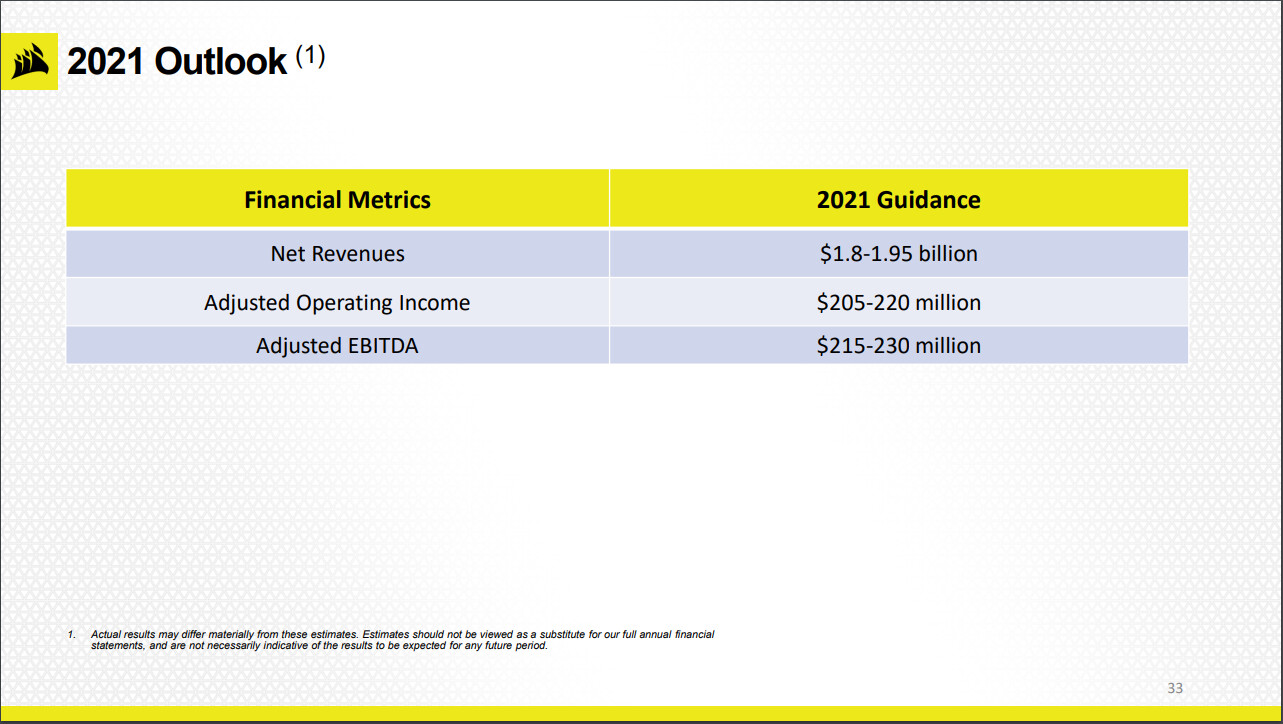
And the shy-sounding 2021 guidance, which would mean YoY revenue growth of 5.5% - 14.7% and EBITDA growth of 0.9% - 8.0% if realized:
After the Q4 results, several analysts raised their target prices on Feb 10, 2021, and the consensus now appears to be $45.11 compared to the current price of $32.16.
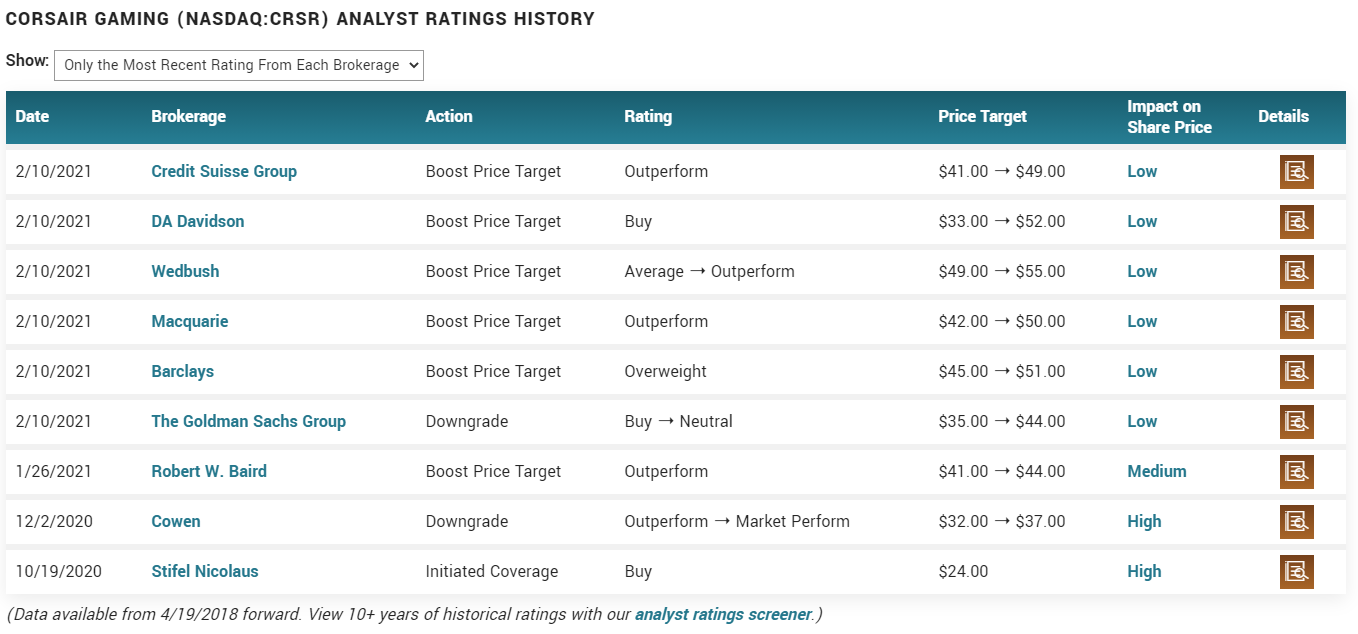
(source https://www.marketbeat.com/stocks/NASDAQ/CRSR/price-target/)
Yes, at first glance, it seems there’s a reasonably priced market leader in a growing market available. I’m particularly interested in the iCue ecosystem and its ability to commit users to Corsair. You can get a quick look at it on Corsair’s website: Challenge Validation
The “streaming” that @tonimerkki mentioned is what caught my eye a couple of months ago. I also have a Corsair STRAFE RGB keyboard, a Corsair power supply in my computer, and I think the RAM was Corsair too (it’s been years since I last updated it…). However, I see bigger growth opportunities in streaming equipment. Wave Panels (acoustics), Wave mics, Stream Decks, etc.
However, I hesitated to invest in this because (as mentioned in @niko_naakka’s posted video) the company’s debt amount > cash amount. The valuation assumes that sales would continue to be as good and grow even further. This perhaps explains the company’s “undervaluation”, risk <=> return.
…I wish corona would go away so I could go to freshman parties and ask teenagers if RGB components are still worth the extra price. “Would you trade a crate of Monster for an RGB keyboard if you had to choose one?”
I personally had two motherboards explode back in the day (2003) when a Corsair or Seasonic power supply decided to die. First, the original motherboard went bad, and then a new motherboard broke on the first start, after which we started looking for the fault elsewhere than a faulty motherboard.
Nowadays, my computer has Corsair, and the quality has, quite obviously, improved significantly since those days.
I’ve also been researching this company for a while now and almost started a thread for it myself about a month ago. Luckily, someone else was more courageous than me!
I agree with @ElmoM that the valuation already has some growth expectations priced in, but if revenue stays at the level of previous quarters and grows moderately from there, I think the stock is very fairly priced. I did a quick DCF calculation for Corsair using financial statements from recent years and the outlook mentioned in them. Here are a couple of points and other thoughts that came to mind while doing the calculation:
- The company guides/forecasts revenue to be $1.8 - $1.95 billion, which would mean approx. 5%-15% growth compared to 2020 ($1.70 billion)
- EBITDA is forecasted to be between $215-$230 million, which at the current price would mean an EV/EBITDA multiple of about 13.7-14.7
The EV/EBITDA multiple isn’t directly alarming, and measured by last year’s EBITDA ($200 million), the multiple at the current price is 15.8. (CRSR - Corsair Gaming Inc Ordinary Shares Valuation | Morningstar)
Partially based on the company’s guidance, I quickly put together a DCF calculation which resulted in approximately $47 per share. There are many question marks in the calculation, especially given Corsair’s very short stock market history. And there can indeed be errors in the calculation, but it has been carried out according to general practices and modeled after Inderes’ calculations.
In the calculation, I assumed 5% growth for this year and for 2022, after which growth would be around 2% until 2031. These figures are significantly lower than what the company has guided for growth. For terminal revenue growth, I put 2% in this calculation. Perhaps the biggest question mark is how well the company can maintain its margins. However, in 2019, EBIT-% was 2.2%, and in 2020, it jumped to 9.3 percent. If margins remain close to ten percent and growth is even that moderate few percent, which I believe the company can achieve at least in the next two years based on previous quarters, then I don’t think the company is very expensive.
Ihre Datenschutzeinstellungen Analysts following Corsair have forecasts ranging from $37-$55.
A few words about the product itself: from what I’ve researched about Corsair’s offerings, they have broadly expanded into all gaming-related equipment, from memory modules and other computer components to monitors and headsets. In addition, to my knowledge, Elgato’s streaming devices are market leaders in many ways and are used by many popular streamers/YouTubers. So, the product portfolio is very broad, and especially in streaming-related software and devices, there don’t seem to be many competitors.
These are my preliminary comments (I can add more later from my notes if anything was missed in this short summary), and I will actively follow this thread.
I bought a small position in Corsair at around $33 a few weeks ago, perhaps initially for a few months / half a year swing, but if Q1 looks promising, I might add more if the prices are right.
Edit:
This comment from the CFO also remained very positive in my mind from the 2020 report:
“We are extremely pleased with our financial performance in the fourth quarter. We have paid off an additional $50 million in debt during the quarter, making the total debt repayment $190 million for 2020. We expect to continue to use our operating cashflows to reduce our debt and continue to invest in growth.”
Actual results (vs consensus):
Revenue: $529.4m ($449m)
Gross margin: 30.3% (27.1%)
EBITDA: $80.4m ($50m)
EPS: $0.58 ($0.33)
Raise FY sales guidance to $1.9-$2.1b and $245-$265m EBITDA.
Really good numbers though. 
With a very simple calculation where EPS would remain the same throughout the year (0.58 x 4), the full 2021 EPS would be $2.32. One couldn’t really expect EPS to fall much. As of writing, the pre-market price is $34.14, which would mean a P/E ratio of 14.71, and with EBITDA guidance ($245-$265 million), EV/EBITDA would be 12-13x with quick calculations.
For a company guiding for 11%-23% revenue growth and 15%-24.5% EBITDA growth this year, it feels quite affordable at these multiples. Especially the improvement in EBITDA margin in an even better direction really gave me confidence. Debt is still being paid off and demand is very strong.
Gamer and creator peripherals YoY growth ->131%
Gaming components and system YoY growth → 51%
The “Gamer and creator peripherals” segment also has higher margins, so its insane growth really gets me excited!
You said it, let’s put these here as well:
Gamer and creator peripherals: RV $176 million, Gross Margin 39.1%
Gaming components and systems: RV $353 million, Gross Margin 25.9%
My face when the counter is -3.5%
now I don’t understand. Of course, the strong power of Nasdaq is pulling this down as well, but I didn’t expect such a negative reaction 
An interesting company; I’ll be accumulating about 10,000 shares of this in my portfolio in the coming years through options. Currently, my thought is to sell all shares immediately upon vesting, but the earnings growth is such that I might actually consider holding onto this. Additionally, I have insight into the company’s future endeavors and I like what I see.
This is not a buy recommendation.
everyone knows that RGB lights surely increase FPS, so presumably the answer would be yes. From my own feeling, quite a few people have those Corsair gadgets in some form. Go figure. But you’re right, I should go ask on Assy, that’s where the industry experts/consumers are.