There wasn’t anything today, at least. TP is still €41.
2 Likes
Basware Oyj - Managers’ transactions: Alwin Schauer | Kauppalehti
Basware Oyj - Managers’ transactions: Perttu Nihti | Kauppalehti
Basware Oyj - Managers’ transactions: Mogens Pedersen | Kauppalehti
3 managers started buying. And it’s no wonder why.
4 Likes
What was wrong with the result when it calculates from day to day, anyway?
Wasn’t there an overshoot in the result and a strong order book for 2022?
Quiet in the Basware thread… What are your thoughts on Basware? The price has come down a lot, and it’s almost reaching the COVID dip, even though the Q4 results were quite good…
3 Likes
I’ve been wondering the same, as it’s almost halved in 6 months. They also guided for a good year and indeed exceeded expectations.
There’s also the possibility of a corporate restructuring; there was a story about it in KL news this week, I think.
1 Like
At least a really big difference in valuation compared to a significant benchmark, Coupa, which is listed in the United States. Coupa’s annual revenue is $540 million and its valuation is $8.5 billion, meaning its valuation is over 15 times its revenue. And Coupa’s stock has even dropped by 2/3 in price over the year…
Yes, Basware is very affordable if someone wants to come and buy it out. The value of Basware’s open and global e-invoice network, built over decades, is strategically significant, so if growth slows down or product management / innovation execution otherwise starts to falter, a new happy owner will surely be found and the premium from these levels will be truly significant. I also understand that Basware has focused on companies of a specific size in the market and is very strong in certain industries, so in that sense, it could be a good acquisition for Coupa, for example.
For comparison, SAP once bought Ariba, which had a revenue of approximately $440 million, for a valuation of $4.3 billion. Although Ariba’s annual growth was faster than Basware’s, it was also a cloud-based network and procurement invoice operator.
10 Likes
Can we finally get rid of this?
Offer consideration 40.1 EUR, almost double yesterday’s price…
A few years ago, Tradeshift was planning to offer something like 46 EUR or so.
13 Likes
Congratulations to us owners. A bit low price or what do you think since the company has improved a lot?
This is what pushing down the share price meant.
5 Likes
Well, this was a surprise found in the Easter egg. This was completely expected, a relatively large premium, but the share price has also fallen. And it won’t be the last takeover bid on the Helsinki stock exchange, as geopolitical crosses reduce valuations. Consolidation in the industry will continue, that’s clear.
The valuation in the offer is still affordable compared to Coupa Software, where, even with the fallen share price, the valuation is almost 10 times revenue. Compared to this, Basware’s valuation should be 1.5 billion, but on the other hand, growth has stumbled in recent years, and there’s a slight hint that product leadership is no longer at the same level as it was in its best years.
I’m selling these shares today, as there will surely be attractive opportunities in the stock market this year.
Good luck to others who have been sitting on their hands!
18 Likes
Coupa’s valuation is indeed astronomical, even though its share price has dropped from 280 USD to 105 USD in a year.
Purely from the corner of my eye, it has also seemed that Coupa’s growth has relied heavily on acquisitions.
Coupa 2022 revenue guidance: 840 MUSD = 760 MEUR
Coupa market cap (105 USD/share): 8.0 Mrd USD = 7200 MEUR
Basware: 2021 revenue 153 MEUR
Basware market cap (40.1 EUR/share): 620 MEUR
Indeed, from the above figures, it can be concluded that even at Coupa’s reduced valuation level, Basware’s market cap would be the 1.5 Mrd EUR you mentioned, or 94 EUR/share.
Well, Basware is Basware and Coupa is Coupa.
But perhaps we can keep the window open for a competing offer.
The acquiring party is, however, what you might call “money men,” who actually already hold a 23% stake in Basware, meaning they also stand to gain IF a competing offer were to emerge.
Of course, as interest rates rise, there’s less willingness to pay as lavishly for these companies that don’t generate actual profits as there was during negative interest rate periods.
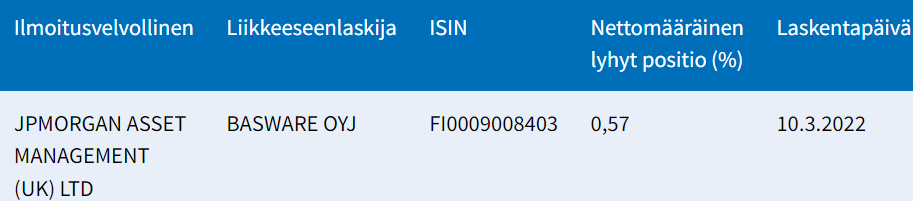
JP Morgan has a reported short position open; FIVA publishes positions >0.5%. Smaller positions are likely beneath the surface as well.
Since the bidders and those who have given their approval already hold 56.27% of the shares, that 0.57% short has some scraping to do, meaning 1.3% of “free” shares, if they are not otherwise covered in some way.
3 Likes
The lowered valuation had, of course, increased the probability of a tender offer, but these always come as a surprise  There is indeed a good premium included compared to the current share price, but in relation to the historical median valuation, we are below it. Still, I see this as a good alternative for owners - here’s a quick comment on the tender offer

7 Likes
So you’re not expecting the price to be raised or a competing offer to emerge?
Personally, I do think the price is a bit on the low side.
Oh crap, I’ve been watching for a couple of weeks to see if the stock price would stop bleeding around €20, and I planned to buy if it did (which it strongly seemed to be doing). I’ve previously made a 100% profit by buying at these levels. This time, unfortunately, it looks like I missed out unless someone randomly sells it this morning without reading the announcement.
1 Like
Of course, it’s always possible, but so is the failure of the offer, which has already happened once with Basware (the reason was never disclosed). I don’t know what kind of due diligence (DD) may have already been done, but there are risks in the other direction as well. I, myself, will sell at this point, but you might be right that an auction is also possible.
3 Likes
Emma interviewed Antti about the tender offer.
-Topics-
00:00 Initial reaction to the tender offer for Basware
00:40 Valuation of the tender offer
01:41 Probability of the tender offer going through
7 Likes
Is this story over now? Having been involved since the initial offering, I certainly can’t be satisfied with this outcome if this is the end result. I would have wanted to see the company succeed/break through as a listed company, and be a shareholder myself. The redemption price is certainly high “at today’s rate,” but as already mentioned here, you only have to look back a year to see that the valuation was the same. So the premium might warm you for a moment, like peeing your pants in winter, but in the longer term, the premium/peeing doesn’t seem like such a good idea anymore…
2 Likes
In my opinion, the premium was very small or non-existent.
However, major shareholders have agreed to it.
For many, many years, the value of the company’s operations was hidden. Revenue-based valuation without profitability. It just didn’t take off. A speculative investment, thank you for that!
Thumbs up, hoping for a competing offer to start a bidding war. I believe this company has been on others’ radar as the share price has hovered around 20 euros. Coupa, for example, would surely benefit from top-notch invoice processing and e-invoicing functionality.
1 Like
The report combines Q1 expectations and additional comments on the tender offer:
I don’t personally see a competing offer as particularly likely, although the possibility always exists, of course.
- The buyer consortium already includes existing Basware shareholders who are deeply involved in the company → I don’t believe another group of private equity investors would be sufficiently familiar with the company to enter the bidding. This depth of understanding and the time spent monitoring the company over the years are particularly important, as I believe the buyer must trust in the progress of Basware’s growth turnaround for the offered price to be justified.
- From a competitor’s perspective, the logic of the acquisition is not very good, in my opinion, as a competitor would essentially acquire software that largely overlaps with its own software → sales synergies in certain parts of the product (purchase invoice processing + supplier/invoice intermediation network), but customer bases using two separate products and overlaps would reduce efficiency in product development.
- The most logical scenario would perhaps be another company developing parallel financial management software that wants to expand into procurement and purchase invoice management (=a new module for the buyer’s product from Basware). A comparable transaction would be SAP & Ariba, although that was already 10 years ago. In the software sector, I understand that “best-of-breed” thinking prevails, meaning the idea that creating more focused software excellently is strategically more sensible than continuously increasing the breadth of the software at the expense of the quality of each partial solution. In this light, I don’t see a competing offer as very likely from this direction either.
5 Likes