# Teleste as an Investment
**URL:** https://forum.inderes.com/t/teleste-sijoituskohteena/3952
**Category:** Osakkeet
**Tags:** teleste
**Created:** [March 10, 2020, 11:14am UTC](https://forum.inderes.com/t/teleste-sijoituskohteena/3952 "2020-03-10T11:14:47Z")
**Posts on this page:** 11
**Page:** 17
### Author:  [@TitoK](https://forum.inderes.com/u/TitoK)
#### Post date: [November 6, 2026, 7:19am UTC](https://forum.inderes.com/t/teleste-sijoituskohteena/3952/331 "2026-11-06T07:19:39Z")
A tech company whose share price is at the same level as it was in 2002. I don’t deny that over the last couple of years small steps have been taken in the business toward the better, but this company has practically never created any shareholder value. In the dot-com bubble, its market cap went through the roof just like everything else. I’m a very long-term and frustrated shareholder. Since this is organically such a difficult sector, I see no other option than consolidation.
---
### Author:  [@Kunhalvallasaa](https://forum.inderes.com/u/Kunhalvallasaa)
#### Post date: [November 6, 2026, 9:02am UTC](https://forum.inderes.com/t/teleste-sijoituskohteena/3952/332 "2026-11-06T09:02:38Z")
Yeah, I agree that with Teleste’s resources, the sector is really challenging.
Still, I’m surprised by the stock market’s -5% reaction right now; maybe there are owners who are having a bit of a “blowout”…
---
### Author:  [@Teletappi](https://forum.inderes.com/u/Teletappi)
#### Post date: [November 6, 2026, 10:39am UTC](https://forum.inderes.com/t/teleste-sijoituskohteena/3952/333 "2026-11-06T10:39:12Z")
That’s an interesting guidance revision—hopefully @Atte_Riikola will ask about this.
The upside was cut from net sales, yet they gave a fairly precise revenue forecast (previously 140–160M, now 140–145M). However, profitability guidance wasn’t cut quite in proportion (previously 7–10M, now 7–9M).
So they’re guiding for a pretty strong revenue figure for Q4, but with a terrible margin? It feels somewhat contradictory to me, especially since profitability improved substantially in Q3 while revenue declined. Usually it’s the other way around, and it’s kind of hard to grasp how profitability could swing this wildly. Surely this involves project timing among other things, but it’s still difficult to see how the bottom end of the guidance—around 45M in net sales—would generate just 1.1M euros in operating profit.
One particular point from the report also has to be highlighted: personnel expenses were down -2M in a single quarter: “Personnel expenses were EUR 8.8 (10.9) million, below the comparison period as production and net sales were weighted towards year-end.” Without knowing more of the details, at first glance it looks like quite an impressive use of workforce flexibility.
---
### Author:  [@Mifalt](https://forum.inderes.com/u/Mifalt)
#### Post date: [November 6, 2026, 12:23pm UTC](https://forum.inderes.com/t/teleste-sijoituskohteena/3952/334 "2026-11-06T12:23:19Z")
A couple of explanations come to mind:
1. Since the North American can was kicked down the road, it wasn’t “ruining” the Q3 margin? As deliveries accelerate, margins will decline because they were sold at a lower margin?
2. Cheaper components were still available, but going forward, new inventory cannot be sourced at that price?
---
### Author:  [@Kunhalvallasaa](https://forum.inderes.com/u/Kunhalvallasaa)
#### Post date: [November 6, 2026, 2:23pm UTC](https://forum.inderes.com/t/teleste-sijoituskohteena/3952/335 "2026-11-06T14:23:26Z")
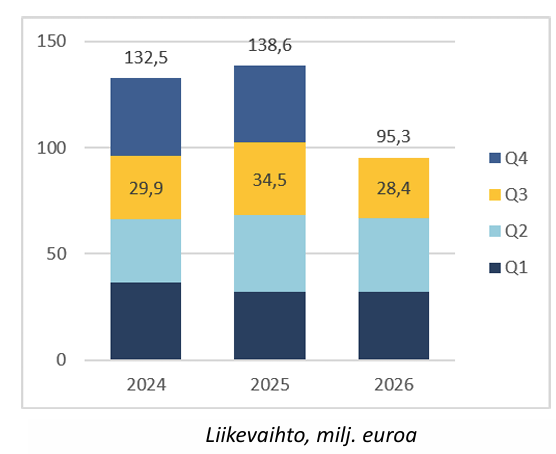
Q3 was indeed exceptionally sluggish in terms of revenue.
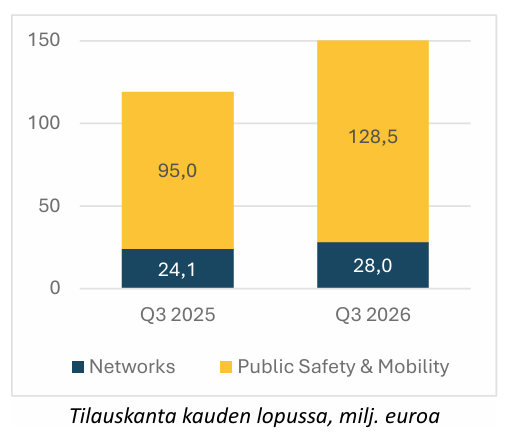
However, the order book is solid for both segments.
Now we just need a strong Q4, and it’ll turn out to be a decent year.
---
### Author:  [@Sijoittaja-alokas](https://forum.inderes.com/u/Sijoittaja-alokas)
#### Post date: [November 6, 2026, 3:49pm UTC](https://forum.inderes.com/t/teleste-sijoituskohteena/3952/336 "2026-11-06T15:49:26Z")
**Atte** interviewed Teleste’s CEO **Esa Harju** right after the earnings release 🙂
https://www.youtube.com/embed/sF2DuzfDz_8
**Topics:**
(00:00) Introduction
(00:11) Q3 Highlights
(02:26) Networks segment & North American performance
(04:38) Developments in Europe
(06:08) Public Safety and Mobility
(07:40) Agreement with Siemens
(08:57) Component shortage & rising prices
(10:50) Outlook
---
### Author:  [@Mifalt](https://forum.inderes.com/u/Mifalt)
#### Post date: [November 6, 2026, 4:48pm UTC](https://forum.inderes.com/t/teleste-sijoituskohteena/3952/337 "2026-11-06T16:48:13Z")
Well, that’s certainly also because there are simply no buyers. Earnings report day and a measly 24,000 shares changed hands. That is a really small amount.
The top 100 own around 80% of the company, so I guess it’s also a kind of liquidity problem. Hardly anyone wants to buy more, but you can’t get rid of a larger block on the market either without causing a bigger drop.
I’ve asked this directly too, but when is the company going to start generating cash for investors? For the last 25 years it’s been mixed, and this year too the company is among the bottom ~10% worst performers. Since market liquidity is affected by visibility, what does Teleste intend to do about it?
Believe it or not, Tokmanni is down less YTD. Not a great point of comparison, but things have gone moderately “wrong” there and yet I don’t see Teleste the same way, even though they’re in the same boat.
---
### Author:  [@Sijoittaja-alokas](https://forum.inderes.com/u/Sijoittaja-alokas)
#### Post date: [November 7, 2026, 10:16am UTC](https://forum.inderes.com/t/teleste-sijoituskohteena/3952/338 "2026-11-07T10:16:45Z")
To our delight, **Atte** put together a company report on Teleste on Saturday following Q3 🙂
> We reiterate our Accumulate recommendation for Teleste, but adjust our target price to EUR 3.9 (prev. EUR 4.2). Q3 revenue fell clearly short of our expectations due to deliveries shifting into Q4, but strong profitability levered earnings up to the level of our expectations. We made minor cuts to our forecasts, as uncertainty still lingers over the investments of the two largest North American customers in Networks. The strong performance of Public Safety and Mobility partially offsets this. Based on our forecasts for next year, Teleste’s valuation is very low (2027e EV/EBIT 7.4x) if the earnings growth materializes. However, the uncertainties surrounding this still keep our view slightly restrained at this stage.
> **[Teleste Q3'26: Eteenpäin mennään epävarmuuksista huolimatta - Inderes](https://www.inderes.fi/research/teleste-q326-eteenpain-mennaan-epavarmuuksista-huolimatta)**
>
> Ensi vuoden ennusteillamme Telesten osakkeen arvostus on hyvin matala (2027e EV/EBIT 7,4x), mikäli tuloskasvu toteutuu.
---
### Author:  [@Atte\_Riikola](https://forum.inderes.com/u/Atte_Riikola)
#### Post date: [November 9, 2026, 8:00am UTC](https://forum.inderes.com/t/teleste-sijoituskohteena/3952/339 "2026-11-09T08:00:57Z")
Having followed Teleste for a long time, the company’s gross margin has been very difficult to pin down on a quarterly basis, and historically it has shown significant fluctuations.
The report mentions that the Q3 gross margin was supported by a favorable product and customer mix, the provision-reducing impact of orders received in certain product groups, as well as the effect of material and production cost savings, partially offsetting the increase in component prices.
If, again in Q4, lower gross margin products are delivered in high volumes, that “one-off” profitability support from the release of provisions is absent, and at the same time component price increases hit profitability harder, then the margin will definitely come down. I was wondering about this myself, but the company made it quite clear that the gross margin will decrease significantly in Q4.
---
### Author:  [@Teletappi](https://forum.inderes.com/u/Teletappi)
#### Post date: [November 9, 2026, 8:54am UTC](https://forum.inderes.com/t/teleste-sijoituskohteena/3952/340 "2026-11-09T08:54:24Z")
Most likely exactly like that. Still, that guidance is a bit peculiar. In my wishful thinking, I interpret it to mean that the €1.1M would be achieved even with a performance where the projects mentioned by Harju do not generate revenue in Q4. If, on the other hand, net sales were to reach that 140–145M range, then EBIT could be closer to €3M.
In other words, in terms of revenue, I interpret that there is a risk of a profit warning (negari), but not regarding profitability. And maybe there’s also a slim chance for a positive profit warning if everything falls into place.
I personally can’t get this year’s EPS to 35 cents no matter how I calculate it, but I’d gladly be proven wrong. On the other hand, Teleste isn’t particularly expensive even if it stops at 30 cents this year. As the balance sheet and financing costs improve, hopefully the dividend will rise quite substantially. If Teleste moves to paying out around 50% of its net income, you’d assume there would be interest (naturally assuming that the business continues progressing gradually in the right direction, as it has so far).
---
### Author:  [@EsaHarju](https://forum.inderes.com/u/EsaHarju)
#### Post date: [November 9, 2026, 10:39am UTC](https://forum.inderes.com/t/teleste-sijoituskohteena/3952/341 "2026-11-09T10:39:53Z")
Hi, I’m commenting here on the revenue vs. profit topic. Q3 profitability was supported by several favorable factors. The Q3 product and market mix was particularly strong in terms of gross margin, and lower revenue was also accompanied by a lower level of personnel expenses. In addition, strengthened orders and forecasts in a certain product category allowed for the reduction of provisions, which provided a one-off boost to the quarter’s result. For Q4, a similar earnings impact from provision reductions is not expected, nor is as favorable a product and market mix.
[Previous page](https://forum.inderes.com/t/teleste-sijoituskohteena/3952.md?page=16)