SoFi Technologies - Banking Disruptor in the US

Well anticipated. You must be on SoFi’s board of directors ; )

Well, 3 guys are leaving there:

https://investors.sofi.com/news/news-details/2022/SoFi-Announces-Changes-to-Its-Board-of-Directors/default.aspx

At least this company issues press releases. The lowered guidance unfortunately impacts profitability quite a bit. But the student loan situation is independent of the company, so let’s consider it a buying opportunity if the stock dips significantly further.

3 Likes

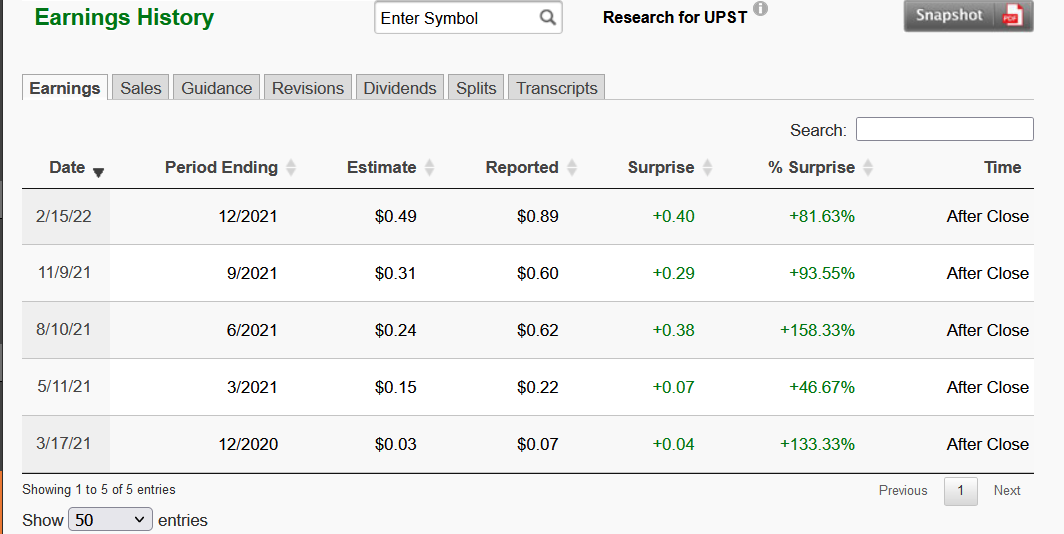
Upstart earnings coming on May 7th. A little bit of thought. Bears (B) vs Bulls (Bu). I’m putting this here because there’s no generic FinTech thread or an Upstart thread. The administration can pick the right place or perhaps this thread could be expanded into a SoFi + Upstart thread. I’ll leave that to the administration to worry about.

Let’s start with the Bears, because often they are forgotten and perhaps have more shortcomings.

B1 Brutal market sentiment. Being wrong can be really expensive. Compare yesterday’s Teladoc, which didn’t even miss by much but got hammered by 35%.

B2 Loan defaults in a certain cohort were higher than predicted by the reference model (Kroll Bond Rating Agency). Since this only targets a specific cohort, I’m not overly concerned. Who is granted a loan changes per cohort as the model is constantly evolving. It is also possible that the reference model is wrong. In addition, it is likely that payment difficulties are already priced into Upstart’s loans, so overall the loans would still be profitable. Still not good news.

B3 Upstart’s model has not been tested in this market. I don’t know how much data they have for their own model, but it’s probably a hell of a lot. By matching their own data and historical FICO data, synthetic data can be created for a bad market situation. There is a lot of research in the area of creating missing and synthetic data, and assuming that Upstart’s AI team knows their stuff, this shouldn’t be a problem. Still, there may be discontinuities in the data that make it difficult to extrapolate the model downwards to junk loans that have never been financed before.

B4 Upstart’s loans benefited from the stimulus during the Corona era. I don’t understand this. Didn’t the demand for all loans decrease when people received money at home and had no opportunities to spend?

Bulls

Bu1 Credit card companies reported strong results. Loan demand has likely also remained strong.

Bu2 The FICO system, widely used by banks today, is full of absurdities. High FICO scores are better and with a little searching you can find instructions on how to improve your FICO scores: don’t cancel your first credit card because it shortens your credit history and lowers your FICO score, or you get more points if you’ve had several different types of loans – car, home, student, and credit card. Everyone can consider the rationality of these criteria themselves.

Bu3 (StockmarketNerd) An analyst downgraded Berkshire Hills Bancorp this week citing the company’s usage of Upstart as a source of loan volume. In response, the bank (thank you to their team) published data on how its Upstart loans were actually performing. Berkshire Hills is collecting an average loan yield of 11.5% with a 5% annual net charge-off rate from Upstart-sourced loans – meaning there’s plenty of room for adequate cash flowing. … The bank also expects the proportion of its loan book via fintech partners (mainly Upstart) to triple from 1% to 3% this year.

Bu4 (StockmarketNerd) In an article published today, $UPST’s VP & GM of Auto Retail told Automotive News that its dealerships have been choosing Upstart-powered loans at “8X” the expected rate. “We had big hopes but the result was significantly more.”

Bu5 The stock price has been battered really low. The average target price is now $175, meaning an upside of 133%. However, at least Yahoo Finance doesn’t state when the target prices were set. Does anyone have a better source?

Bu6 Shorts. 35% of free float is shorted (Ortex estimate). This has even accelerated from the November lows by 5.65%.

Overall, the bulls seem to be taking this. I’d be tempted to go all-in before earnings and take out a loan on top, but I probably won’t do that, opting instead for a more moderate position increase. How much lower could the price still go? Maybe the shorts are going to release some chatter about “Upstart loans getting destroyed as interest rates rise” to drive the price even lower, allowing them to buy at 6x or even 5x.

On the other hand, I might have forgotten some Bear B? and this could sting really badly.

Disclaimer: current position 7.5% of portfolio at an average price of $97.
4 Likes

Yes, the US tech market is so toxic right now that it’s difficult to predict anything. I’ve tried to keep individual company positions relatively small for now. I’ve already taken losses from both SoFi and UPST once and have since bought back at a lower price.

With my common sense, UPST’s AI-based system should be more sensible than the prevailing FICO in all market conditions. And indeed, the auto lending side looks particularly promising. Those potential payment difficulties are likely primarily a problem for the lending bank or institution, as UPST itself does not act as a lender. Of course, it doesn’t boost the AI product’s profile if loan recipients turn out to be insolvent.

2 Likes

My biggest fears are indeed market sentiment and that the shorts know something I don’t.

If there is no secret information and I were sitting on a pile of shorts, I wouldn’t dare to go into earnings with such a huge short position. Upstart has surprised many times in the past.

Instead, before the earnings release, I would try to get an article published in a newspaper or on TV, comparing Upstart’s loans to the sub-prime loans of the 2008 financial crisis. That would make the stock price fall further, allowing me to close my shorts with a profit. For those who don’t remember, in the subprime crisis, secured mortgage loans were given to low-income individuals with the assumption that housing prices would rise, so insolvency wouldn’t matter. These loans were then sold as high-interest, AAA-rated secured loans. And then it clicked when housing prices went down and not everyone could manage their loans. Upstart’s loans are unsecured loans, which inherently have a quite high interest rate. So they are not sold as some AAA+ rated secured stuff. Banks that take on these loans understand the risks of low-FICO customers and monitor them closely.

If such an “Upstart 2022 = 2008 subprime loan crisis” story appears somewhere, with Bill Ackman or similar sharing these insights, that would be a strong Buy signal for me, at least.

2 Likes

Galileo Financial Technologies, a subsidiary of SoFi Technologies, Inc., and Mastercard on Wednesday (May 4) unveiled a multiyear strategic alliance focused on “accelerating digital transformation and improving access to financial opportunities for unbanked and underserved segments in Latin Americas and the Caribbean.”

Based on initial reactions, the market liked it.

5 Likes

Did SoFi’s Q1 results leak too early…trading was also apparently halted…
https://twitter.com/juancholmp/status/1524040060240384001/photo/1

Yeah, it seems to have gotten out because of a Bloomberg error:

https://www.barrons.com/articles/sofi-stock-earnings-51652196906?siteid=yhoof2

The decline is indeed steep. Will we go below $4 today once the halt ends?

1 Like

Yes, the US market is completely messed up, or should I say, totally headless, like UPST, which had good results. The guidance must have been what got people upset.

SoFi’s results were quite good. Growth slowed down in some aspects, but on the other hand, the full-year guidance was raised again:

2 Likes

Sofi & UPST are definitely expensive now. I’m torn about buying, as I haven’t invested in them before. However, the bears of the last few months have really pulled the rug out from under both sides, as I’ve thought “Is this it?” several times, and each time I’ve been beaten black and blue.

4 Likes

Hey, is there broader interest in a dedicated thread for Upstart (UPST)? I’m asking because the company is at an interesting stage. The market has hammered the stock, growth has stalled—but apparently only for this year. The company states that rising interest rates are eating into their growth, meaning the company has cyclicality. Additionally, the business model has caused credit risk for the company, perhaps. If there’s interest, I might consider a thread at some point. I’d be interested in understanding UPST’s situation better because the company says its business is progressing according to plan. The story is unfolding. Who would be interested in delving into UPST in its own thread?

12 Likes

I’m interested in an Upstart thread of our own. I’m invested with a fairly large weighting – well in the red after the share price crash, of course – but the company is interesting, and if they can get loans off their balance sheet and new auto and home loan products to market, the story could get back on track.

6 Likes

I would be interested, as the company seems very interesting, and the recent share price reaction was quite something. Apparently, investors were surprised that the company’s balance sheet includes loans for testing algorithms, and the risks associated with these loans are the main reason for the stock’s massive collapse.

2 Likes

Well, apparently there has always been a small number of loans in testing, but now the number of loans on the balance sheet had grown significantly as the business had stumbled a bit. If they now find a buyer for the loans and get the balance sheet back to its previous level, we will certainly see a rapid rise in UPST’s share price. According to US forums, AI works great and clearly outperforms traditional risk assessments.

Latest KRB report is out:

Upstart’s A-plus graded loans within the 700-plus FICO range have an annualized default rate of 0.6%, while the annualized default rate for all FICO borrowers with a 700-plus score is 3.4%. An Upstart A-plus graded loan in the 639 FICO score range and below (a borrower category more likely to default) sees an annualized default rate of 1.2% compared to the FICO default rate in this range of 7.7%. So clearly, Upstart scoring has been significantly more accurate than FICO so far.

2 Likes

Picked from behind the hedge

Upst was up yesterday and today because of comments made by the CFO yesterday at Barclays conference that they are no longer going to hold loans on their balance sheet.

The market will now re-rate the company higher because they will be removing the risk from loans off their balance sheet. This makes a big difference to their multiple, hence why UPST was one of the strongest stocks in a very week market.

1 Like

Alright, then start your own channel for UPST :sweat_smile: I’m interested in everything related to SoFi, but not so much in UPST’s matters.

Both have risen nicely in the last 10 days, though. Still not in the green yet :monkey:

8 Likes

Alright, now there’s a dedicated thread for Upstart!

2 Likes

Excellent interview with SoFi’s CFO. Should be a profitable company by the end of 2022 :thinking: still strong growth…

4 Likes

SoFi Technologies, Inc. Reports Second Quarter 2022 Results

Record GAAP and Adjusted Net Revenue for Second Quarter 2022
GAAP Net Revenue of $363 Million Up 57%; $356 Million Record Adjusted Net Revenue Up 50% Year-over-Year
Adjusted EBITDA of $20 Million Up 81% Year-over-Year
New Member Adds of Over 450,000; Quarter-End Total Members Up 69% Year-over-Year to Over 4.3 Million
New Product Adds of Over 702,000; Quarter-End Total Products Up 79% Year-over-Year to Nearly 6.6 Million
Management Raises Full-Year 2022 Guidance

SoFi Technologies, Inc. (SOFI) - Events & Presentations

Hyvin siis meni tähän saumaan :dancer:

13 Likes

Softbank is starting to sell off its shares. If you have faith in their operations long-term, it could be a buying opportunity. :thinking: Not a recommendation, of course :sweat_smile:

https://seekingalpha.com/news/3869466-sofi-technologies-stock-dips-after-softbank-starts-selling-off-sofi-shares

  • SoFi Technologies (NASDAQ:SOFI) shares slipped 3.1% in Monday after-hours trading after the fintech company said SoftBank Group (OTCPK:SFTBY) (OTCPK:SFTBF) decided to sell some or all of its stake in SOFI, according to a filing.
  • SoftBank (OTCPK:SFTBY) holds more than 83M of the SoFi’s (SOFI) shares outstanding, about a 9.0% stake in the company. The shares may be sold in the open market or in private transactions. In fact, the share sales have started.
  • On Aug. 5, SoftBank (OTCPK:SFTBY) sold 5.38M shares of SoFi (SOFI) at an average weighted price of $7.99. On Aug. 6, it sold 6.68M more shares at an average weighted price of $8.17 per share.
  • Last week, SoFi (SOFI) stock soared after delivering Q2 revenue and adjusted EBITDA that beat Wall Street expectations and boosted its guidance

Softbank holds 83M shares, of which 12M have already been sold. The sales will take about a week.

7 Likes

Background on the previous point: SoftBank has been doing “a bit” poorly lately.
Mr. Margin must have been on the line :grin: And Sofi then got delisted

https://seekingalpha.com/news/3869970-softbanks-23b-loss-could-push-masayoshi-son-to-reconsider-a-take-private-report

3 Likes